Japan ends the JCT small-business exemption for foreign corporations with JPY 10 million capital that start business in Japan
This page records one dated change. For the rules in Japan as they stand today, see the Japan guide →
- Jurisdiction
- Japan
- Tax
- Consumption Tax (JCT)
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 28 March 2024
- Effective
- 1 October 2024
- Instrument
- JP-ACT-Act-No-8-of-2024
- Authority
- 国会 (National Diet of Japan)
- Verified
- Fetched from official source · high confidence
Foreign corporations and other foreign businesses (国外事業者) that start taxable business in Japan, particularly those with share capital of JPY 10 million or more.
No action required — monitoring only. Foreign entities entering Japan with share capital at or above JPY 10 million must register for JCT from the date they commence Japanese business.
Act No. 8 of 2024 (passed by the Diet on 28 March 2024, promulgated 30 March 2024) tightened the JCT small-business exemption for foreign businesses, for business years beginning on or after 1 October 2024. New Article 12-2(3) of the Consumption Tax Act treats a foreign corporation that starts taxable business in Japan after the end of its base period as having no base period, so the new-corporation rule applies: if its share capital is JPY 10 million or more at the start of the business year, it is not exempt (Article 12-3(5) applies the same deeming to the specified-new-corporation rule). Article 9-2(3) was amended so that foreign businesses (国外事業者) can no longer use salary paid in the specified period instead of taxable sales when testing the exemption; domestic businesses keep that option.
What changed in detail
The FY2024 tax reform act, 所得税法等の一部を改正する法律 (Act No. 8 of 2024), passed the House of Councillors on 28 March 2024 and was promulgated on 30 March 2024. It amends the Consumption Tax Act with effect for business years beginning on or after 1 October 2024, under supplementary provisions Art. 1(3) and Art. 13(1)–(2).
- Art. 12-2(3) (new). A foreign corporation that has a base period but starts taxable business in Japan after that base period has ended is treated as having no base period. The new-corporation rule in paragraphs 1–2 then applies. If its share capital is JPY 10 million or more at the start of the business year, it is not exempt from consumption tax.
- Art. 12-3(5). The same deeming applies to the specified-new-corporation rule, which covers corporations controlled by a large group.
- Art. 9-2(3). When testing the exemption by the specified period, a business may use salary paid instead of taxable sales. That option now belongs only to businesses other than foreign businesses (国外事業者). Domestic businesses keep it.
Before the amendment, a foreign corporation whose taxable sales in Japan during its base period were low or nil could start Japanese business exempt, whatever its capital.
What it means
The rule is in force and has not been amended since. A foreign corporation with JPY 10 million or more in capital that starts selling into Japan is a taxable business from its first business year there. To issue qualified invoices it also has to register as an invoice issuer, which the exemption used to let it postpone.
The rule works on a corporation’s share capital, not its Japanese turnover, so a foreign corporation should check its capital before entering Japan. Foreign businesses with less capital can still be exempt, but they lose the salary alternative when the specified-period test is run.
Proof
その事業年度の基準期間がある外国法人(法人税法第二条第四号(定義)に規定する外国法人をいう。次条第五項において同じ。)が、当該基準期間の末日の翌日以後に国内において課税資産の譲渡等に係る事業を開始した場合には、当該事業年度については、基準期間がないものとみなして、前二項の規定を適用する。Where a foreign corporation (meaning a foreign corporation as defined in Article 2(iv) (Definitions) of the Corporation Tax Act; the same applies in paragraph 5 of the following Article) that has a base period for the business year commences business involving taxable transfers of assets, etc. in Japan on or after the day following the last day of that base period, the preceding two paragraphs apply to that business year as if it had no base period.
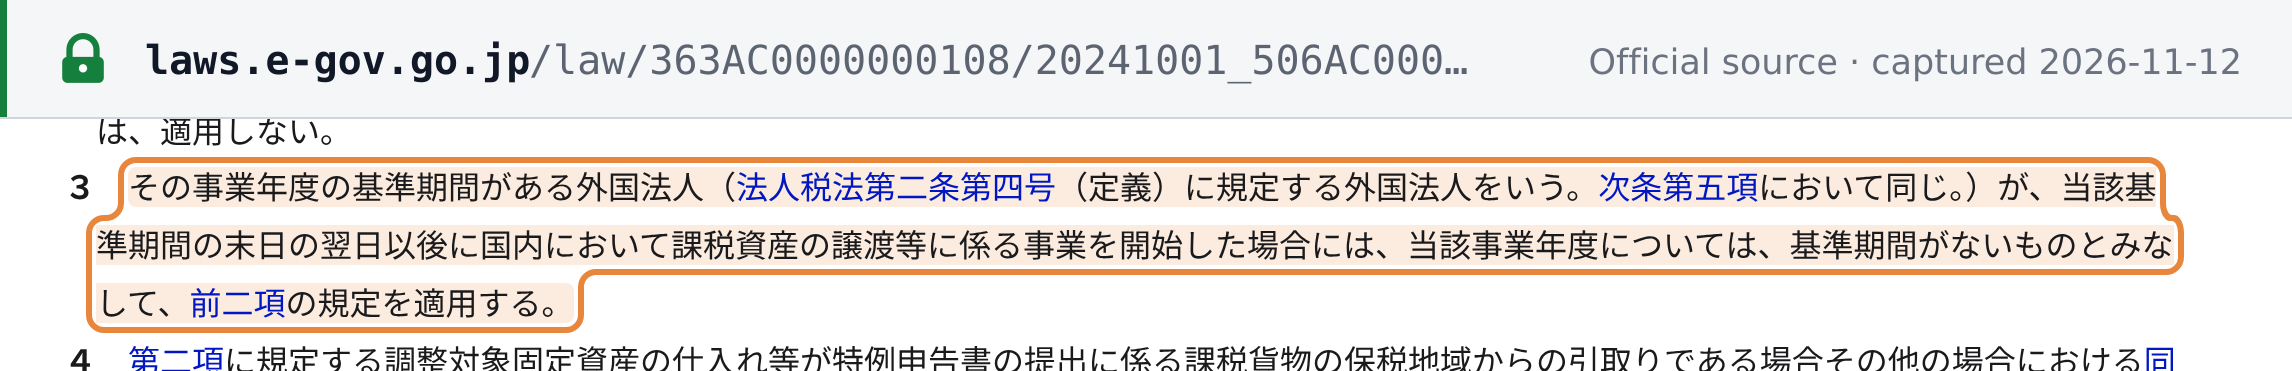 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · 消費税法(昭和六十三年法律第百八号), e-Gov law revision 363AC0000000108_20241001_506AC0000000008 (as amended by 令和六年法律第八号, in force 2024-10-01), Art. 12-2(3) · laws.e-gov.go.jp