Kenya exempts transfers of a going concern and adds fertilizer, pest-control and ethanol exemptions to the VAT First Schedule
This page records one dated change. For the rules in Kenya as they stand today, see the Kenya guide →
- Jurisdiction
- Kenya
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 13 December 2024
- Effective
- 27 December 2024
- Instrument
- KE-ACT-12-2024
- Authority
- National Council for Law Reporting (Kenya Law)
- Verified
- Fetched from official source · high confidence
Sellers and buyers of businesses as going concerns; suppliers of fertilizers, agricultural pest control products and their inputs, denatured ethanol and textile raw materials; suppliers to the Kenya Defence Forces and DFWS.
No action — monitoring only.
Tax Laws (Amendment) Act 2024 (Act No. 12 of 2024, Kenya Gazette Supplement No. 215, 13 December 2024; assented 11 December 2024; in force 27 December 2024), s.21, amends the VAT Act First Schedule: adds Part II para 35 (transfer of a business as a going concern exempt); adds Part I paras 149-154 (inputs for and agricultural pest control products, fertilizers of Chapter 31 and fertilizer inputs, denatured ethanol 2207.20.00, textile raw materials of 5407/6309); replaces paras 57 (goods for official use by KDF, DFWS, NIS and National Police Service) and 101 (beverages supplied to the Defence Forces Welfare Services); replaces para 69 (tariff 4703.21.00 for diaper and sanitary-product manufacture), deletes paras 70 and 114, and replaces the para 146 proviso.
What changed in detail
Section 21 of the Tax Laws (Amendment) Act, 2024 (No. 12 of 2024, Kenya Gazette Supplement No. 215 of 13 December 2024; assented 11 December 2024; commenced 27 December 2024) amends the First Schedule (exempt supplies) to the VAT Act, CAP 476.
In Part II it inserts paragraph 35: transfer of a business as a going concern.
In Part I it:
- inserts paragraphs 149 to 154: imported inputs and raw materials for manufacturers of agricultural pest control products; agricultural pest control products; fertilizers of Chapter 31; inputs or raw materials for fertilizer manufacturers; denatured ethanol of tariff 2207.20.00; and goods of Chapters 5407 and 6309 imported as raw materials for textile manufacture, each on the relevant Cabinet Secretary’s recommendation or approval where stated;
- replaces paragraph 57 (goods for official use by the Kenya Defence Forces, the Defence Forces Welfare Services, the National Intelligence Service and the National Police Service) and paragraph 101 (beverages supplied to the Defence Forces Welfare Services);
- replaces paragraph 69 (tariff 4703.21.00 for diaper and sanitary-product manufacture), deletes paragraphs 70 and 114, and replaces the proviso to paragraph 146.
The pest-control and fertilizer items moved here from the zero-rated Second Schedule under section 22 of the same Act.
What it means
The going-concern exemption is the item with the widest reach: a business sale in Kenya no longer carries VAT on the transferred assets, which removes a cash-flow cost from acquisitions. Other parts of the amendment did not last. The Finance Act 2025 (ke-vat-fa2025-first-schedule) deleted paragraph 154 (textile raw materials) six months later, replaced paragraph 101 again and cut off the paragraph 146 investment exemption at 27 December 2025. The Finance Act 2026 (s.32) then replaced paragraph 146 again from 1 July 2026, with a new investment exemption and no end date. Read this record as the December 2024 position, superseded in part, not as the current schedule.
Proof
35. Transfer of a business as a going concern.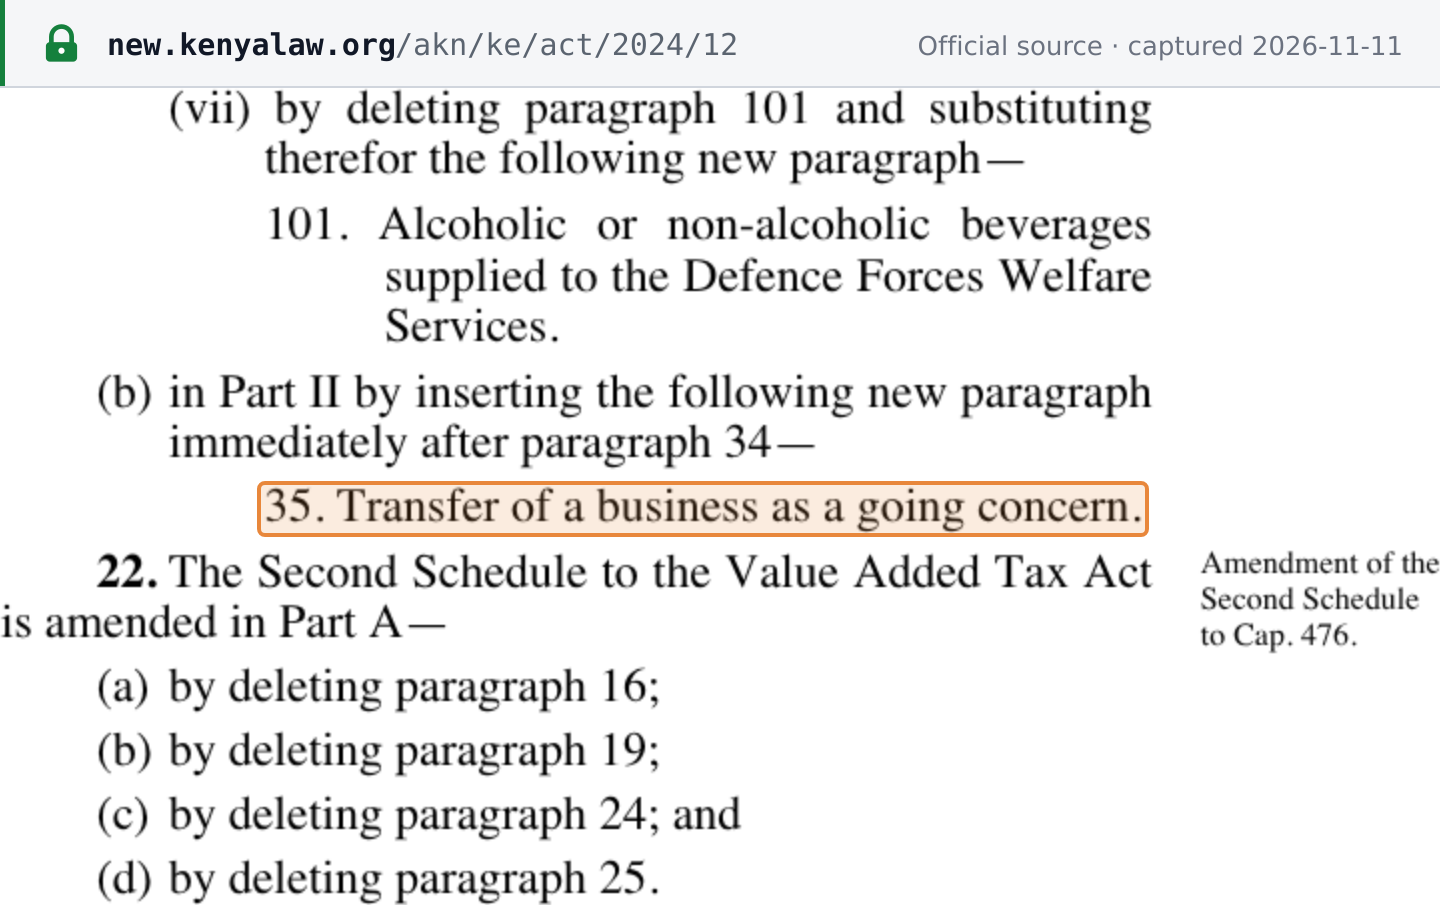 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · The Tax Laws (Amendment) Act, 2024 (No. 12 of 2024), Kenya Gazette Supplement No. 215, 13 December 2024 · kenyalaw.org