Liechtenstein moves menstrual hygiene products to the 2.6% reduced VAT rate from 1 January 2025
- Jurisdiction
- Liechtenstein
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 29 October 2024
- Effective
- 1 January 2025
- Instrument
- LI-ACT-LGBl-2024-Nr-372
- Authority
- Liechtensteinisches Landesgesetzblatt
- Verified
- Fetched from official source · high confidence
Retailers, pharmacies, wholesalers and importers supplying menstrual hygiene products in Liechtenstein.
No action — menstrual hygiene products have been taxed at 2.6% since 1 January 2025.
LGBl. 2024 Nr. 372 (Gesetz vom 5. September 2024 über die Abänderung des Mehrwertsteuergesetzes), issued 29 October 2024 and in force from 1 January 2025 (Part III), inserts a new item 10 into Article 25(2)(a) MWSTG: 'Produkte für die Monatshygiene' (menstrual hygiene products) are taxed at the 2.6% reduced rate instead of the 8.1% standard rate. The same law inserts the deemed-supplier rule for electronic platforms (Article 20a), the travel-agency resale exemption (Article 21(2)(30)), and an emissions-rights reverse-charge provision (Article 45(1)(e)).
What changed in detail
The Gesetz vom 5. September 2024 über die Abänderung des Mehrwertsteuergesetzes was published as LGBl. 2024 Nr. 372, issued on 29 October 2024. Under its Part III it entered into force on 1 January 2025.
It inserts a new item 10, “Produkte für die Monatshygiene” (menstrual hygiene products), into Article 25(2)(a) of the Mehrwertsteuergesetz (MWSTG), the list of goods whose supply is taxed at the 2.6% reduced rate. Before the change these products were not on the list, so they were taxed at the 8.1% standard rate set by LGBl. 2023 Nr. 221.
The law does not define the products further.
The same law made other changes to the MWSTG, each outside this record: the deemed-supplier rule for electronic platforms in new Article 20a (recorded here), an exemption for travel agencies’ resale of travel services (Article 21(2)(30)) and a reverse charge for emissions rights (Article 45(1)(e)).
What it means
The reduced rate is still in force. The consolidated MWSTG on gesetze.li (version of 1 January 2026) shows item 10 in Article 25(2)(a), with a footnote noting it was inserted by LGBl. 2024 Nr. 372, and the rates of 8.1% and 2.6% are unchanged.
Liechtenstein shares a VAT area with Switzerland, which made the same change to its own law on the same date, so products crossing the border are treated alike. Sellers should check that tampons, pads, menstrual cups and similar products are mapped to the 2.6% code in their systems; mixed baskets with other toiletries still split between the two rates.
Proof
10. Produkte für die Monatshygiene;10. Menstrual hygiene products;
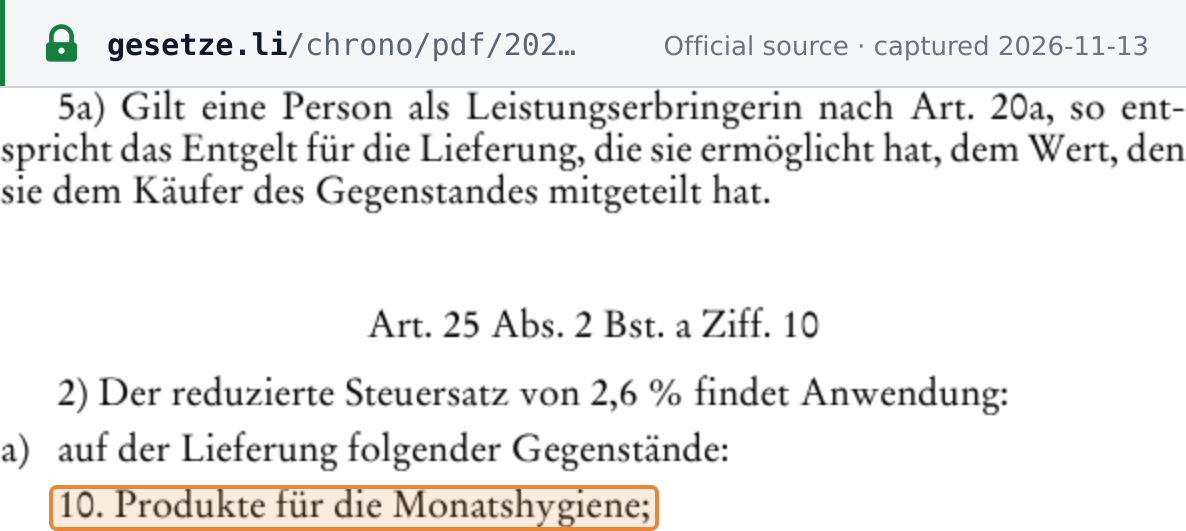 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · LGBl. 2024 Nr. 372, Gesetz vom 5. September 2024 über die Abänderung des Mehrwertsteuergesetzes, ausgegeben am 29. Oktober 2024 · www.gesetze.li