Malta opens its small-enterprise VAT exemption to businesses established elsewhere in the EU
This page records one dated change. For the rules in Malta as they stand today, see the Malta guide →
- Jurisdiction
- Malta
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 17 December 2024
- Effective
- 1 January 2025
- Instrument
- MT-ACT-XXXVIII-2024
- Authority
- Government of Malta, Laws of Malta (legislation.mt)
- Verified
- Fetched from official source · high confidence
Small enterprises established in Malta that supply in other EU Member States, and small enterprises established in other Member States that supply in Malta.
No action — monitoring only.
Act XXXVIII of 2024 (Presidential assent 17 December 2024), transposing EU Directive 2020/285, introduced the cross-border SME VAT exemption scheme in Malta via new Articles 11, 11A and 11B of the Value Added Tax Act, allowing small enterprises established in other EU member states to register in Malta for the small-enterprise exemption and vice versa, effective 1 January 2025.
What changed in detail
Act No. XXXVIII of 2024, the Value Added Tax (Amendment) Act, 2024, received Presidential assent on 17 December 2024 and came into force on 1 January 2025 (s.1(2)). It rebuilds the small-enterprise provisions of the VAT Act (Cap. 406) around three articles:
- Art. 11 (substituted): a taxable person established in Malta who qualifies as a small enterprise under Part One of the Sixth Schedule may register under art. 11 for supplies made within Malta. An art. 11 number carries no “MT” prefix and is not a VAT identification number.
- Art. 11A (new): a Malta-established small enterprise that supplies in another Member State and wants that State’s SME exemption applies to the Commissioner under Part Two of the Sixth Schedule. It receives its art. 10 or 11 number with the suffix “EX”. It must apply to cancel within 15 working days once its Union annual turnover exceeds the Union threshold.
- Art. 11B (new): a person established in another Member State is deemed to have applied once that State notifies Malta under Chapter Xa of Regulation (EU) 904/2010. Registration takes effect only when the Commissioner approves under Part Three of the Sixth Schedule. Malta must answer within 15 working days.
The Act also renames the Sixth Schedule “Small Enterprises” and lets such persons skip article 10 registration for those supplies (art. 10(4) proviso).
What it means
Before 2025, Malta’s small-enterprise exemption was domestic only. Since 1 January 2025 it works in both directions under the EU scheme. Malta-based small firms can use other Member States’ exemptions through an EX number. EU small firms reach Malta through their home tax authority and do not register with the Commissioner directly.
The scheme is in force as of November 2026. The MTCA’s July 2026 guidance on fiscal receipts for art. 11 exempt SMEs (mt-fiscal-receipt-art11-sme-2026) builds on it.
Proof
A taxable person who is not established in Malta but is established in another Member State shall be deemed to have applied to register under this article once the Commissioner is notified by the Member State in which such person is established in accordance with Chapter Xa of Council Regulation (EU) 904/2010 of the person’s intention to avail itself of the exemption for small enterprises in relation to supplies of goods and services made in Malta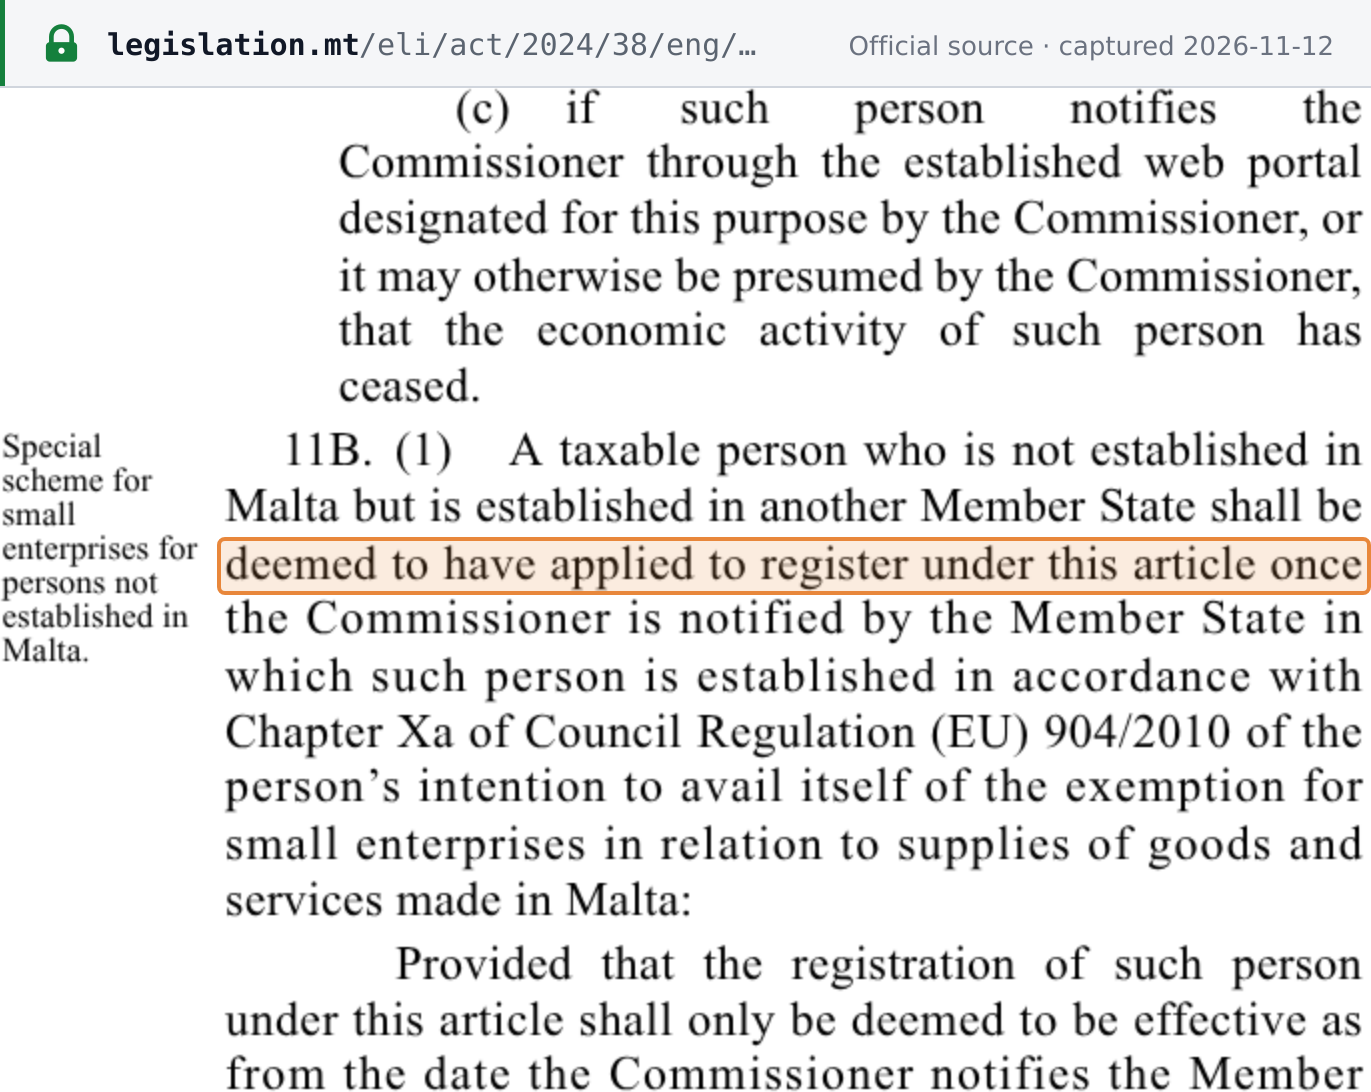 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Act No. XXXVIII of 2024, Value Added Tax (Amendment) Act, 2024 (ELI: legislation.mt/eli/act/2024/38/eng; assent 17 December 2024; Government Gazette of Malta No. 21,362) · legislation.mt