Mauritius requires foreign digital-service suppliers to register for VAT regardless of turnover
This page records one dated change. For the rules in Mauritius as they stand today, see the Mauritius guide →
- Jurisdiction
- Mauritius
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- FYI
- Announced
- 9 August 2025
- Effective
- 1 January 2026
- Instrument
- MU-ACT-Act-No-18-of-2025
- Authority
- National Assembly of Mauritius
- Verified
- Fetched from official source · high confidence
Suppliers with no permanent establishment in Mauritius, or with their place of abode outside it, that supply digital or electronic services listed in Part III of the VAT Act Tenth Schedule to persons in Mauritius.
No action — monitoring only.
Finance Act 2025 (Act No. 18 of 2025) requires foreign suppliers with no permanent establishment in Mauritius to register for VAT if they provide digital or electronic services (as specified in Part III of the Tenth Schedule to the VAT Act) to any person in Mauritius, effective 1 January 2026.
What changed in detail
Section 61 of the Finance Act 2025 (Act No. 18 of 2025), gazetted on 9 August 2025, rewrites how the Mauritius VAT Act treats non-resident digital suppliers.
- s.61(a) defines a “foreign supplier” as a person with no permanent establishment in Mauritius or with its place of abode outside Mauritius, who supplies digital or electronic services to a person in Mauritius. A “digital or electronic service” is a Part III, Tenth Schedule service supplied over the internet or that depends on information technology.
- s.61(b) lets a foreign supplier paid in a listed foreign currency file and pay in that currency.
- s.61(c) replaces sections 14A and 14B. VAT is charged on these services. A foreign supplier above the Sixth Schedule threshold must appoint a tax representative with a permanent establishment in Mauritius. Any two non-contradictory indicators, such as billing address, bank location, IP address or phone country code, place the customer in Mauritius.
- s.61(d) adds section 15(2)(a)(iii), which makes registration compulsory for these supplies “irrespective of his turnover of taxable supplies”.
Section 66(10) brings all of these into operation on 1 January 2026.
What it means
From 1 January 2026, any foreign digital-service supplier with Mauritian customers had to register, whatever its sales. Those above the threshold also had to appoint a local tax representative.
That position has since been eased. The Finance Act 2026 (Act No. 14 of 2026) repealed the tax-representative requirement on publication, 13 August 2026 (mu-digital-tax-representative-repealed-2026). From 1 October 2026 it replaced “irrespective of his turnover” with the Sixth Schedule turnover threshold, and it exempts suppliers who sell only to VAT-registered persons (mu-digital-services-easing-enacted-2026). This record describes the rule as it stood from January to September 2026.
Proof
the supply of digital or electronic services specified in Part III of the Tenth Schedule, irrespective of his turnover of taxable supplies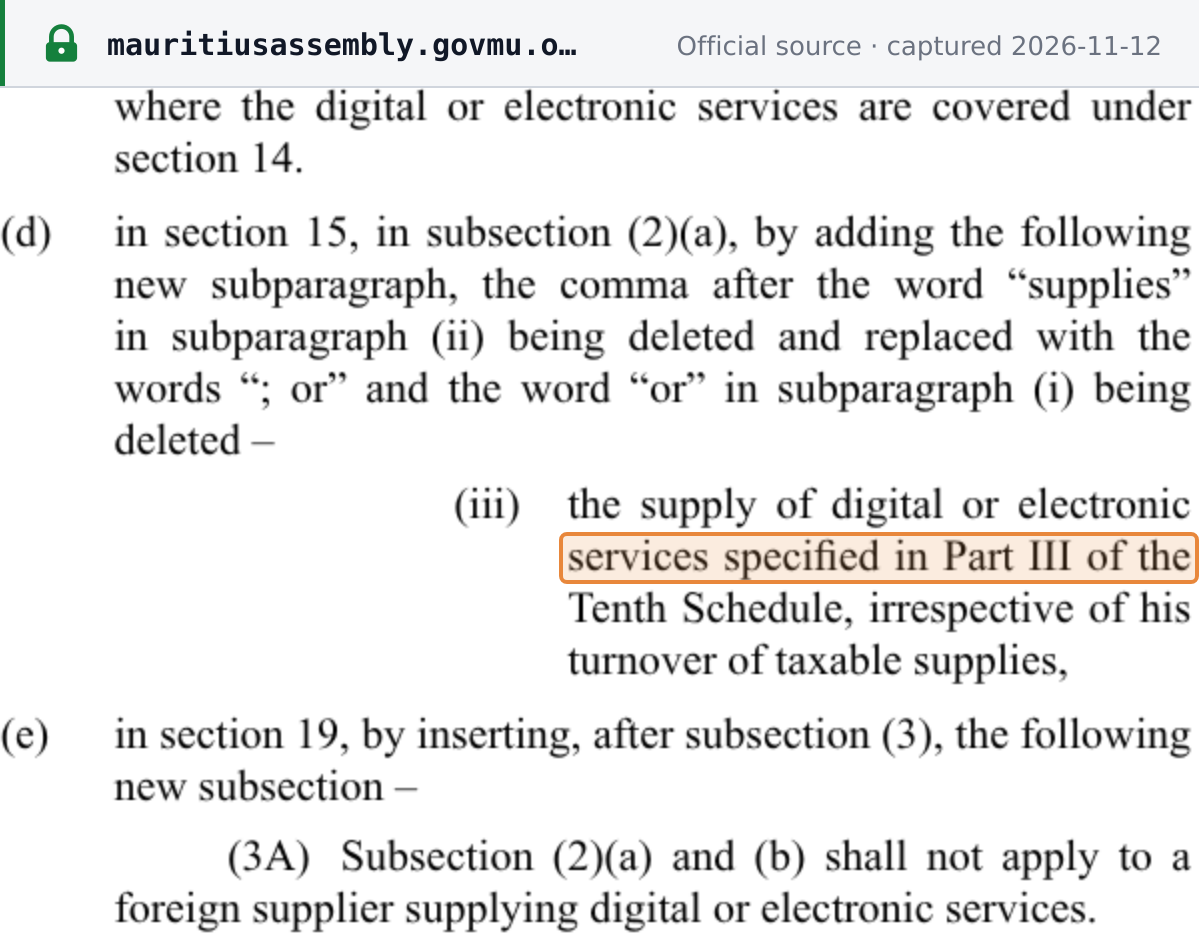 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · The Finance Act 2025 (Act No. 18 of 2025), s.61, Legal Supplement to Government Gazette of Mauritius No. 66 of 9 August 2025 · mauritiusassembly.govmu.org