Nigeria makes the fiscalisation system mandatory for every VAT-taxable supplier
This page records one dated change. For the rules in Nigeria as they stand today, see the Nigeria guide →
- Jurisdiction
- Nigeria
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 26 June 2025
- Effective
- 1 January 2026
- Instrument
- NG-ACT-7-2025
- Authority
- National Assembly of the Federal Republic of Nigeria
- Verified
- Fetched from official source · high confidence
Every taxable person making taxable supplies in Nigeria, phased in by the Nigeria Revenue Service's rollout.
No action — monitoring only.
Nigeria Tax Act 2025 (Act No. 7), section 157, mandates that every taxable person making a taxable supply must implement the fiscalisation system deployed by the Nigeria Revenue Service in accordance with the Nigeria Tax Administration Act 2025, effective 1 January 2026.
What changed in detail
Section 157 of the Nigeria Tax Act, 2025 (Act No. 7), headed “Fiscalisation of supplies for VAT”, comes into force on 1 January 2026.
Section 157(1) requires every taxable person making a taxable supply to implement the fiscalisation system deployed by the Service, in accordance with the Nigeria Tax Administration Act.
Section 157(2) defines what that system may consist of: fiscal equipment made up of electronic devices, software solutions, or a communication system over a secured network, or any combination of these, “for electronic invoicing and data transfer as the Service may prescribe or deploy”.
A separate power sits in section 152(4). For the purpose of the invoice rules, the Service may direct any taxable person to use electronic invoices, on at least 30 days’ notice.
The Act does not itself name a system, a technical standard or a timetable. Those are left to the Service.
What it means
Section 157 is the statutory basis for e-invoicing in Nigeria. It makes participation an obligation of the VAT law itself, but leaves the system, the format and the sequencing to the Nigeria Revenue Service. In practice the rollout has run in phases by taxpayer size. The NRS extended the Merchant Buyer Solution to medium taxpayers from 1 July 2026 (ng-merchant-buyer-solution-rollout-2026).
As of November 2026 section 157 is in force as enacted. When a business must connect depends on the NRS phase notices, not on this section alone.
Proof
A taxable person making a taxable supply shall implement the fiscalisation system deployed by the Service in accordance with Nigeria Tax Administration Act.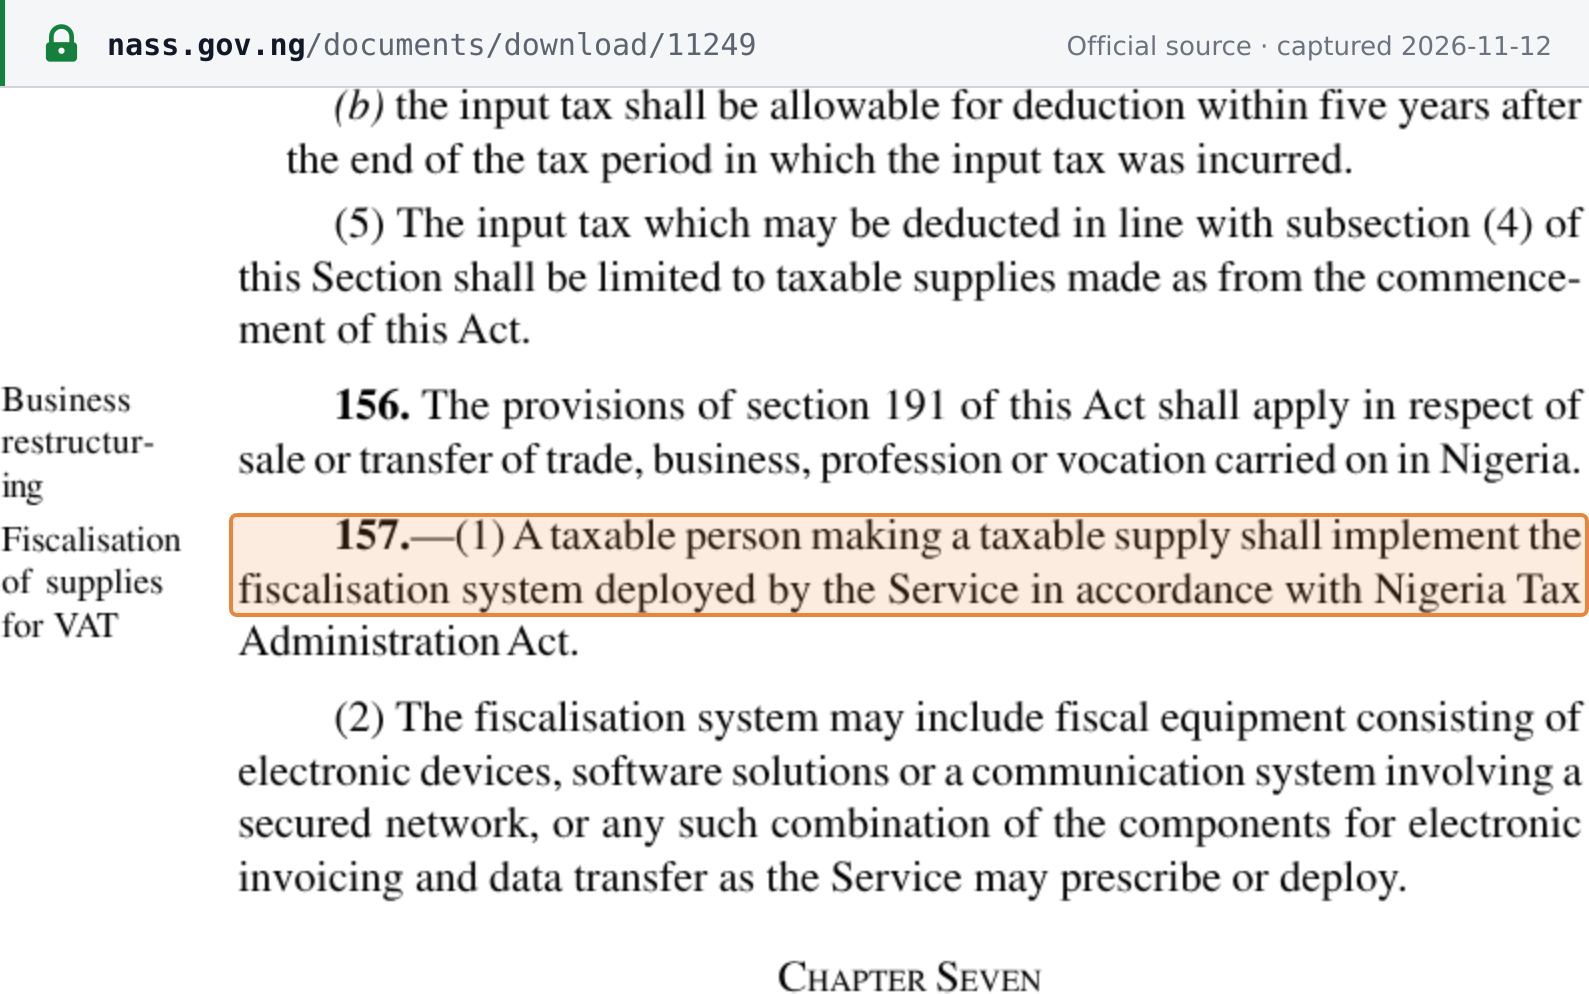 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Nigeria Tax Act, 2025 (Act No. 7), s.157 — Federal Republic of Nigeria Official Gazette No. 117, Vol. 112, Lagos, 26 June 2025 · nass.gov.ng