Oman lets its armed and security forces reclaim VAT on local purchases of weapons, ammunition and military vehicles
This page records one dated change. For the rules in Oman as they stand today, see the Oman guide →
- Jurisdiction
- Oman
- Tax
- VAT
- Change type
- Update
- Status
- In force
- Impact
- FYI
- Announced
- 4 May 2025
- Effective
- 5 May 2025
- Instrument
- OM-DECISION-81-2025
- Authority
- Ministry of Justice and Legal Affairs (Sultanate of Oman)
- Verified
- Fetched from official source · high confidence
Oman’s armed forces and security forces, in all their sectors, and the local suppliers selling them ammunition, weapons, military transport equipment and vehicles, and parts.
No action — monitoring only.
Oman Tax Authority Decision No. 81/2025, signed on 30 April 2025 and published in Official Gazette No. 1594 on 4 May 2025, amends the Executive Regulation of the VAT Law (Decision 53/2021) by adding a fourth case to the schedule of additional VAT refund cases. VAT paid by the armed forces and security forces, in all their sectors, on local purchases of ammunition, weapons, military transport equipment and vehicles, and their parts and accessories is refundable. Claims are filed with the Tax Authority for each quarterly tax period, must total at least OMR 15, and must be made on the prescribed form with the tax invoice, or a simplified tax invoice with proof that the tax was debited from the claimant's bank account. The Authority must decide within 30 days of receiving complete documents (otherwise the claim is deemed rejected) and refund approved amounts within 15 days of notifying its decision. The decision took effect on 5 May 2025, the day after publication.
What changed in detail
Oman Tax Authority Decision No. 81/2025 was signed on 30 April 2025 (2/11/1446H) and published in Official Gazette No. 1594 on 4 May 2025. It amends the Executive Regulation of the VAT Law (issued by Decision No. 53/2021) by adding a fourth case to the schedule of additional cases in which VAT is refunded.
The new case covers VAT paid by the armed forces and security forces, in all their sectors, on local purchases of ammunition, weapons, military transport equipment and vehicles, and their parts and accessories.
The conditions attached to the refund are:
- a claim is filed with the Tax Authority for each tax period (every three months), and the total claimed must be at least OMR 15;
- the claim is made on the prescribed form with the tax invoice, or a simplified tax invoice with proof that the tax was debited from the claimant’s bank account;
- the Authority must decide within 30 days of receiving all required documents, otherwise the claim is deemed rejected;
- approved amounts, in whole or in part, are refunded within 15 days of notifying the decision.
Article 3 brings the decision into effect on the day after publication, 5 May 2025.
What it means
The refund case has applied since 5 May 2025 and is still in force in November 2026; the weekly feed holds no later amendment to it.
It is a refund, not an exemption or zero rate: the decision does not change how local suppliers tax these sales, and the forces recover the VAT they paid afterwards. Suppliers should keep issuing full tax invoices, since the claim depends on them. The 30-day deemed-rejection rule puts the onus on the claimant to file complete documents the first time.
Proof
الضريبة المدفوعة من القوات المسلحة وقوى الأمن بجميع قطاعاتها على مشترياتها المحلية من الذخائر والأسلحة وتجهيزات ووسائط النقل العسكري، وقطعها وملحقاتهاTax paid by the armed forces and security forces in all their sectors on their local purchases of ammunition, weapons, and military transport equipment and vehicles, and their parts and accessories
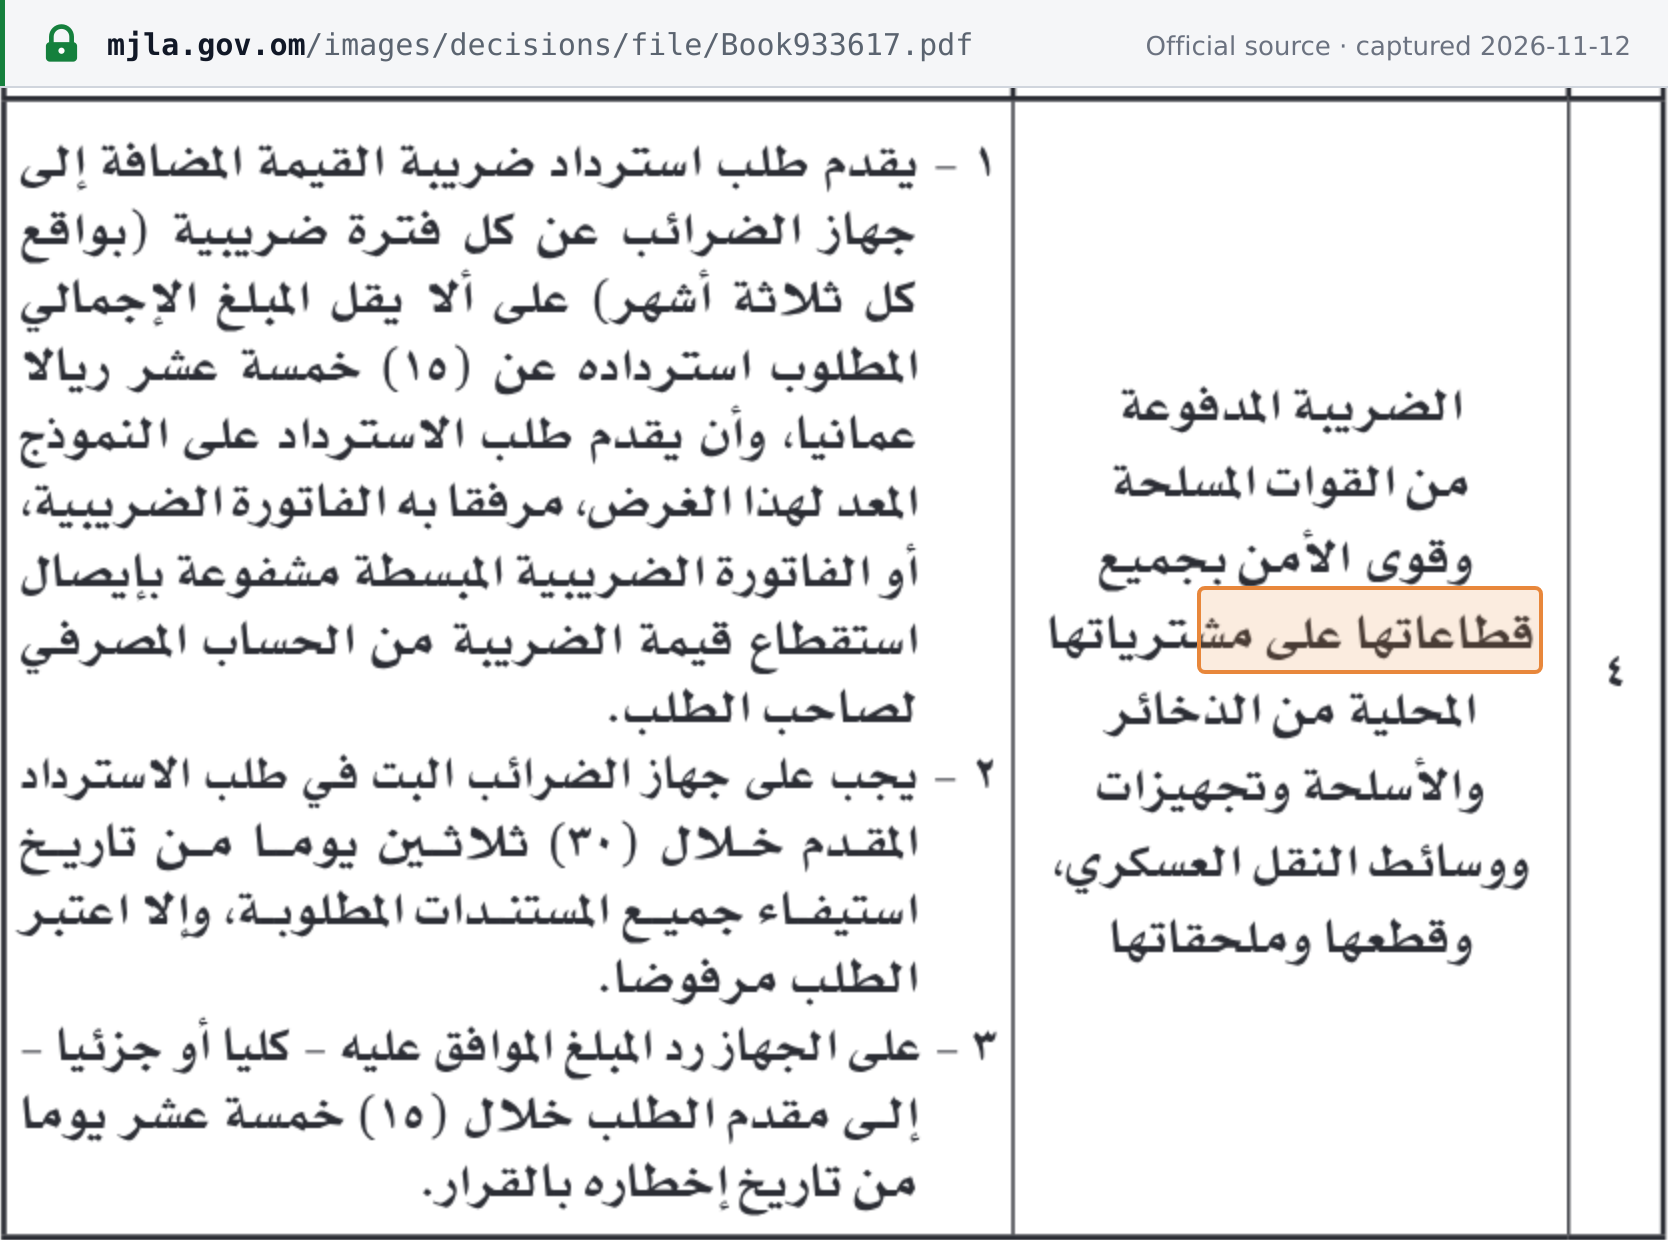 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Tax Authority Decision No. 81/2025 amending the Executive Regulation of the VAT Law, Official Gazette No. 1594, issued 2/11/1446H (30 April 2025) · www.mjla.gov.om
جهاز الضرائب قرار رقم ٢٠٢٥/٨١ بتعديل بعض أحكام اللائحة التنفيذية لقانون ضريبة القيمة المضافةTax Authority Decision No. 81/2025 amending certain provisions of the Executive Regulation of the Value Added Tax Law
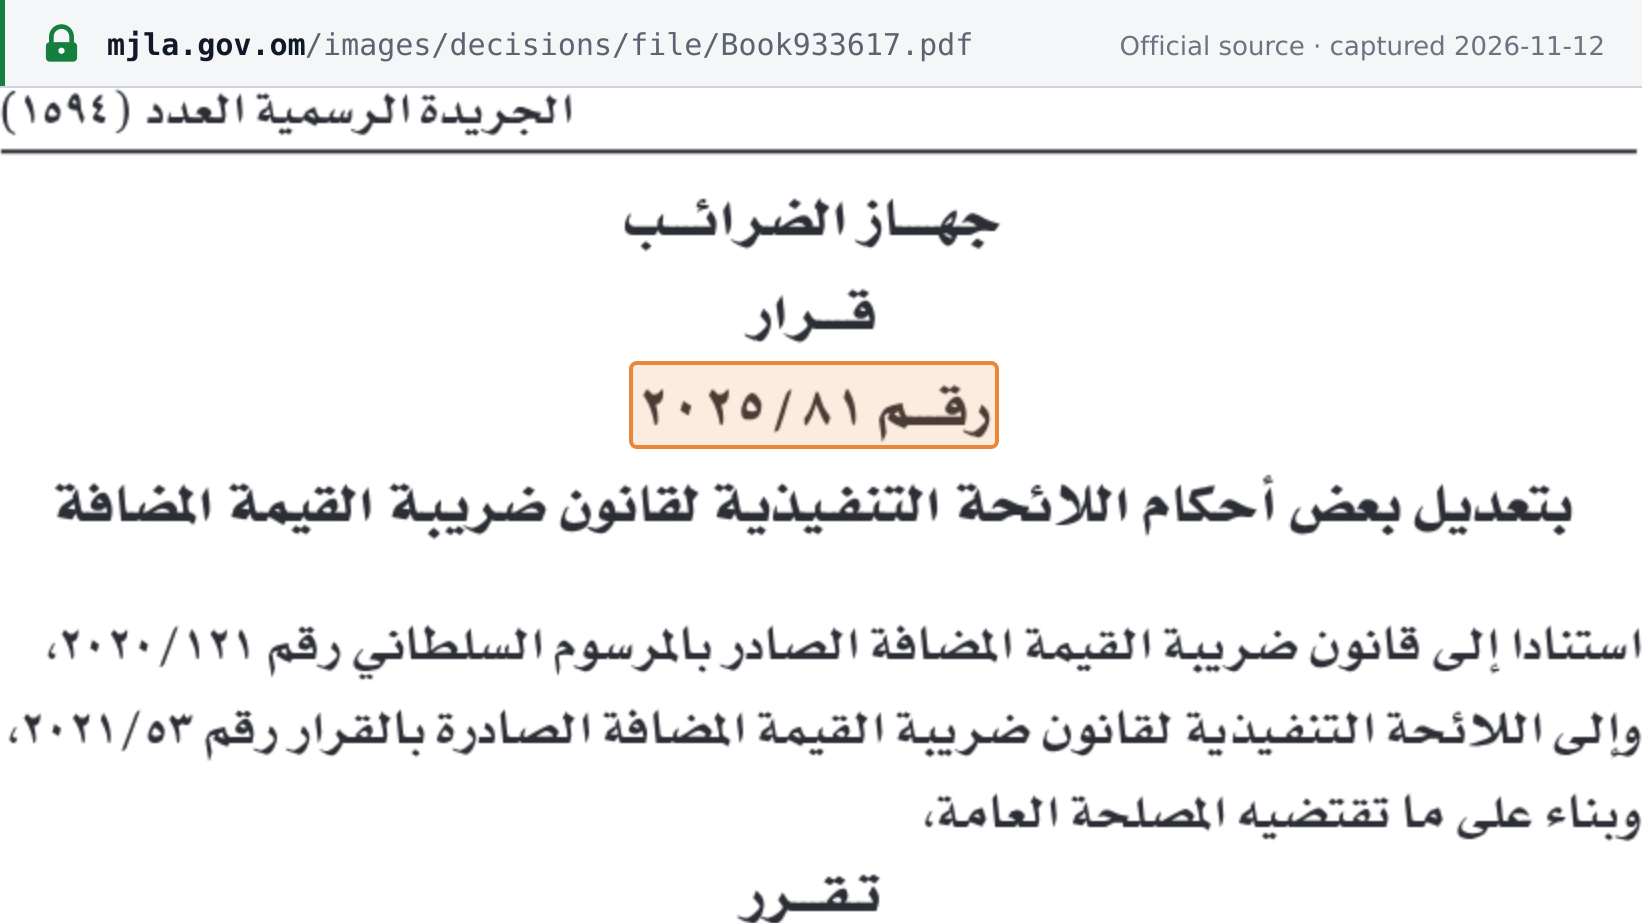 Source snapshot of the official page. Open full size ↗