Pakistan replaces the FATA/PATA sales-tax exemption with a 10% rate rising to 16% by 2028-29
This page records one dated change. For the rules in Pakistan as they stand today, see the Pakistan guide →
- Jurisdiction
- Pakistan
- Tax
- Sales Tax
- Change type
- Rate change
- Status
- In force
- Impact
- Plan ahead
- Announced
- 27 June 2025
- Effective
- 1 July 2025
- Authority
- Federal Board of Revenue, Pakistan
- Verified
- Fetched from official source · high confidence
Industrial units in the erstwhile FATA/PATA tribal areas, importers of plant, machinery and inputs for those areas, and suppliers within them; electricity consumers in the tribal areas.
FATA/PATA industrial units must charge 10% (now in force) and must prepare for 12% from 1 July 2026. Update invoicing systems and contracts accordingly.
Finance Act, 2025 (Act No. XIX of 2025), assented by the President on 27 June 2025 and in force from 1 July 2025, replaces the sales-tax exemption for the erstwhile FATA/PATA tribal areas (extended year by year since 2018) with a phased reduced rate under new Eighth Schedule S.No. 89. It covers imports of plant, machinery and equipment for installation in the tribal areas, imports of industrial inputs by industries located there, and supplies within them. Rates are 10% for 2025-26, 12% for 2026-27, 14% for 2027-28 and 16% for 2028-29, and FBR Circular 02 of 2025-26 states the standard 18% from July 2029. The Sixth Schedule exemption for electricity supplied to tribal-area residential, commercial and pre-31 May 2018 industrial consumers was extended to 30 June 2026.
What changed in detail
The Finance Act, 2025 (Act No. XIX of 2025) received the President’s assent on 27 June 2025 and was gazetted on 29 June 2025. Its sales-tax provisions apply from 1 July 2025.
The exemption on imports and supplies by industrial units in the erstwhile FATA/PATA tribal areas had run since 2018, most recently extended to 30 June 2025. The Act replaces it with a phased reduced rate under new Eighth Schedule S. No. 89. The entry covers imports of plant, machinery and equipment for installation in the tribal areas, imports of industrial inputs by industries located there, and supplies within them.
| Tax period | Rate |
|---|---|
| July 2025 – June 2026 | 10% |
| July 2026 – June 2027 | 12% |
| July 2027 – June 2028 | 14% |
| July 2028 – June 2029 | 16% |
| July 2029 onwards (per FBR Circular 02 of 2025-26) | 18% |
FBR Circular No. 02 of 2025-26 (2 August 2025, para 29) gives the reason: inputs imported for FATA/PATA were reaching the settled areas and undercutting industry there.
The Sixth Schedule exemption (S. No. 152) also continued, but only to 30 June 2026. It covers electricity supplied to residential and commercial consumers in the tribal areas, and to industries there that started production before 31 May 2018.
What it means
The phase-in is running. Since 1 July 2026, tribal-area industrial units have charged 12%, and the step to 14% is due on 1 July 2027. The Finance Act, 2026 (gazetted 26 June 2026) did not amend S. No. 89. Its Sixth and Eighth Schedule amendments extend other entries, but not this one and not the S. No. 152 electricity exemption. On the Act’s own text, that exemption ran to 30 June 2026.
Units in the tribal areas should price contracts that run past June 2027 at the next step, not the current one. Goods taken outside the tribal areas pay the difference up to the standard rate.
Proof
gradual imposition of sales tax on import and supplies by the industrial units located in erstwhile FATA/PATA has been enacted by adding S. No. 89 in the Eighth Schedule, thereby charging sales tax in phased manner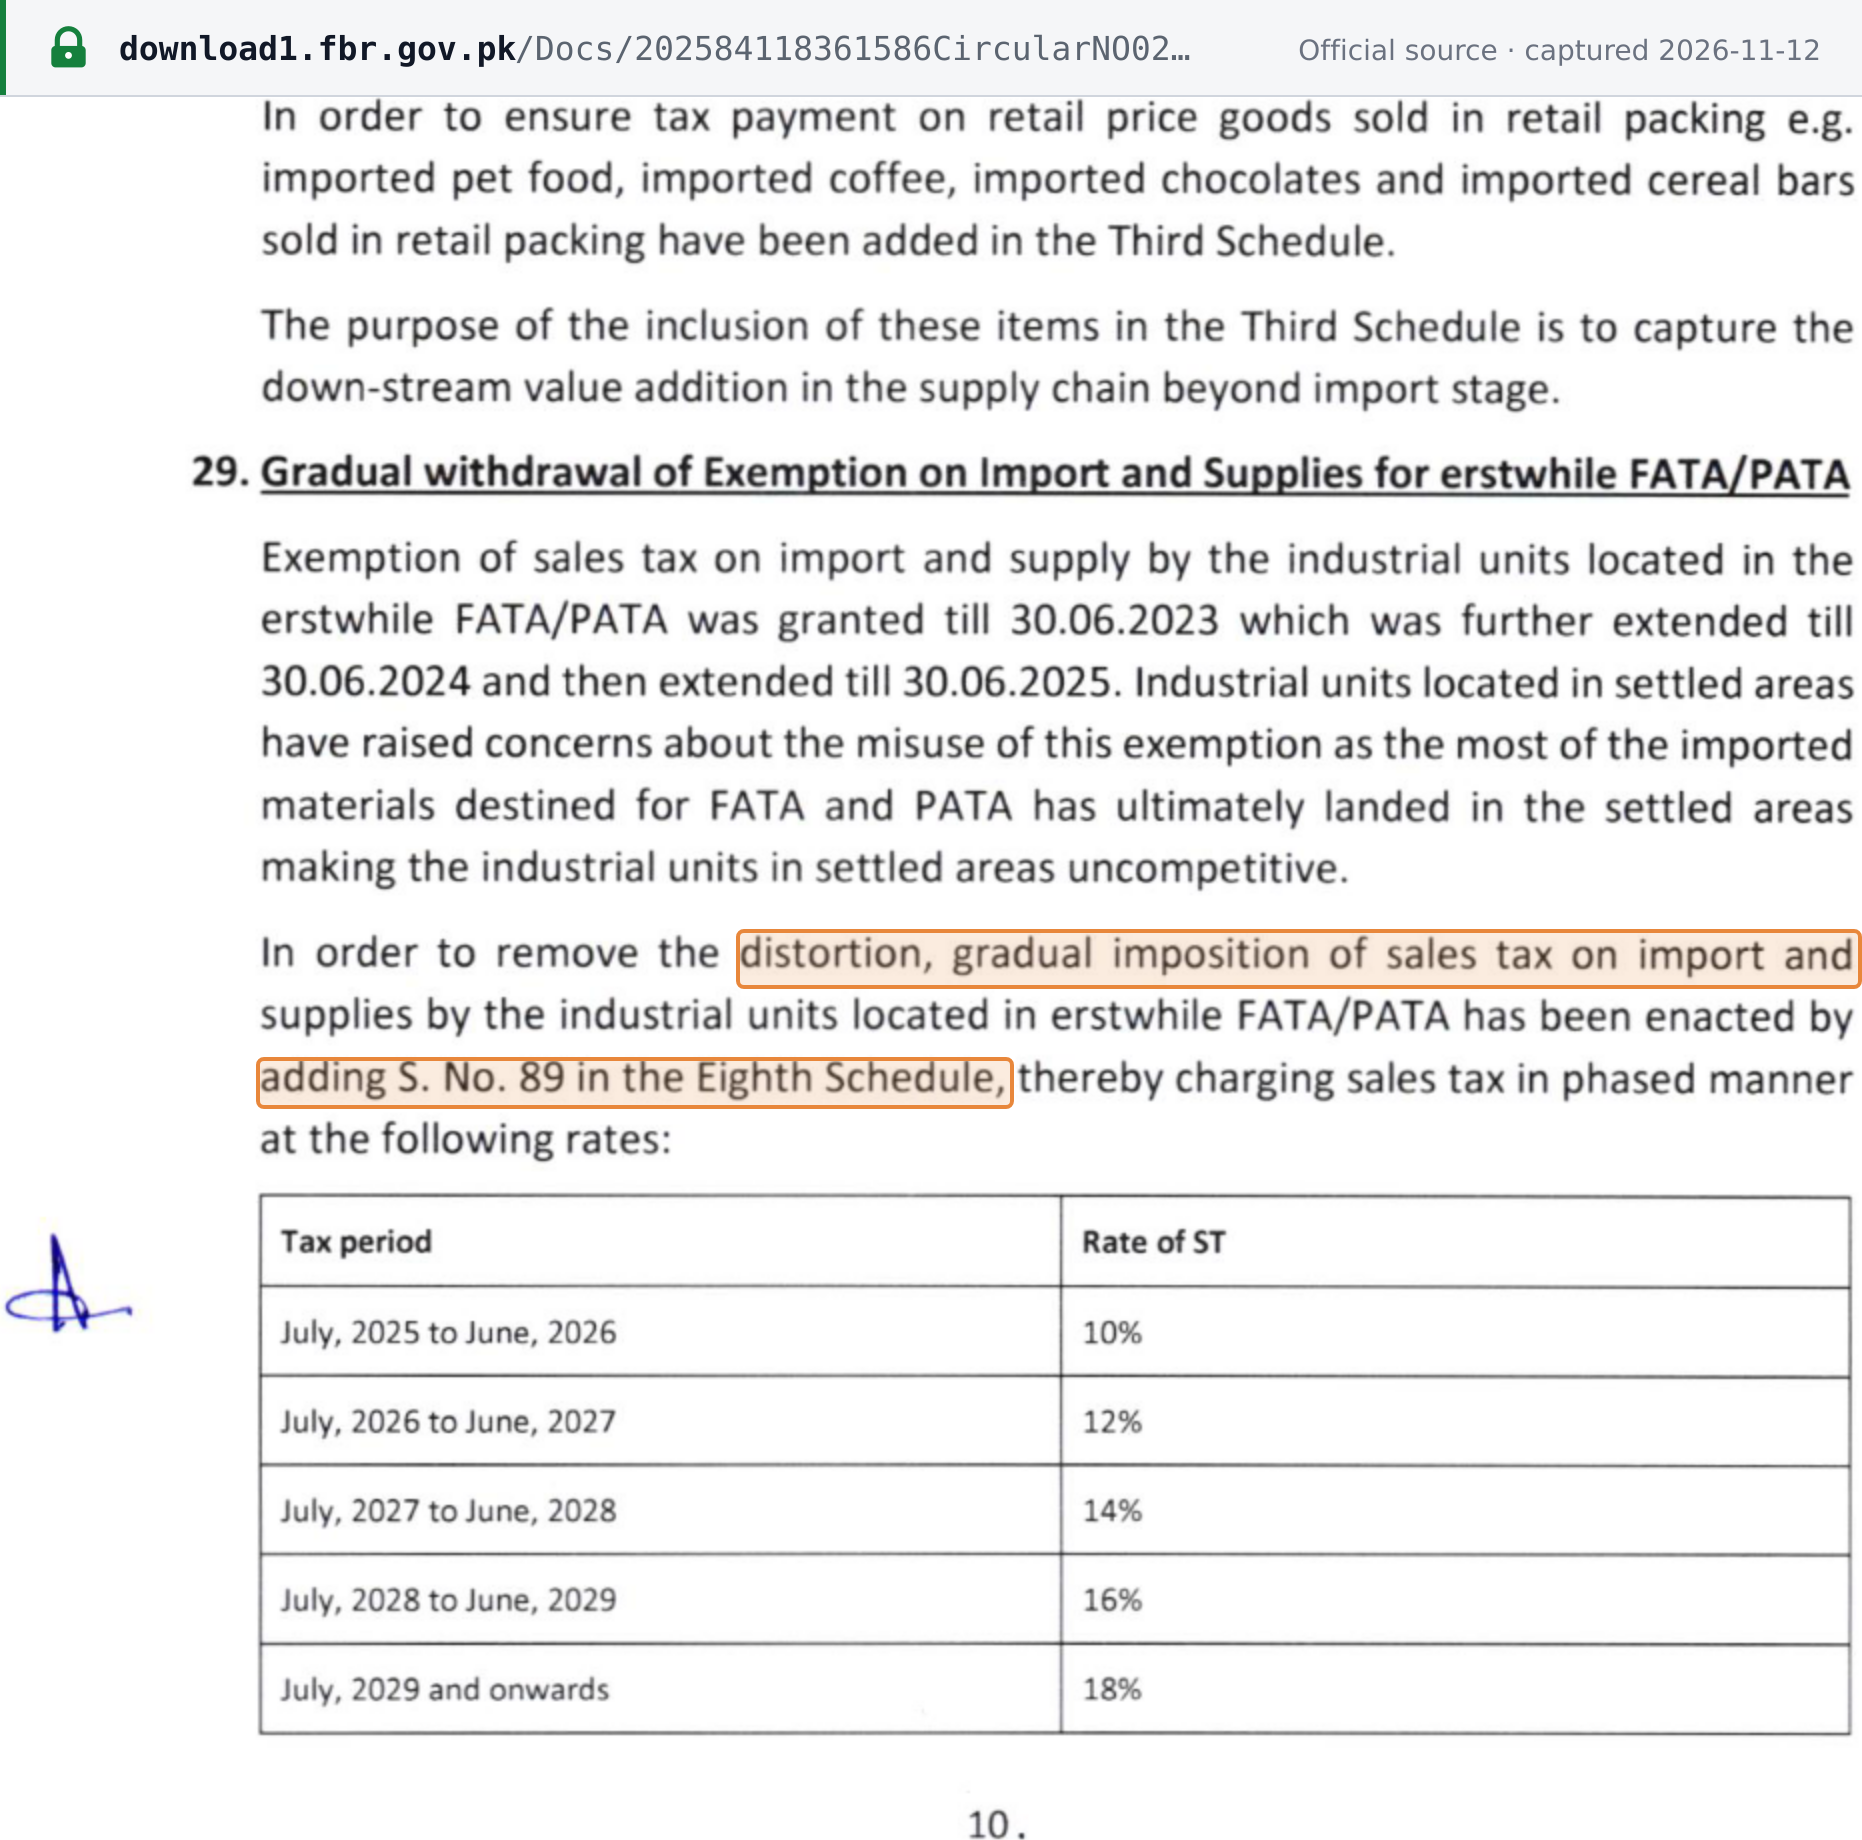 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · FBR Circular No. 02 of 2025-26 (Sales Tax & Federal Excise), 2 August 2025, para 29 · download1.fbr.gov.pk