Paraguay puts medium and large taxpayers in Groups 11 to 18 on mandatory SIFEN e-invoicing, March 2025 to December 2026
- Jurisdiction
- Paraguay
- Tax
- IVA
- Change type
- E-invoicing
- Status
- In force
- Impact
- Action required
- Announced
- 30 December 2024
- Effective
- 3 March 2025
- Instrument
- PY-RESOLUTION-21-2024
- Authority
- Direccion Nacional de Ingresos Tributarios (DNIT), Paraguay
- Verified
- Fetched from official source · high confidence
Medium and large taxpayers listed in Annexes I–VIII of the resolution, suppliers to the State, and legal entities newly registered in the RUC from 1 April 2025.
Medium and large taxpayers assigned to Groups 11–18 must issue all tax documents exclusively electronically from their designated start dates (Groups 11–14 already obligated; Groups 15–18 from March–December 2026). New legal-entity taxpayers may only issue electronic documents from 1 April 2025.
Resolución General DNIT N° 21, issued 30 December 2024 by Director Nacional Óscar Alcides Orué Ortiz, designates medium and large taxpayers in Groups 11 through 18 as mandatory electronic invoice issuers (facturadores electrónicos) under the SIFEN system. Each group must issue all tax documents exclusively electronically from its start date: Group 11 from 3 March 2025, Group 12 from 2 June 2025, Group 13 from 1 September 2025, Group 14 from 1 December 2025, Group 15 from 2 March 2026, Group 16 from 1 June 2026, Group 17 from 1 September 2026, Group 18 from 1 December 2026. State suppliers (Proveedores del Estado) must issue exclusively electronic documents from 2 January 2026 (Art. 7). New legal-entity RUC registrants may only use E-Kuatia or E-Kuatia'i from 1 April 2025 (Art. 9). This resolution was subsequently modified by Resolución General DNIT N° 52/2026 (already shipped as py-dnit-rg-52-electronic-invoicers-2026).
What changed in detail
Resolución General DNIT N° 21, signed in Asunción on 30 December 2024 by the Director Nacional de Ingresos Tributarios, Óscar Alcides Orué Ortiz, designates the medium and large taxpayers listed in its annexes as electronic invoicers (facturadores electrónicos) under SIFEN.
Article 1 sets the calendar. From its group’s start date, each taxpayer must issue all tax documents only in electronic form, except the virtual withholding receipt:
| Group | Start date |
|---|---|
| 11 | 3 March 2025 |
| 12 | 2 June 2025 |
| 13 | 1 September 2025 |
| 14 | 1 December 2025 |
| 15 | 2 March 2026 |
| 16 | 1 June 2026 |
| 17 | 1 September 2026 |
| 18 | 1 December 2026 |
Other provisions:
- Art. 2 (as first issued; replaced by RG 52/2026): a taxpayer could, once, ask 30 working days before its start date to move to the next group, with reasons and an implementation schedule.
- Art. 3: authorisation and timbrado of pre-printed and self-printed documents for Groups 11–18 lapse the day after the start date.
- Art. 5–6: earlier voluntary adopters follow their group’s date (small taxpayers get 12 months); new voluntary adopters must go fully electronic within six months.
- Art. 7: suppliers to the State issue only electronic documents from 2 January 2026.
- Art. 8: a voluntary phase for small legal entities on Ekuatia’i from 2 January 2025.
- Art. 9: legal entities newly registered in the RUC from 1 April 2025 may only issue electronically, through E-Kuatia or E-Kuatia’i.
What it means
The resolution is in force, but it was later modified. Resolución General DNIT N° 52/2026 (5 May 2026) designates further cohorts, Groups 19 to 24, starting from 1 June 2026 through 1 September 2027, and rewrote Article 2 of this resolution: the request to move to the next group was replaced by a one-time extension of up to three months after the start date, available only to taxpayers already using e-kuatia.
As of November 2026, Groups 11 to 17, State suppliers and new legal entities are all electronic-only. Group 18, the last cohort under this resolution, starts on 1 December 2026. Its members’ paper timbrado lapses the next day, so the numbering report and cancellation of pre-printed stock must be done before that date. Later groups follow RG 52/2026.
Proof
El contribuyente, según el grupo al que pertenezca, deberá emitir todos sus documentos tributarios exclusivamente de forma electrónica, con excepción del Comprobante de Retención virtual, a partir de las fechas indicadas en el siguiente calendario:The taxpayer, according to their group, must issue all tax documents exclusively in electronic form, except for the virtual Withholding Receipt, from the dates indicated in the following schedule:
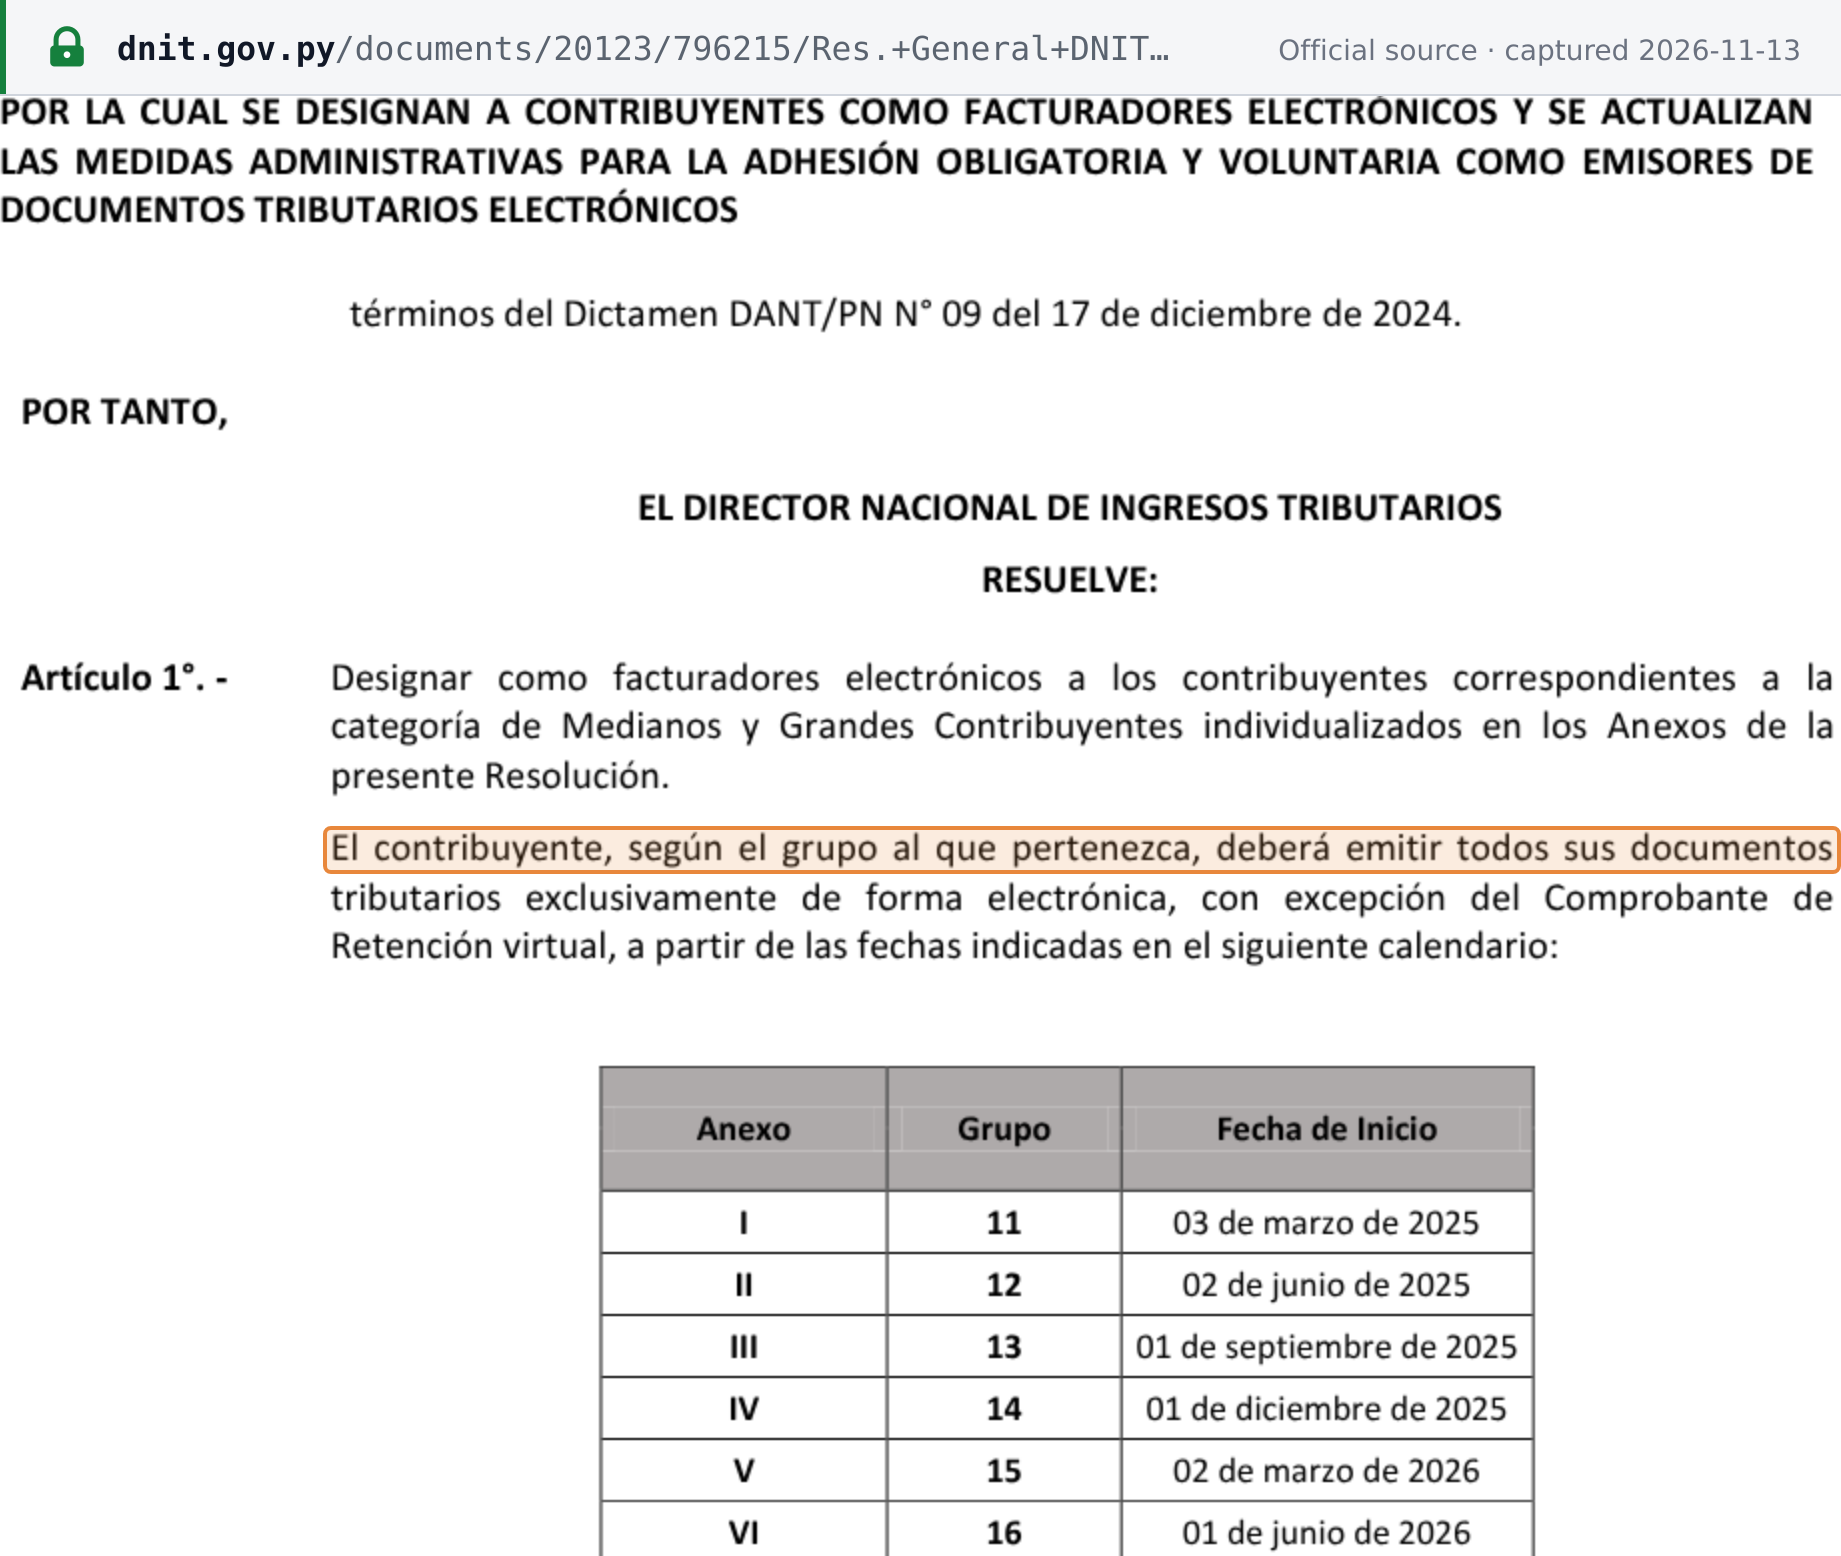 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Resolución General DNIT N° 21, Asunción, 30 de diciembre de 2024 · www.dnit.gov.py