Poland cuts VAT on cosmetic, manicure and pedicure services to 8% from 1 April 2024
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 15 March 2024
- Effective
- 1 April 2024
- Instrument
- PL-MINISTERIAL-REGULATION-DU-2024-387
- Authority
- Dziennik Ustaw Rzeczypospolitej Polskiej
- Verified
- Fetched from official source · high confidence
Providers of cosmetic, manicure and pedicure services classified under PKWiU 96.02.13.0, ex 96.02.14.0 (at the client's home) or 96.02.19.0, mainly beauty salons and mobile beauticians.
No action — in force since 1 April 2024.
Rozporządzenie Ministra Finansów z dnia 14 marca 2024 r. (Dz.U. 2024 poz. 387) amended the reduced-rates regulation of 9 December 2023 (Dz.U. 2023 poz. 2670) with effect from 1 April 2024: § 8 now covers services as well as goods, and the replaced annex adds cosmetic services — PKWiU 96.02.13.0 (cosmetic, manicure and pedicure services), ex 96.02.14.0 (the same services provided at home) and 96.02.19.0 (other cosmetic services) — to the 8% list, in place of the 23% standard rate.
What changed in detail
The Minister of Finance regulation of 14 March 2024 (Dz.U. 2024 poz. 387), published on 15 March 2024, amends the reduced-rates regulation of 9 December 2023 (Dz.U. 2023 poz. 2670) with effect from 1 April 2024.
§ 1 pkt 1 extends § 8 of the 2023 regulation, which applies the 8% rate to the items in its annex, from goods to goods and services. § 1 pkt 2 replaces the annex. The new annex keeps the existing goods for blind and visually impaired people (items 1–5) and adds a services part, classified by PKWiU:
- item 6, PKWiU 96.02.13.0: cosmetic, manicure and pedicure services;
- item 7, ex 96.02.14.0: cosmetic, manicure and pedicure services provided at home;
- item 8, PKWiU 96.02.19.0: other cosmetic services.
Before 1 April 2024 these services took the 23% standard rate. Hairdressing services were already at 8% under Annex 3 to the VAT Act.
What it means
The 8% rate on these services is still in force. The 2023 regulation has been amended many times since, for donation reliefs and the 2026 fuel rates, but none of those changes touched the services part of the annex.
The rate depends on the PKWiU classification of the service, not on what the business calls itself. A salon’s cosmetic, manicure and pedicure work falls within items 6–8. A service classified under another code stays at 23% unless another list covers it. The home-service item is an “ex” position, so only the cosmetic, manicure and pedicure part of PKWiU 96.02.14.0 benefits.
Proof
6 96.02.13.0 Usługi kosmetyczne, manicure i pedicure 7 ex 96.02.14.0 Usługi kosmetyczne, manicure i pedicure, świadczone w domu 8 96.02.19.0 Pozostałe usługi kosmetyczne6 96.02.13.0 Cosmetic, manicure and pedicure services 7 ex 96.02.14.0 Cosmetic, manicure and pedicure services provided at home 8 96.02.19.0 Other cosmetic services
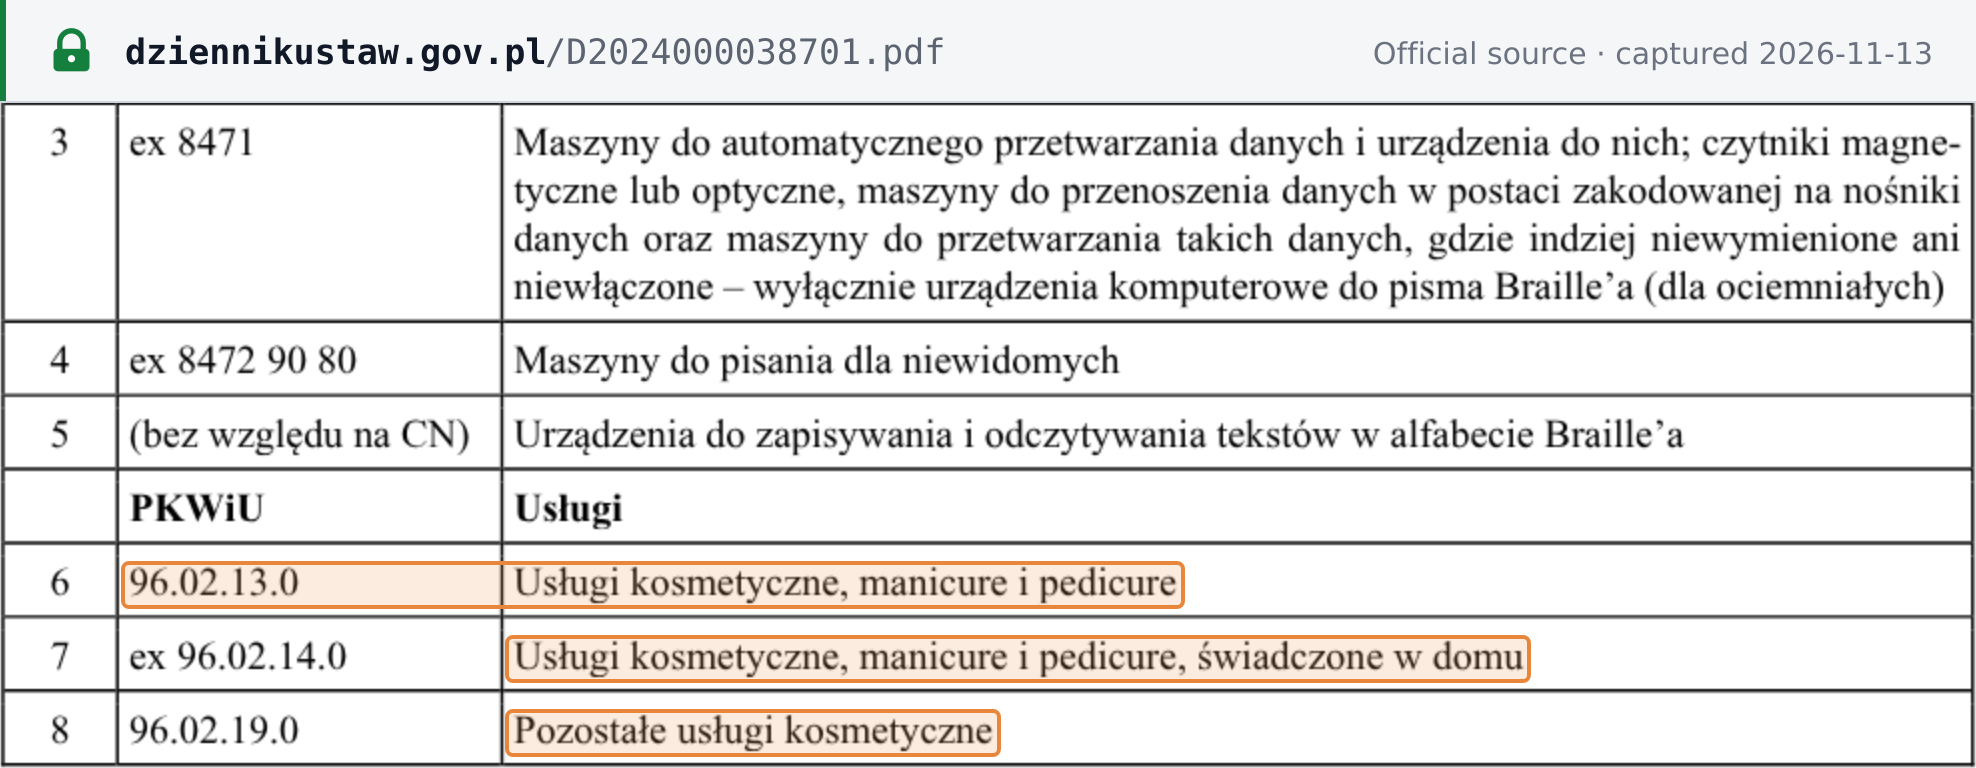 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Dz.U. 2024 poz. 387 · Rozporządzenie Ministra Finansów z dnia 14 marca 2024 r. · dziennikustaw.gov.pl