Poland ends the temporary 0% VAT rate on basic food on 31 March 2024, returning it to 5%
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 9 December 2023
- Effective
- 1 April 2024
- Authority
- Dziennik Ustaw Rzeczypospolitej Polskiej
- Verified
- Fetched from official source · high confidence
Polish sellers of the basic foods listed in items 1–18 of Annex 10 to the VAT Act (other than catering services, PKWiU 56), mainly retailers and food producers.
No action — monitoring only; in force since 1 April 2024.
The Minister of Finance regulation of 9 December 2023 on reduced VAT rates (Dz.U. 2023 poz. 2670, in force 1 January 2024) kept the temporary 0% VAT rate on basic food products (items 1–18 of Annex 10 to the VAT Act) only until 31 March 2024. The measure was not extended, so those foods returned to the 5% reduced rate from 1 April 2024.
What changed in detail
The Minister of Finance regulation of 9 December 2023 on reduced VAT rates (Dz.U. 2023 poz. 2670), in force from 1 January 2024, carried the temporary 0% rate on basic food into 2024 for one more quarter only.
Under § 10(1), the 0% rate applies until 31 March 2024 to the foodstuffs listed in items 1–18 of Annex 10 to the VAT Act, other than goods classified as catering services (PKWiU 56). Under § 10(2), the 0% rate does not apply where those goods are imported under the import scheme referred to in art. 138i(1) of the Act.
The regulation was not extended past that date. From 1 April 2024, the same foods are taxed again at the 5% reduced rate that the VAT Act provides for them through Annex 10.
What it means
This change is spent. Since 1 April 2024, basic food in Poland has carried the 5% rate, and nothing in this regulation applies to supplies made today.
It still matters for corrections and audits of the first quarter of 2024: Annex 10 food supplied on or before 31 March 2024 (tax point arising by that date) correctly took 0%, and supplies from 1 April 2024 took 5%, whatever the invoice date. For mixed baskets and catering, the PKWiU 56 carve-out meant restaurant meals never benefited from the 0% rate, which is a common point of confusion when reviewing that period.
Proof
Do dnia 31 marca 2024 r. obniżoną do wysokości 0% stawkę podatku stosuje się również do towarów spożywczych wymienionych w poz. 1–18 załącznika nr 10 do ustawyUntil 31 March 2024, the tax rate reduced to 0% also applies to the foodstuffs listed in items 1–18 of Annex 10 to the Act
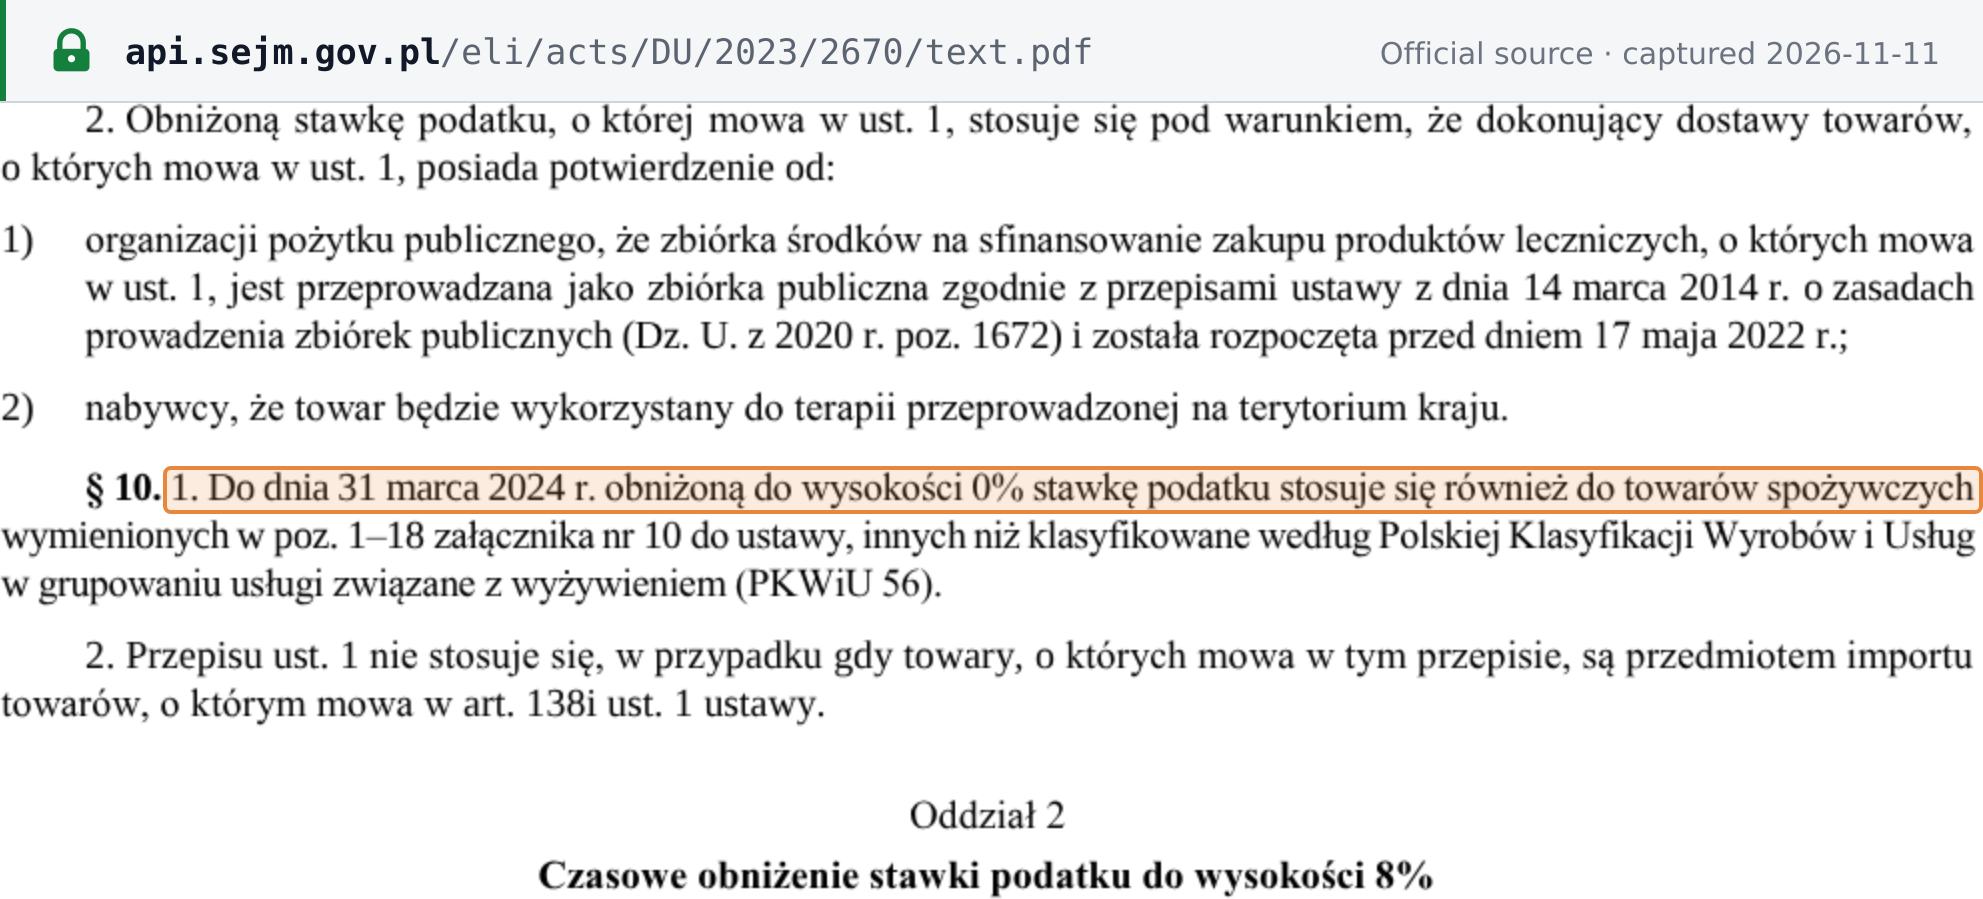 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Dz.U. 2023 poz. 2670 · Rozporządzenie Ministra Finansów z dnia 9 grudnia 2023 r. · api.sejm.gov.pl