Poland fixes the KSeF start at 1 February 2026 for large taxpayers and 1 April 2026 for everyone else
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 1 September 2025
- Effective
- 1 February 2026
- Instrument
- PL-USTAWA-poz-1203-2025
- Authority
- Dziennik Ustaw Rzeczypospolitej Polskiej
- Verified
- Fetched from official source · high confidence
All Polish VAT taxpayers obliged to issue structured invoices; the 1 April 2026 start applies to those whose 2024 sales including VAT did not exceed PLN 200 million.
No action — monitoring only; KSeF is now live (1 February 2026 for large taxpayers, 1 April 2026 for all others).
Ustawa z dnia 5 sierpnia 2025 r. (Dz.U. 2025 poz. 1203, published 1 September 2025) finalised the KSeF mandatory e-invoicing rollout and amended the June 2023 KSeF Act. Structured invoicing applies from 1 February 2026. Taxpayers whose 2024 sales including VAT did not exceed PLN 200 million may keep issuing paper or electronic invoices until 31 March 2026 (Art. 145l), so their obligation starts on 1 April 2026. From 1 April to 31 December 2026, taxpayers whose monthly invoiced sales do not exceed PLN 10,000 may still issue invoices outside KSeF (Art. 145m). Invoices from cash registers may stay outside KSeF until 31 December 2026 (Art. 145n). Most of the Act entered into force on 2 September 2025. Art. 1 items 1–4 entered into force on 1 February 2026.
What changed in detail
The Act of 5 August 2025 (Dz.U. 2025 poz. 1203), published on 1 September 2025, amends the VAT Act and the June 2023 Act that introduced the Krajowy System e-Faktur (KSeF). Most of it entered into force on 2 September 2025; Art. 1 items 1–4 entered into force on 1 February 2026.
It sets the KSeF rollout as follows:
- 1 February 2026: the obligation to issue structured invoices starts.
- Art. 145l: from 1 February to 31 March 2026, taxpayers whose 2024 sales including VAT did not exceed PLN 200,000,000 may still issue electronic or paper invoices, so in practice their obligation starts on 1 April 2026.
- Art. 145m: from 1 April to 31 December 2026, taxpayers whose sales including VAT documented by invoices in a given month are PLN 10,000 or less may still issue electronic or paper invoices. The right is lost from the invoice that crosses the PLN 10,000 figure.
- Art. 145n: from 1 February to 31 December 2026, invoices issued using cash registers, and fiscal receipts treated as invoices, may stay outside KSeF.
The Act also re-dates several other provisions of the 2023 Act, including items applying from 1 January 2026, 1 April 2026 and 1 January 2027.
What it means
These dates are the ones that applied. KSeF went live on 1 February 2026 for the largest taxpayers (pl-ksef-large-taxpayers-live-2026) and on 1 April 2026 for everyone else. The Act replaced the single 1 February 2026 start set by the 2024 postponement (pl-ksef-postponement-2024).
The reliefs in Art. 145m and 145n run until 31 December 2026, so they end in seven weeks. Small sellers relying on the PLN 10,000 monthly allowance, and businesses invoicing from cash registers, should be issuing through KSeF from 1 January 2027.
Proof
Ustawa wchodzi w życie z dniem następującym po dniu ogłoszenia, z wyjątkiem art. 1 pkt 1–4, które wchodzą w życie z dniem 1 lutego 2026 r.The Act enters into force on the day following its promulgation, except for Art. 1 items 1–4, which enter into force on 1 February 2026.
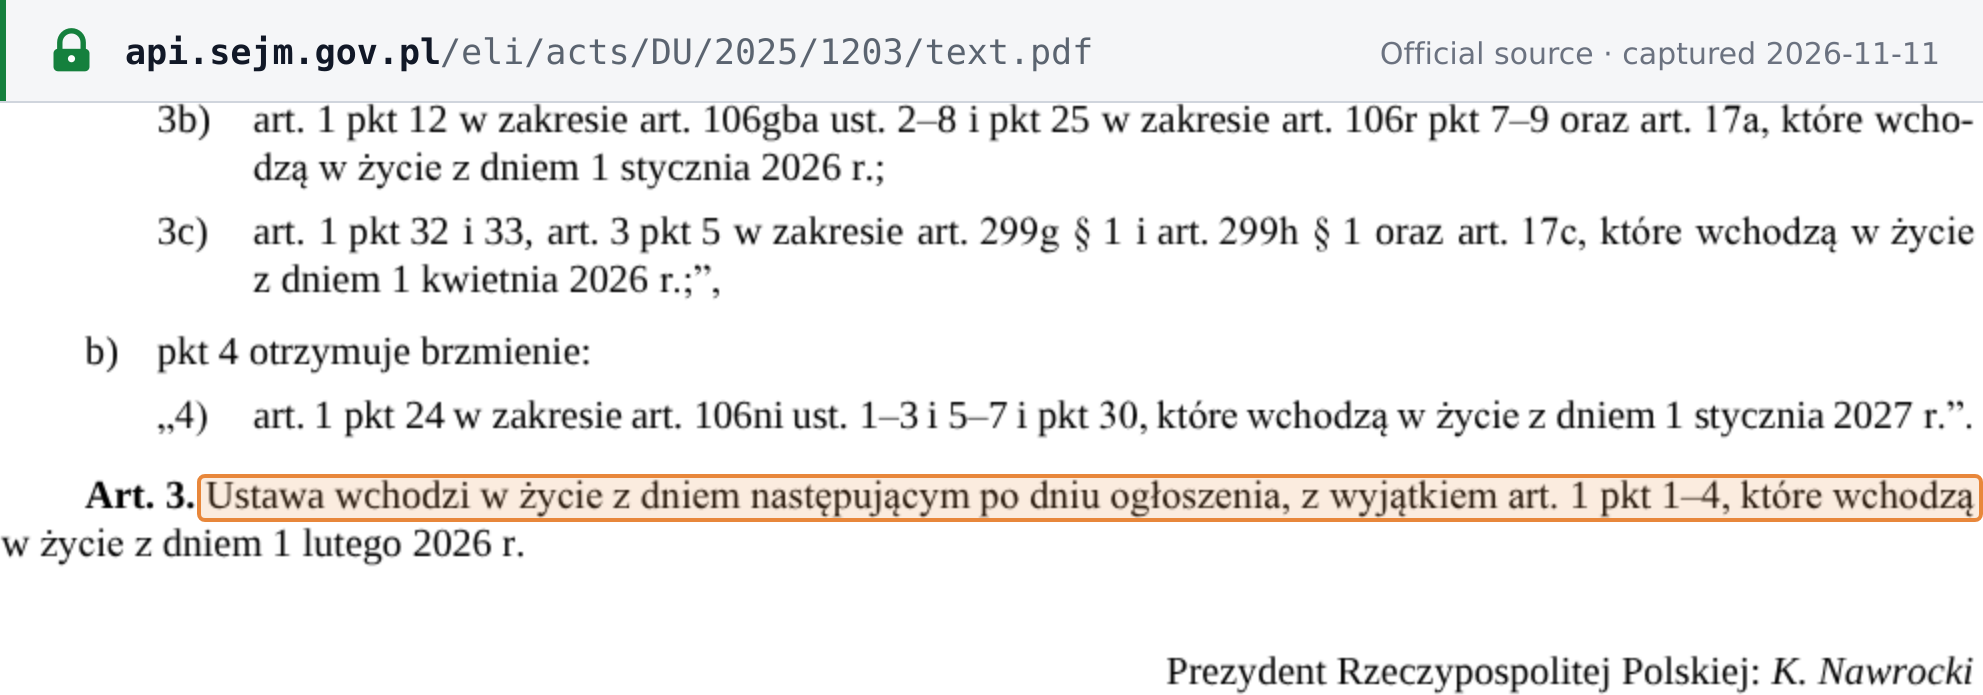 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Dz.U. 2025 poz. 1203 · Ustawa z dnia 5 sierpnia 2025 r. · api.sejm.gov.pl