Poland's Senate passes the 23% VAT bill for energy and certain non-alcoholic drinks unamended; it awaits the President's signature
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Plan ahead
- Announced
- 27 October 2026
- Effective
- 1 January 2027
- Authority
- Sejm Rzeczypospolitej Polskiej (lower house of the Polish Parliament)
- Systems
- Tax engine, POS, ERP
- Verified
- Fetched from official source · high confidence
Producers, importers, retailers and caterers selling energy drinks, non-alcoholic equivalents of alcoholic drinks, and certain drinks containing at least 20% fruit or vegetable juice in Poland.
Beverage producers and retailers: prepare to apply 23% to the affected drinks from 1 January 2027 if the act is signed.
Tax enginePOSERP
Poland's Senate passed without amendments on 27 October 2026 the bill (Sejm print 3135) applying the 23% VAT rate to energy drinks, non-alcoholic equivalents of alcoholic beverages and certain drinks containing at least 20% fruit or vegetable juice, and the act was sent to the President for signature on 28 October 2026. The President has 21 days to sign. The rate change is planned from 1 January 2027.
What changed in detail
This is not yet law. Poland’s Senate passed without amendments on 27 October 2026 the bill amending the VAT Act that the Sejm handled as print 3135. The act was sent to the President for signature on 28 October 2026. The President has 21 days to sign.
The bill would apply the 23% VAT rate to:
- energy drinks;
- non-alcoholic equivalents of alcoholic beverages; and
- certain drinks containing at least 20% fruit, vegetable or fruit-and-vegetable juice.
The rate change is planned to apply from 1 January 2027.
This moves the bill on from its passage in the Sejm on 22 October 2026.
What it means
Parliament has finished with the bill, so the remaining step is the President’s decision, due by around 18 November 2026. Because the planned start date is 1 January 2027, a signature would leave only about six weeks to reprice affected products and update tax codes in point-of-sale and ERP systems. Businesses selling these drinks should prepare the 23% configuration now so it can be switched on if the act is signed, and hold it back if it is not.
Proof
27 października 2026 Stanowisko Senatu Nie wniósł poprawek 28 października 2026 Ustawę przekazano Prezydentowi do podpisu27 October 2026 Position of the Senate: introduced no amendments. 28 October 2026 The act was sent to the President for signature
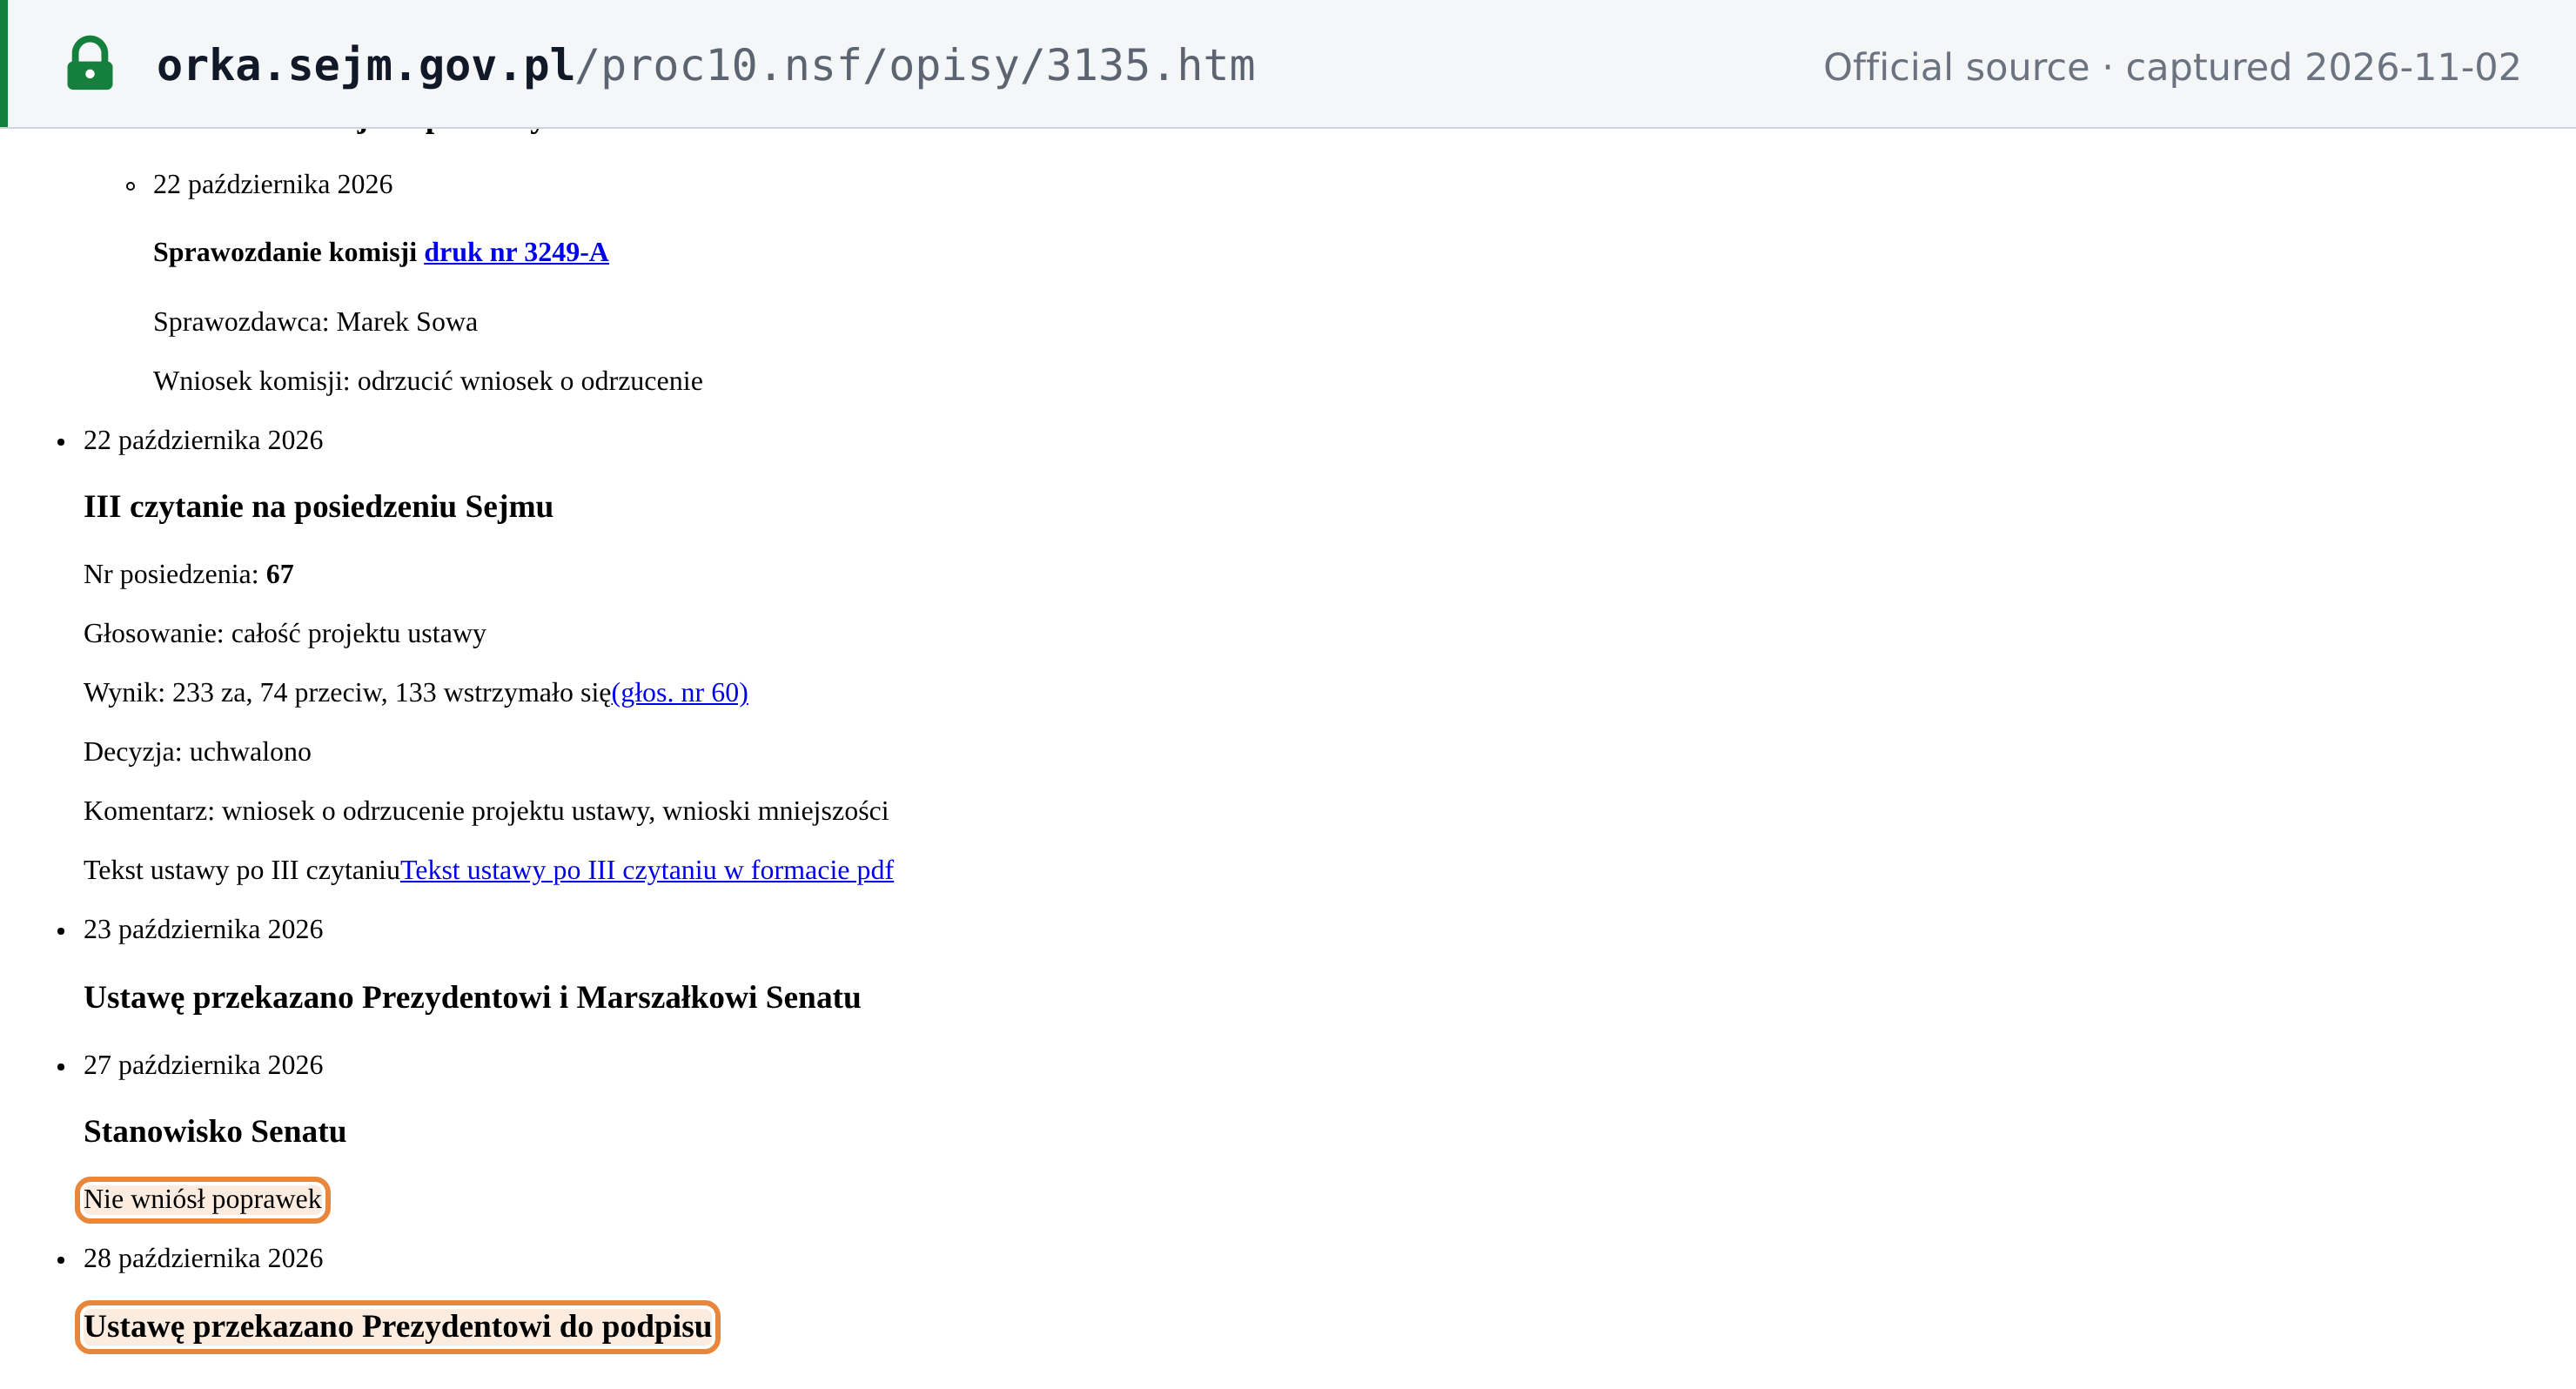 Source snapshot of the official page. Open full size ↗
"date":"2026-10-28","stageName":"Ustawę przekazano Prezydentowi do podpisu""date":"2026-10-28","stageName":"The act was sent to the President for signature"
Archived from the official distribution · Sejm RP legislative process record, print 3135 (api.sejm.gov.pl JSON) · api.sejm.gov.pl