Poland opens its small-business VAT exemption to sellers established in other EU Member States from 2025
This page records one dated change. For the rules in Poland as they stand today, see the Poland guide →
- Jurisdiction
- Poland
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 25 November 2024
- Effective
- 1 January 2025
- Instrument
- PL-USTAWA-poz-1721-2024
- Authority
- Dziennik Ustaw Rzeczypospolitej Polskiej
- Verified
- Fetched from official source · high confidence
Small businesses established in another EU Member State with EU-wide turnover up to EUR 100,000 and Polish sales within the Art. 113(1) limit; also Polish small businesses using the exemption elsewhere in the EU.
No action — monitoring only; in force since 1 January 2025.
Ustawa z dnia 8 listopada 2024 r. (Dz.U. 2024 poz. 1721, published 25 November 2024) transposed EU Directive 2020/285 (SME VAT scheme) by adding Art. 113a and 113b to the Polish VAT Act, with effect from 1 January 2025. A business established in another EU Member State may use the Polish small-business exemption if its EU-wide annual turnover does not exceed EUR 100,000 and its Polish sales stay within the domestic limit in Art. 113 ust. 1. It must hold an EX identification number obtained through its home Member State.
What changed in detail
The Act of 8 November 2024 (Dz.U. 2024 poz. 1721), published on 25 November 2024 and in force from 1 January 2025, transposes Council Directive (EU) 2020/285 on the special scheme for small enterprises by adding Art. 113a and Art. 113b to the Polish VAT Act.
Art. 113a(1) exempts sales made in Poland by a taxable person established in another EU Member State when the conditions are met together:
- its annual turnover in the EU, excluding VAT and including its Polish sales, did not exceed EUR 100,000 in the previous or current tax year;
- its Polish sales did not exceed the domestic limit in Art. 113(1) (PLN 200,000 in 2025; PLN 240,000 from 1 January 2026 under Dz.U. 2025 poz. 896) in the previous or current year;
- it makes none of the supplies excluded from the exemption by Art. 113(13).
Before starting, it must notify its Member State of establishment and obtain there an individual identification number with the suffix EX; the exemption applies from the day that state assigns or confirms the number. The competent Polish tax office for these taxpayers is Naczelnik Urzędu Skarbowego Łódź-Śródmieście. The exemption is lost from the transaction by which the Polish limit or the EUR 100,000 EU limit is exceeded.
Art. 113b is the mirror rule: a business established in Poland whose EU turnover stays within EUR 100,000 may use the exemption in other Member States, through a Polish EX number assigned by its tax office after prior notification.
What it means
This scheme is still in force. Before 2025, Poland’s small-business exemption was not available to a business established elsewhere in the EU. Since 1 January 2025 it can sell in Poland without charging Polish VAT, provided it stays within both limits and has the EX number. Both limits are tested on the previous and the current year, so a business can lose the exemption part-way through a year. Because the exemption is lost from the very sale that crosses a limit, sellers near either limit need to track turnover continuously, not at year end.
Proof
Zwalnia się od podatku sprzedaż dokonywaną przez podatnika posiadającego siedzibę działalności gospodarczej na terytorium państwa członkowskiego innym niż terytorium kraju, jeżeli łącznie są spełnione następujące warunki:Sales made by a taxable person established in a Member State other than Poland are exempt from tax, provided that the following conditions are jointly met:
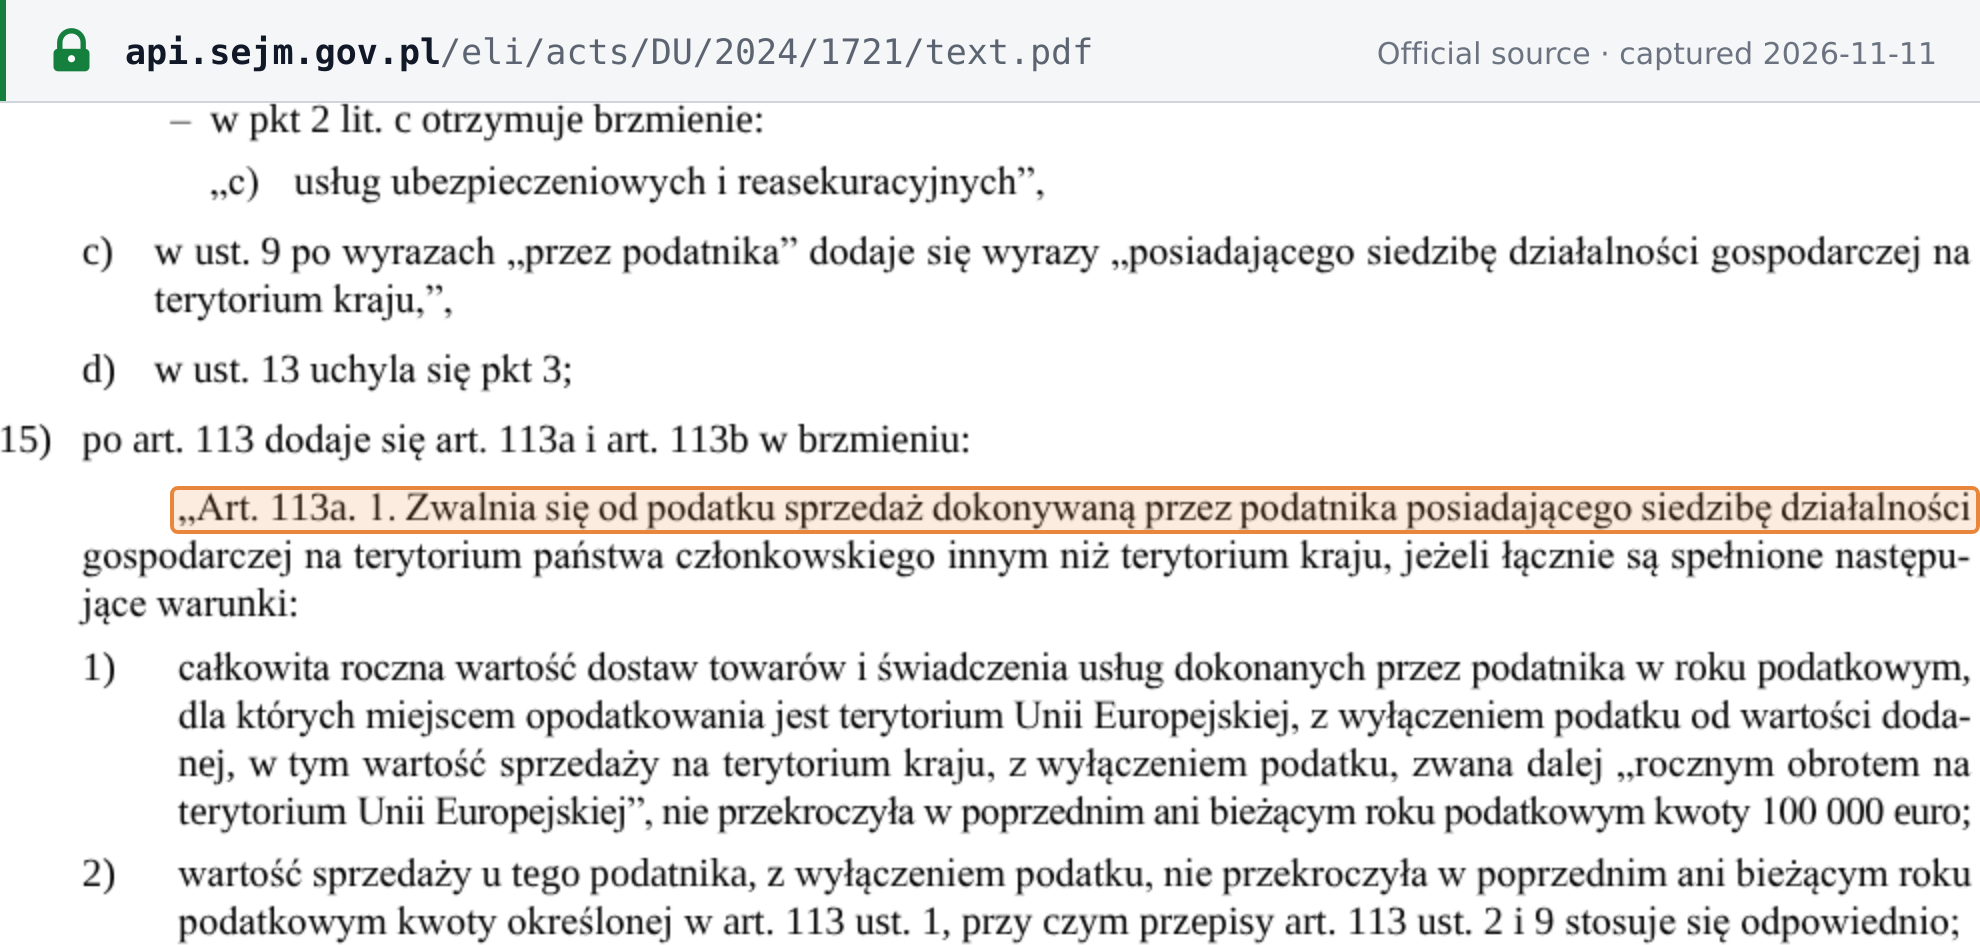 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Dz.U. 2024 poz. 1721 · Ustawa z dnia 8 listopada 2024 r. · api.sejm.gov.pl