Portugal extends the SME transition for B2G e-invoicing to 31 December 2024 in the 2024 State Budget
This page records one dated change. For the rules in Portugal as they stand today, see the Portugal guide →
- Jurisdiction
- Portugal
- Tax
- VAT (IVA)
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 29 December 2023
- Effective
- 1 January 2025
- Authority
- Assembleia da República
- Verified
- Fetched from official source · high confidence
Micro, small and medium enterprises (EU Recommendation 2003/361/EC) and public bodies acting as co-contractors that supply Portuguese public-sector contracting entities.
No action — superseded by DL 13-A/2025 and later Lei 73-A/2025. Monitoring only.
Lei n.º 82/2023, de 29 de dezembro (OE 2024), Article 305, amends Article 9(4) of Decreto-Lei n.º 111-B/2017 to extend to 31 December 2024 the transitional period during which micro, small and medium enterprises (and public bodies acting as co-contractors) may supply public-sector contracting entities without structured (CIUS-PT) B2G e-invoices. Mandatory B2G e-invoicing for SMEs would therefore apply from 1 January 2025. The deadline was later extended to 31 December 2025 by Decreto-Lei n.º 13-A/2025 (Article 163).
What changed in detail
Portugal’s State Budget law for 2024, Lei n.º 82/2023, de 29 de dezembro, published in Diário da República n.º 250/2023, rewrites Article 9(4) of Decreto-Lei n.º 111-B/2017 through its Article 305.
Article 9 of that decree-law phases in mandatory electronic invoicing in public procurement: suppliers to public-sector contracting entities must issue structured electronic invoices in the CIUS-PT format. Paragraph 4 gives a longer transitional period to two groups:
- micro, small and medium enterprises, as defined in Commission Recommendation 2003/361/EC of 6 May 2003; and
- public entities when they act as co-contracting parties.
The amended paragraph extends that period to 31 December 2024. On that wording, structured B2G e-invoicing would have become mandatory for these suppliers from 1 January 2025. Large companies were not covered by the extension.
What it means
This deadline never bit. Portugal pushed it back twice more, each time by a one-year extension in a later law:
- Decreto-Lei n.º 13-A/2025, Article 163, moved it to 31 December 2025, with effect from 1 January 2025.
- Lei n.º 73-A/2025 (State Budget 2026), Article 260(2), moved it to 31 December 2026.
As of November 2026, an SME supplying the Portuguese public sector must be able to send CIUS-PT invoices from 1 January 2027, unless the 2027 State Budget, still before Parliament, extends the period again. Treat 31 December 2024 as history only.
Proof
4 — O prazo referido no número anterior é alargado até 31 de dezembro de 2024 para as micro, pequenas e médias empresas, definidas nos termos da Recomendação 2003/361/CE da4 — The period referred to in the previous paragraph is extended to 31 December 2024 for micro, small and medium-sized enterprises, as defined in Recommendation 2003/361/EC
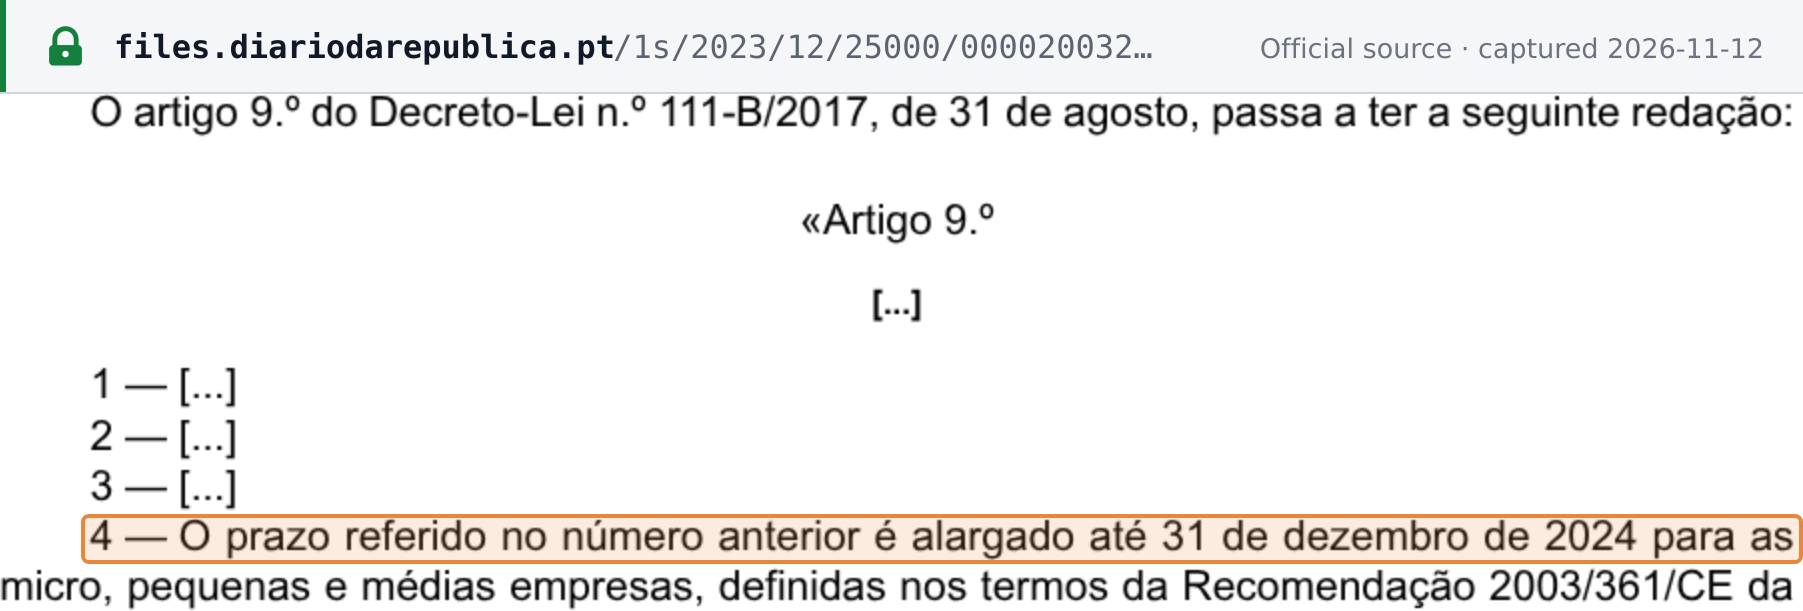 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Lei n.º 82/2023, de 29 de dezembro (Orçamento do Estado para 2024), Diário da República n.º 250/2023, Série I, art. 305.º (p. 164 of the PDF) · files.diariodarepublica.pt