Saudi Arabia narrows zero-rating for services to non-GCC residents: no benefit while in a GCC state, no work on goods located there
This page records one dated change. For the rules in Saudi Arabia as they stand today, see the Saudi Arabia guide →
- Jurisdiction
- Saudi Arabia
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Action required
- Announced
- 19 November 2024
- Instrument
- SA-BOARD-RESOLUTION-01-06-24
- Authority
- Zakat, Tax and Customs Authority (ZATCA)
- Verified
- Fetched from official source · medium confidence
Saudi VAT-registered suppliers of services to customers resident outside the GCC.
Businesses supplying services to non-GCC residents should review whether their supplies meet the revised Article 33 conditions for zero-rating: the customer or related person must not benefit from the service while present in any GCC state, and the service must not be physically performed on goods in a GCC state.
ZATCA Board Resolution No. (01-06-24) of 19 November 2024, effective on publication in the Official Gazette (April 2025), amended Article 33(2)(C) and (D) of the VAT Implementing Regulations. Services supplied to non-GCC residents are zero-rated only if the customer or any related person does not directly benefit from the service while present in a GCC member state, and the service is not physically performed on tangible goods located in a GCC member state.
What changed in detail
The amending instrument is ZATCA Board of Directors Resolution No. (01-06-24) dated 19 November 2024, which ZATCA’s consolidated Arabic Regulations cite as resolution (24-06-01), passed by circulation on 17 Jumada al-Awwal 1446H. The amendments take effect on publication in the Official Gazette. ZATCA issued its explanatory guideline (Issue 1) and the 10th version of the consolidated Regulations in April 2025. The commonly reported effective date is 18 April 2025; that day comes from secondary sources, and no official page we read states it.
The resolution amends paragraphs (C) and (D) of Article 33(2) of the VAT Implementing Regulations, which set the conditions for zero-rating services supplied to a customer resident outside the GCC.
As amended, a service qualifies for the 0% rate only if both of these hold:
- the customer, or any person related to the customer, does not directly benefit from the service while present in a GCC member state; and
- the service is not physically performed on tangible goods located in a GCC member state during the supply.
A service that fails either condition is not zero-rated under Article 33 and falls to be taxed under the general rules, normally at the standard rate of 15%. ZATCA’s guideline on the amendments sets the two conditions out in section 2.7.
What it means
The amended Article 33 is in ZATCA’s current consolidated Regulations (10th version, April 2025) and we found no later change, so it is in force. In practice it closes two routes to zero-rating: a non-resident client whose staff use the service while in Riyadh or Dubai, and repair or testing work on goods that are physically in the GCC. Exporters of services should look at where the customer’s people actually are when they benefit, not only at the contracting party’s address. Related changes from the same resolution: VAT groups (Article 10), electronic marketplaces (Article 47), credit notes, return corrections and refunds (Articles 54, 63, 69 and 70).
Proof
The amendments to the Implementing Regulation of Value Added Tax (VAT) introduced clarifications on the tax treatment of services supplied to non-GCC residents, which qualify for a 0% VAT rate provided the applicable conditions are met.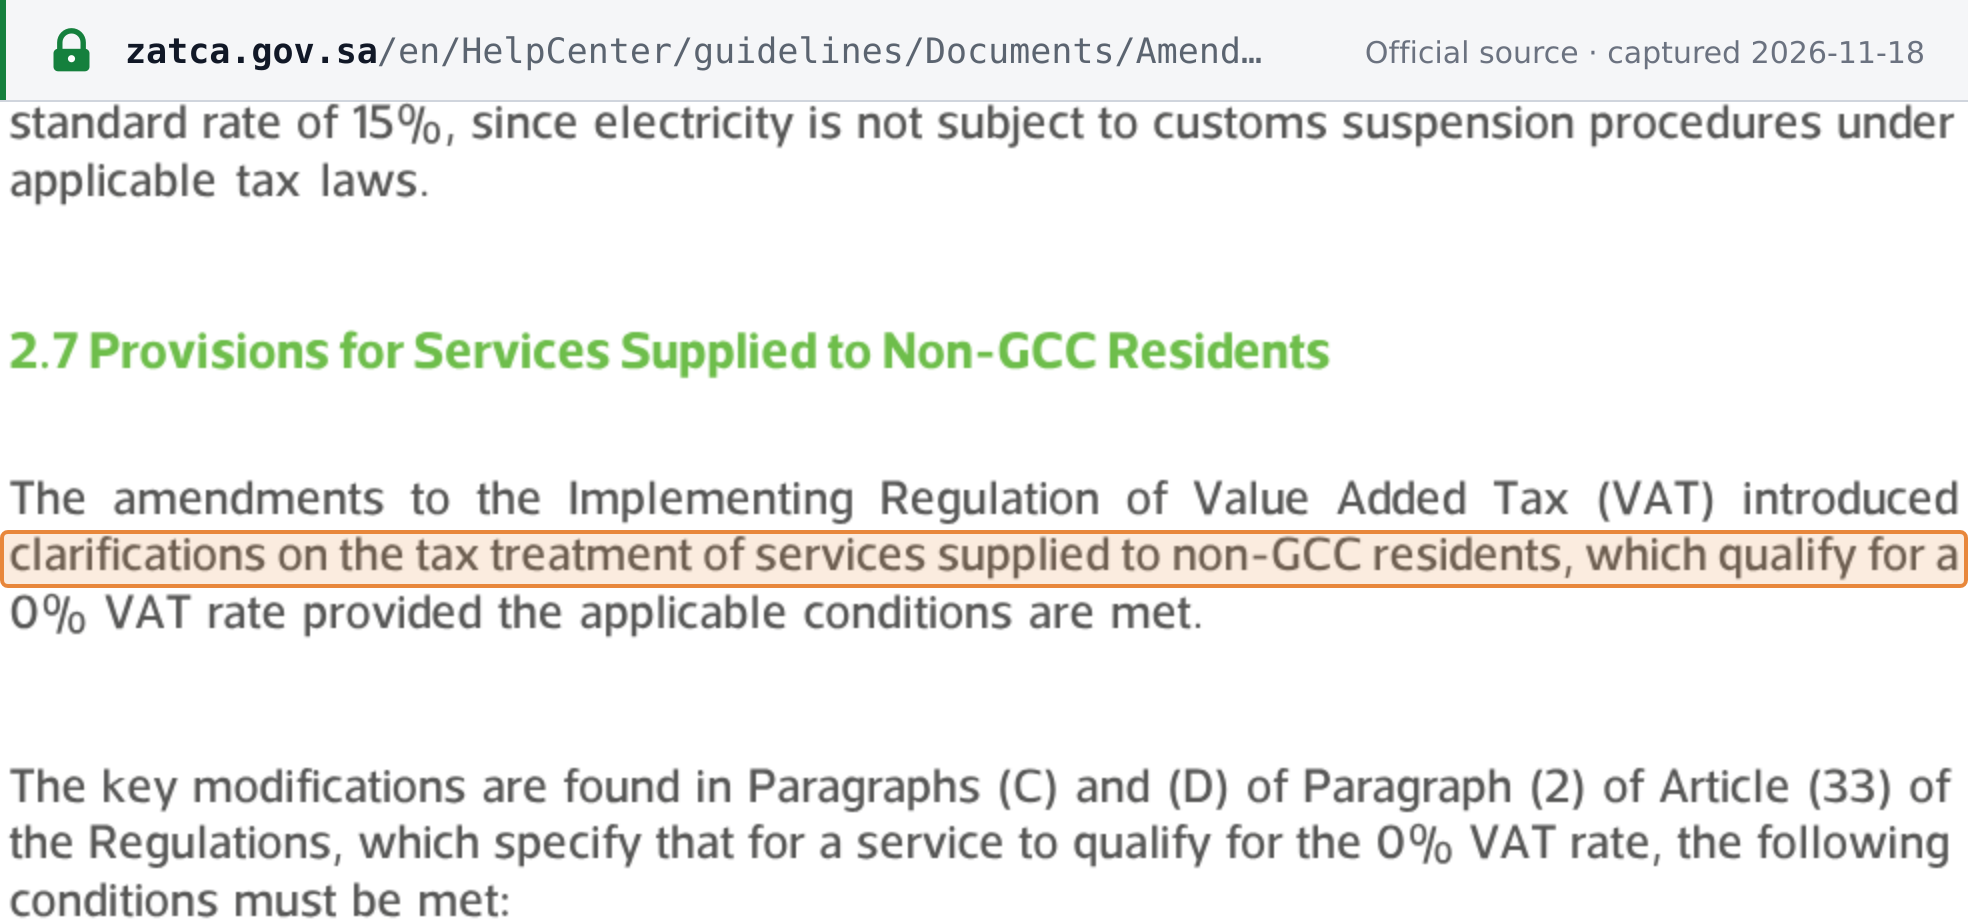 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · ZATCA, Guideline for Amendments to the Implementing Regulation of Value Added Tax (VAT), issued by Board of Directors Resolution No. (01-06-24) dated November 19, 2024, Issue 1, April 2025 · zatca.gov.sa