Serbia rewrites electronic VAT recording in SEF from 1 January 2025
- Jurisdiction
- Serbia
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 28 November 2024
- Effective
- 1 January 2025
- Instrument
- RS-ACT-94-2024
- Authority
- Poreska uprava Republike Srbije (Tax Administration of Serbia)
- Verified
- Fetched from official source · high confidence
Serbian VAT payers acting as tax debtors, public-sector entities and voluntary SEF users that record VAT in the e-invoicing system (SEF).
No action — monitoring only.
Amendments to the Law on Electronic Invoicing in Sl. glasnik RS No. 94/2024 (28 November 2024), in force 15 December 2024 and applied from 1 January 2025, rewrote the electronic VAT-recording rules in SEF: VAT payers (and public-sector entities and voluntary SEF users) record VAT calculated collectively per tax period, with individual per-liability recording for reverse-charge supplies, supplies to business buyers and first transfers of new buildings, by the 12th day of the following month; input-VAT recording is due by the 12th, as at the 10th if made later. The law also created the SEF preliminary VAT return, originally for tax periods after 31 December 2025.
What changed in detail
The Law on Amendments and Supplements to the Law on Electronic Invoicing, published in Službeni glasnik RS No. 94/2024 on 28 November 2024, enters into force on 15 December 2024 and applies from 1 January 2025 (its article 14). Articles 3 and 12 apply from 15 December 2024; articles 4 and 5 apply to VAT tax periods beginning after 31 December 2024.
The law rewrites article 4 of the Law on Electronic Invoicing. The obligation to record calculated VAT electronically in the e-invoicing system (SEF) lies with the tax debtor who is a VAT payer, and with public-sector entities and voluntary SEF users that are not. Recording is done collectively for each tax period, by tax rate, but individually, per liability, for supplies where the recipient is the tax debtor (reverse charge), for supplies by a tax-debtor supplier to buyers taxed on self-employment or corporate income, and for the first transfer of newly built buildings. The deadline is the 12th day of the month following the tax period.
In article 4a, input VAT is recorded collectively by the 12th day of the following month, as at the day before recording, or as at the 10th where recording is made after the 10th.
Article 7 of the law introduced the SEF preliminary VAT return, originally for tax periods beginning after 31 December 2025.
What it means
The collective and individual VAT-recording rules have applied since January 2025 and remain in force; the consolidated text now runs to Službeni glasnik 80/2026. The preliminary VAT return has not started on the original timetable: Law 109/2025 moved it to tax periods beginning after 31 December 2026, and the July 2026 rulebook amendment set out its forms (PPP PDV). The 80/2026 amendment adds a further recording duty for purchases from unregistered farmers from 1 July 2027 (Law 80/2026).
Proof
Овај закон ступа на снагу 15. децембра 2024. године, а примењиваће се од 1. јануара 2025. годинеThis Law enters into force on 15 December 2024 and shall apply from 1 January 2025
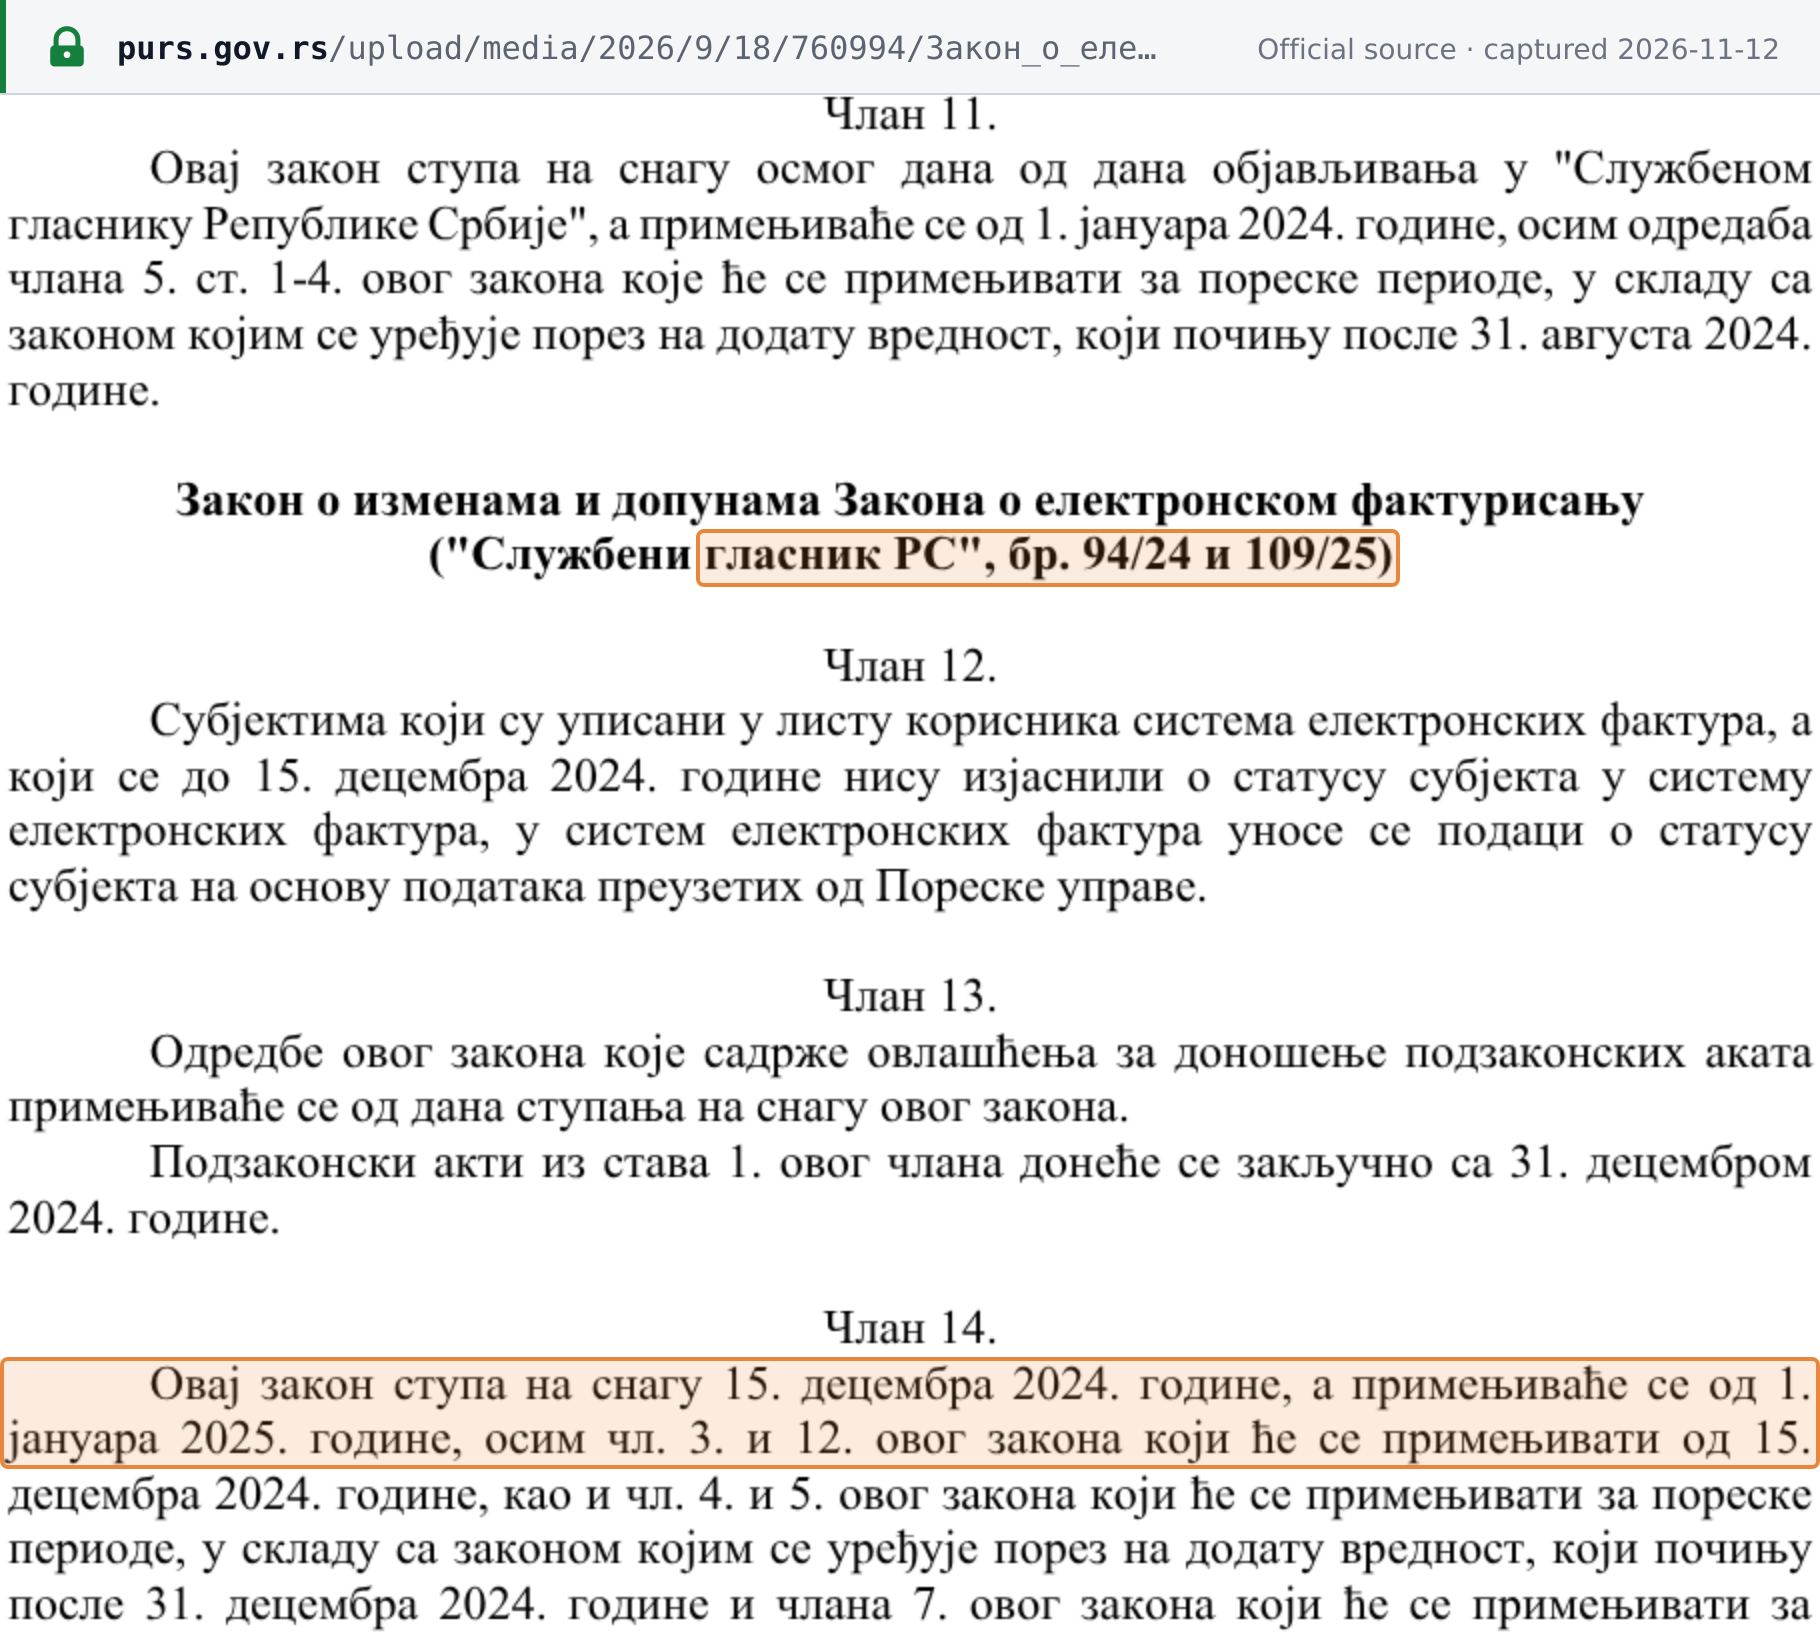 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Закон о електронском фактурисању („Службени гласник РС“, бр. 44/21, 129/21, 138/22, 92/23, 94/24, 109/25, 80/26), consolidated text, Poreska uprava · www.purs.gov.rs