South Africa lets casinos account for VAT on table games on gross gaming revenue
This page records one dated change. For the rules in South Africa as they stand today, see the South Africa guide →
- Jurisdiction
- South Africa
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 14 March 2025
- Effective
- 1 January 2025
- Instrument
- ZA-REGULATION-GN-5994
- Authority
- National Treasury (South Africa)
- Verified
- Fetched from official source · high confidence
Licensed casinos that are registered VAT vendors and operate table games of chance played against the house with live croupiers.
No action required — in force since 1 January 2025. Casino operators running table games of chance should confirm their VAT201 accounting uses gross gaming revenue as permitted by the regulations.
Government Notice 5994 published in Government Gazette 52294 (14 March 2025) under s 74(2) of the Value-Added Tax Act 89 of 1991 prescribed the VAT Regulations for Casino Table Games of Chance, with retrospective effect from 1 January 2025. The regulations permit casinos to account for VAT on table games of chance based on gross gaming revenue (closing bankroll plus credit slips plus drop, less opening bankroll and fills) for the relevant VAT period on their VAT201 return, rather than accounting on each individual transaction.
What changed in detail
Government Notice 5994 (Government Gazette 52294, 14 March 2025) prescribes the VAT Regulations for Casino Table Games of Chance, made by the Minister of Finance under section 74(2) of the Value-Added Tax Act 89 of 1991. Regulation 3 sets commencement at 1 January 2025, before the date of publication.
The regulations define:
- casino as a casino under the National Gambling Act, 2004, run by a licensed person that is a registered vendor;
- table game of chance as a gambling game played against the casino and operated by one or more live croupiers; and
- gross gaming revenue, per table game, as the closing bankroll plus credit slips for cash, chips or tokens returned to the cage, plus drop, less the opening bankroll and fills to the table, as determined under provincial gambling legislation.
Under regulation 2, a casino may account for VAT on table games on the gross gaming revenue for the tax period:
- (a) the gross gaming revenue goes in field 1 of the VAT return, with the tax fraction applied in field 4;
- (b) no deduction under section 16(3)(d) is allowed for amounts already taken into account in calculating gross gaming revenue; and
- (c) the casino must keep records adequate for the Commissioner to verify the liability, including the records used for provincial gaming board audits.
What it means
The regulations remain in force; the SARS regulations index lists no amendment as of November 2026.
They align the VAT base for table games with the figure casinos already report to provincial gaming boards, rather than requiring a separate calculation of bets and payouts. The method is optional (“may”), but a casino using it cannot also deduct winnings paid under section 16(3)(d) where those amounts are already netted in gross gaming revenue. Because the start date of 1 January 2025 came before publication, early-2025 returns may have needed reconciling.
Proof
These regulations are called the “VAT Regulations for Casino Table Games of Chance” and will come into effect on 1 January 2025.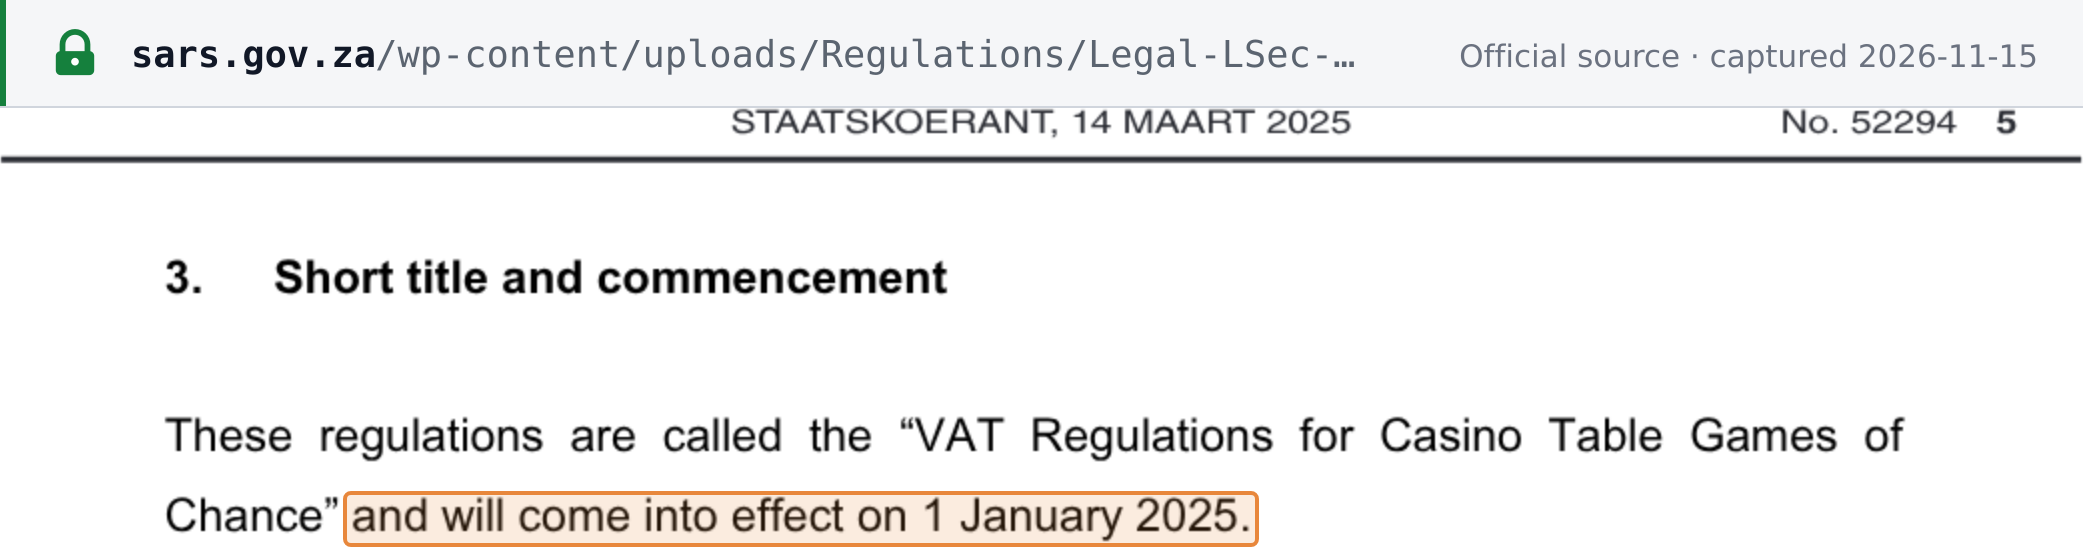 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Government Notice 5994, Government Gazette No. 52294, 14 March 2025 · www.sars.gov.za