South Africa enacts that the announced VAT increase never took effect, keeping the rate at 15%
This page records one dated change. For the rules in South Africa as they stand today, see the South Africa guide →
- Jurisdiction
- South Africa
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 1 April 2026
- Effective
- 1 May 2025
- Instrument
- ZA-ACT-3-2026
- Authority
- Parliament of the Republic of South Africa
- Verified
- Fetched from official source · high confidence
All South African VAT vendors.
No action required. The 15.5% rate announced on 12 March 2025 never came into effect; the standard VAT rate remains 15%.
The Rates and Monetary Amounts and Amendment of Revenue Laws Act 3 of 2026 (Government Gazette 54446, 1 April 2026, assented to 31 March 2026) enacts section 13 to prevent the VAT rate increase that the Minister of Finance announced on 12 March 2025. The Act provides that notwithstanding section 7(4) of the VAT Act 89 of 1991 and the ministerial announcement, the alteration of the VAT rate does not come into effect. Subsection (2) deems this to have effect from 1 May 2025. The standard VAT rate therefore remains at 15%.
What changed in detail
Section 13 of the Rates and Monetary Amounts and Amendment of Revenue Laws Act 3 of 2026 (Government Gazette 54446, 1 April 2026; assented to on 31 March 2026) is headed “Prevention of increase of rate in terms of Value-Added Tax Act 89 of 1991, announced by Minister of Finance in national annual budget of 2025”.
Section 13(1) provides that the alteration of the VAT rate in section 7 of the VAT Act does not come into effect, despite:
- section 7(4) of the VAT Act; and
- the Minister of Finance’s announcement of 12 March 2025 in the national annual budget.
Under section 13(2), subsection (1) is deemed to have come into effect on 1 May 2025. The standard VAT rate therefore stayed at 15% throughout. The 15.5% rate announced on 12 March 2025 never came into effect.
What it means
This closes the 2025 VAT rate episode in statute. The increase announced in the March 2025 budget never applied, and section 13 removes any argument that section 7(4) gave the announcement legal effect before Parliament acted. Vendors that kept charging 15% from 1 May 2025 were right, and there is nothing to correct.
The episode also showed how fragile the announcement mechanism in section 7(4) is. Proposals to change that mechanism followed in 2026, including the Taxation Laws Amendment Bill (B32 of 2026) provisions.
Proof
Despite— (a) section 7(4) of the Value-Added Tax Act, 1991; and (b) the announcement by the Minister of Finance on 12 March 2025 in the national annual budget, contemplated in section 27(1) of the Public Finance Management, 1999 (Act No. 1 of 1999), the alteration of the VAT rate specified in section 7 of that Act, 1991, does not come into effect. (2) Subsection (1) is deemed to have come into effect on 1 May 2025.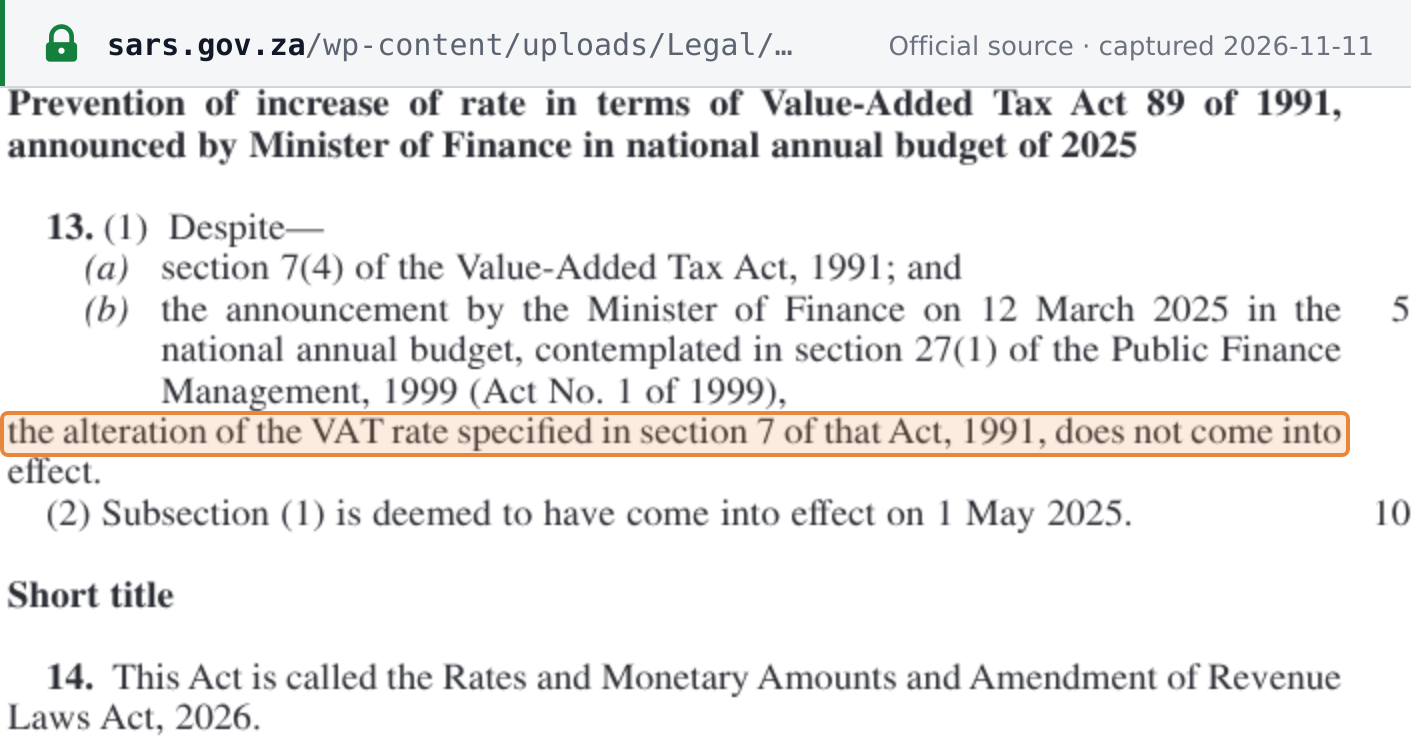 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Rates and Monetary Amounts and Amendment of Revenue Laws Act 3 of 2026, Government Gazette No. 54446, 1 April 2026 · www.sars.gov.za