South Africa makes gold agents hold the zero-rating proof and pay the VAT if they do not
This page records one dated change. For the rules in South Africa as they stand today, see the South Africa guide →
- Jurisdiction
- South Africa
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 22 December 2023
- Effective
- 1 April 2024
- Instrument
- ZA-ACT-17-of-2023
- Authority
- Parliament of the Republic of South Africa
- Verified
- Fetched from official source · high confidence
Registered VAT vendors acting as agents for resident registered-vendor principals in zero-rated supplies of gold under s 11(1)(f) or in gold exports.
No action required — in force since 1 April 2024. Gold agents who supply s 11(1)(f) gold or export gold on behalf of resident registered-vendor principals must retain documentary proof acceptable to the Commissioner or face output tax liability.
Taxation Laws Amendment Act 17 of 2023 (GG 49894, 22 December 2023) inserted s 54(2C) into the Value-Added Tax Act 89 of 1991 by s 52 of the Amendment Act, effective 1 April 2024. The provision requires that where gold is supplied under s 11(1)(f) or exported by an agent acting on behalf of a resident registered-vendor principal, and both the agent and principal are registered vendors, the agent must obtain and retain documentary proof acceptable to the Commissioner. The agent is not required to provide the principal with copies of documentary evidence, but is liable for output tax if not in possession of requisite documents.
What changed in detail
Section 52 of the Taxation Laws Amendment Act 17 of 2023 (Government Gazette 49894, 22 December 2023) inserts subsection (2C) into section 54 of the Value-Added Tax Act 89 of 1991, from 1 April 2024 (section 52(2)).
The subsection applies where gold is supplied as contemplated in section 11(1)(f), or is exported in the circumstances in paragraph (a) or (d) of the definition of “exported” and in accordance with section 12 of the Precious Metals Act, 2005, by an agent acting for a principal, and:
- (a) the agent is a registered vendor; and
- (b) the principal is a resident of the Republic and a registered vendor.
In that case the agent must obtain and retain documentary proof acceptable to the Commissioner. Under the proviso, the agent:
- (aa) is not required to provide the principal with copies of the documentary evidence; and
- (bb) is liable to account for output tax if it does not hold the requisite documents to substantiate the zero rate on supplies it made for the principal, other than zero-rated tax invoices where the principal supplied its gold directly to the purchaser.
What it means
The gold rule still applies, but not in this text. Taxation Laws Amendment Act 5 of 2026 substituted section 54(2C) from 1 April 2026 and extended it to agents exporting silver; see South Africa extends the agent documentary-proof rule to silver exports. For gold, the substance is unchanged.
The practical effect is that the risk of a failed zero rate sits with the agent, not the principal. An agent that cannot produce the export or s 11(1)(f) documents on audit pays output tax out of its own pocket, even though it never owned the gold. Agents should hold the full documentary set themselves rather than rely on the principal’s files.
Proof
(2C) For the purposes of this Act, where gold is supplied as contemplated in section 11(1)(f) or where gold is exported from the Republic in the circumstances contemplated in paragraph (a) or (d) of the definition of ‘exported’ in section 1(1) and in accordance with section 12 of the of the Precious Metals Act, 2005 (Act No. 37 of 2005), by an agent who is acting on behalf of another person who is the principal for the purposes of that supply and— (a) the agent is a registered vendor; and (b) the principal is a resident of the Republic and a registered vendor, the agent must obtain and retain documentary proof as is acceptable to the Commissioner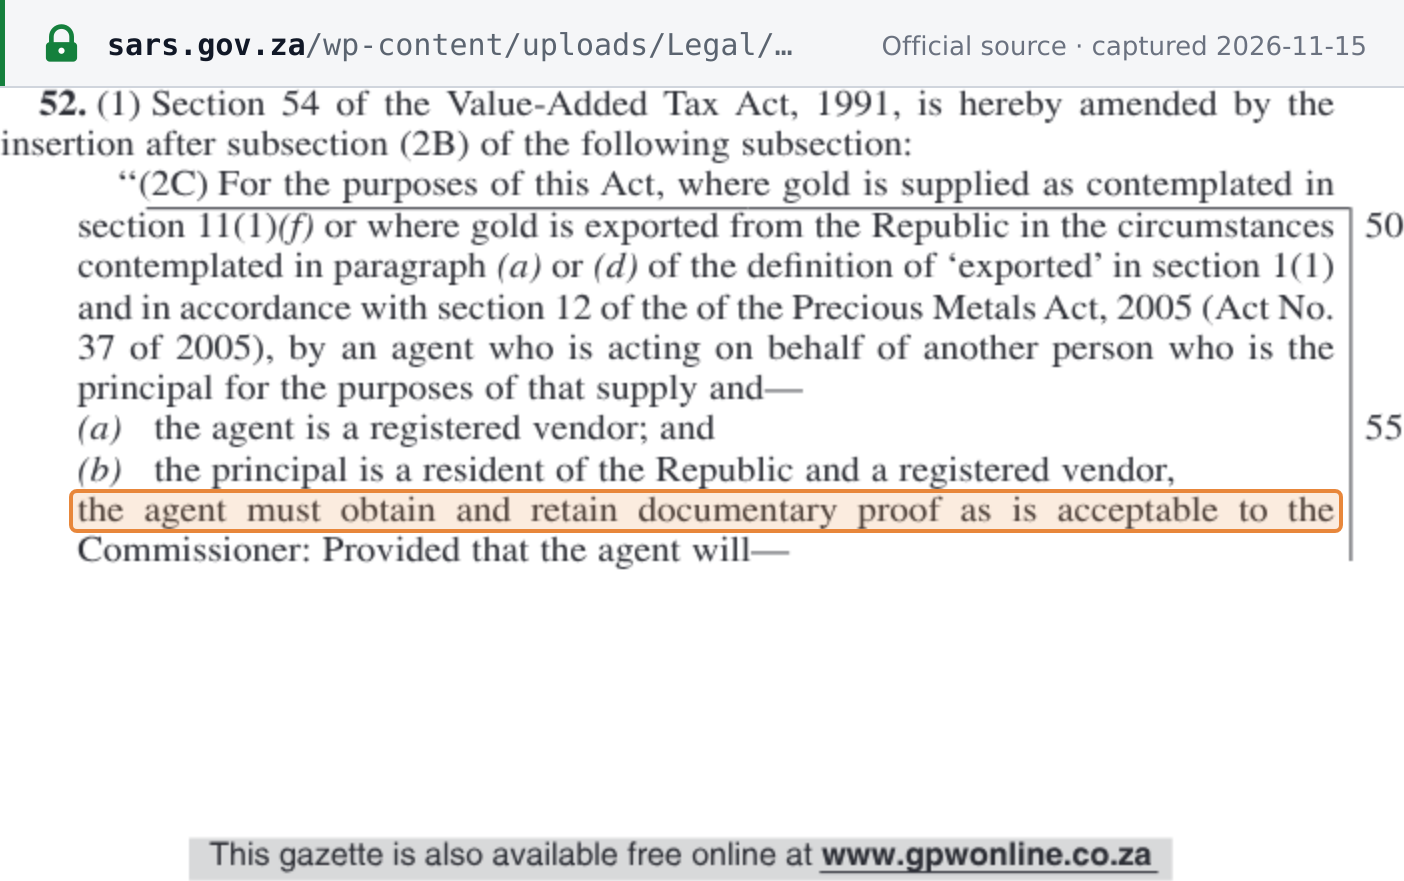 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Taxation Laws Amendment Act 17 of 2023, Government Gazette No. 49894, Notice 4226, 22 December 2023 · www.sars.gov.za