South Africa zero-rates testing services for non-resident non-vendors
This page records one dated change. For the rules in South Africa as they stand today, see the South Africa guide →
- Jurisdiction
- South Africa
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 1 April 2026
- Effective
- 1 April 2026
- Instrument
- ZA-ACT-5-of-2026
- Authority
- Parliament of the Republic of South Africa
- Verified
- Fetched from official source · high confidence
South African vendors that supply testing services (for example clinical trials or laboratory testing) to non-resident customers that are not VAT vendors, and international carriers' airtime voucher distributors.
No action required — in force since 1 April 2026. Vendors supplying testing services to non-resident, non-vendor clients should review whether supplies qualify for zero-rating under s 11(2)(z); consumable goods used in such testing may also be zero-rated under s 11(1)(x). International telecom carriers providing airtime vouchers for distribution should review the s 8(31)/s 10(30)/s 11(2)(zA) distribution services regime.
Taxation Laws Amendment Act 5 of 2026 (GG 54448, 1 April 2026) inserted s 11(2)(z), s 11(1)(x), and s 11(2)(zA) into the Value-Added Tax Act 89 of 1991 by s 41 of the Amendment Act, effective 1 April 2026. Section 11(2)(z) zero-rates testing services supplied to a non-resident, non-vendor where the services are not supplied directly in connection with moveable property in South Africa (except property referred to in s 11(1)(x) or exported to that person afterwards), or directly to that person while it is in the Republic (s 11(2)(z)(ii)). Section 11(1)(x) zero-rates consumable goods supplied in the course of such testing services that become unusable or have no commercial value as a direct result of their use in the testing and are necessary for the supply of the testing services. Section 11(2)(zA) zero-rates the supply of distribution services deemed to be made under s 8(31). Related provisions in the same Act: s 38(1)(c) inserts s 8(31) (airtime voucher distribution services deeming) and s 40 inserts s 10(30) (consideration for such distribution services deemed equal to the difference between purchase price and selling price of the airtime voucher); both effective 1 April 2026.
What changed in detail
Section 41 of the Taxation Laws Amendment Act 5 of 2026 (Government Gazette 54448, 1 April 2026) amends section 11 of the Value-Added Tax Act 89 of 1991, from 1 April 2026 (section 41(2)).
- Section 11(2)(z) zero-rates testing services supplied to a person that is not a resident and not a vendor, except testing services supplied directly (i) in connection with moveable property in the Republic when the services are rendered, unless the property is goods under section 11(1)(x) or is exported to that person afterwards, or (ii) to that person while it is in the Republic.
- Section 11(1)(x) zero-rates consumable goods supplied in the course of those testing services, where the goods become unusable or have no commercial value as a direct result of the testing and are necessary for it.
- Section 11(2)(zA) zero-rates distribution services deemed supplied under section 8(31).
The same Act inserts section 8(31) (section 38(1)(c)): a vendor’s supply of an airtime voucher usable only for telecommunications services outside the Republic, provided by a non-resident non-vendor carrier, is disregarded, and the amount the vendor keeps is consideration for distribution services. Section 10(30) (section 40) values that supply at the difference between the voucher’s purchase and selling price. Both apply from 1 April 2026.
What it means
These zero rates have applied since 1 April 2026, and no later Act has amended them as of November 2026.
For laboratories and testing houses, the key condition is the customer’s status: a foreign customer registered for VAT in South Africa does not qualify, so the supply stays standard-rated. Testing goods that remain in South Africa disqualifies the supply unless they are consumed in the test or exported to the customer afterwards, so export evidence matters. The airtime-voucher rules mean distributors account for VAT on their margin only, and at zero rate.
Proof
(z) the services comprise of testing services supplied to a person who is not a resident of the Republic and that is not a vendor, not being testing services that are supplied directly— (i) in connection with moveable property situated in the Republic at the time the services are rendered, except moveable property that is— (aa) referred to in section 11(1)(x); or (bb) exported to the said person subsequent to the supply of such services;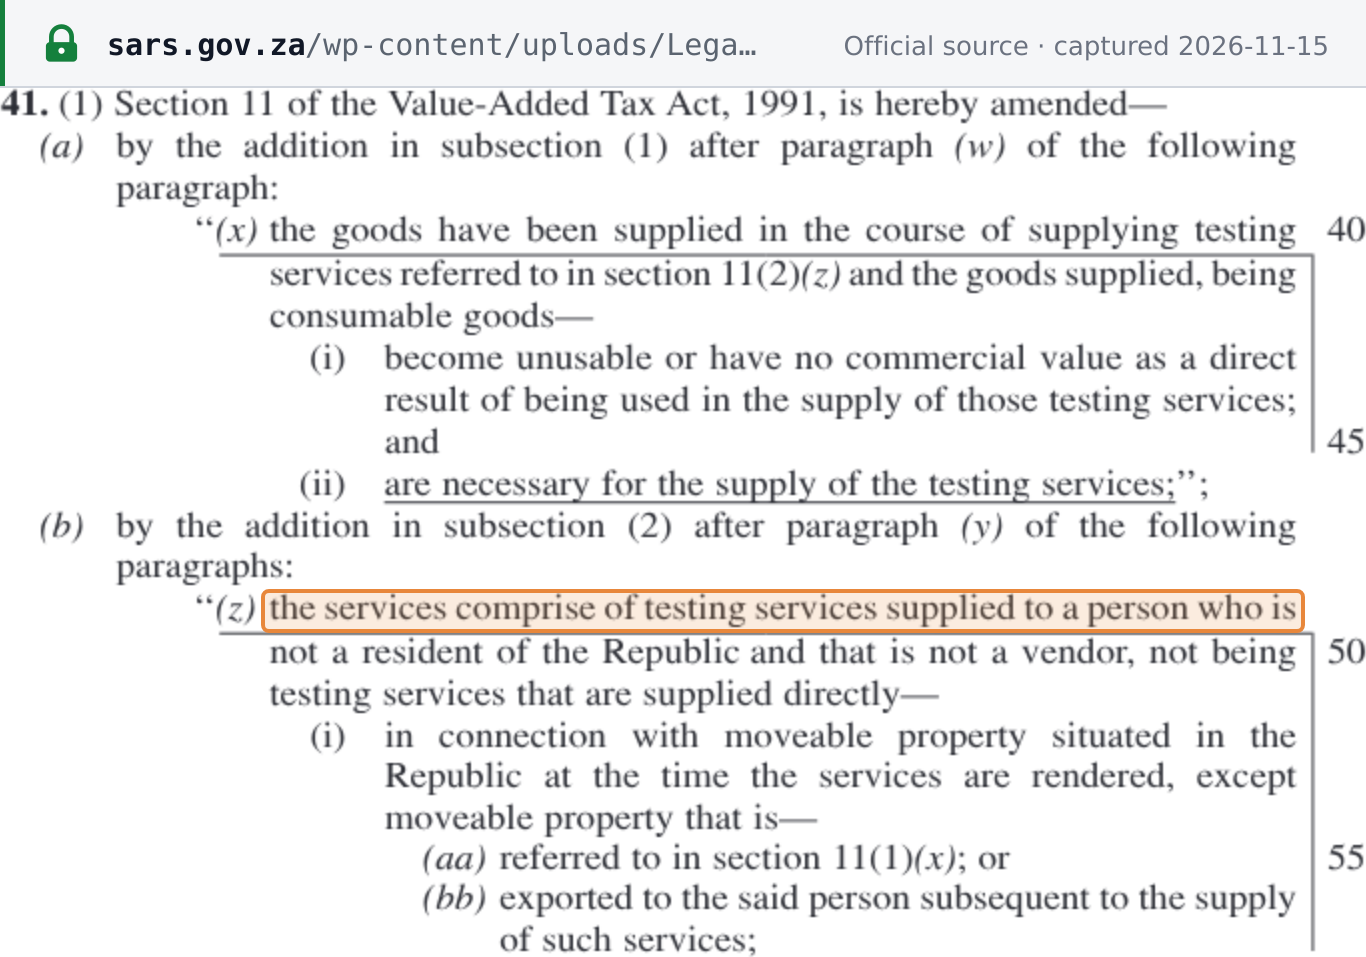 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Taxation Laws Amendment Act 5 of 2026, Government Gazette No. 54448, 1 April 2026 · www.sars.gov.za
(ii) to the said person if the said person is in the Republic at the time when the services are rendered;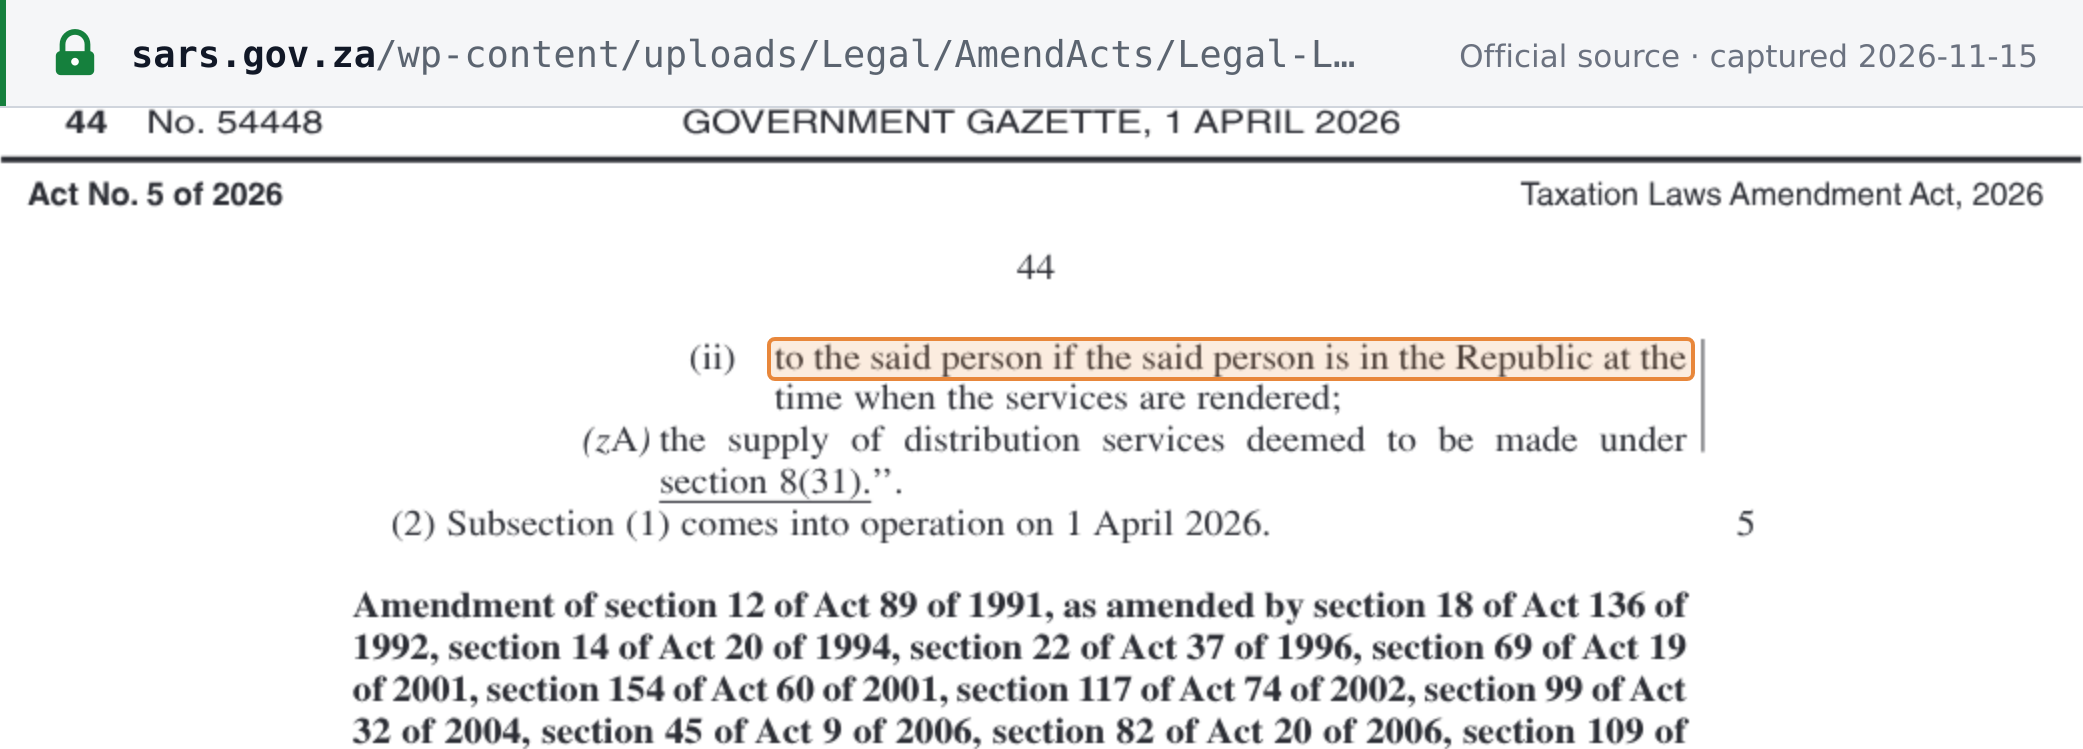 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Taxation Laws Amendment Act 5 of 2026, Government Gazette No. 54448, 1 April 2026 · www.sars.gov.za