South Korea requires app-market operators to report brokered domestic sales to the NTS from 1 July 2025
This page records one dated change. For the rules in South Korea as they stand today, see the South Korea guide →
- Jurisdiction
- South Korea
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 28 February 2025
- Effective
- 1 July 2025
- Instrument
- KR-PRESIDENTIAL-DECREE-35353
- Authority
- 법제처 국가법령정보센터 (Ministry of Government Legislation, Republic of Korea)
- Verified
- Fetched from official source · high confidence
App-market operators (앱 마켓사업자) under Article 2(13) of the Telecommunications Business Act that broker or settle domestic sales.
No action — monitoring only.
VAT Enforcement Decree amended by Presidential Decree No. 35353 (28 February 2025, generally in force from promulgation): (1) Art. 121(2)2 — app-market operators (앱 마켓사업자, as defined under the Telecommunications Business Act Art. 2(13)) added to the list of entities required to submit domestic-sales/payment-intermediary transaction data to the Commissioner of the National Tax Service; this provision in force from 1 July 2025 (부칙 제1조 단서 / 제4조); (2) Art. 104-2 — specifies grounds for ad-hoc VAT assessment (수시부과) under VAT Act Art. 57-2 (frequent business-location moves, closed/suspended businesses); (3) Art. 69(21) and 72(9) — demerger invoicing: the surviving or newly established entity in a corporate split may issue tax invoices for supplies made by the dissolving entity from the split plan date to the registration date.
What changed in detail
Presidential Decree No. 35353, promulgated on 28 February 2025, amended the Enforcement Decree of the Value Added Tax Act. Most of it took effect on promulgation; the app-market rule took effect on 1 July 2025 (addendum Article 1, proviso).
- Article 121(2), app-market operators. Article 75(1)5 of the VAT Act lets the decree name further businesses that must submit data on sales they act as agent for, broker or settle. The rewritten Article 121(2) names two: bulletin-board operators that broker supplies and are designated by the National Tax Service, and app-market operators under Article 2(13) of the Telecommunications Business Act. The statement of reasons says the aim is to cross-check the mobile-content sales of telecommunications businesses. It applies to sales brokered or settled on or after 1 July 2025 (addendum Article 4).
- Article 104-2, ad-hoc assessment. It defines the “other grounds” for ad-hoc VAT assessment (수시부과) under VAT Act Article 57-2 by reference to Article 103(1): frequent moves of business place, a business place in an area where such moves are frequent, and suspended or closed businesses, among others.
- Articles 69(21) and 72(9), demergers. Between the split date in the plan and registration, the surviving or new company that takes over a supply may issue or receive the tax invoice for the dissolving company.
What it means
All three provisions are still in force; the consolidated decree current from 1 April 2026 carries Article 121(2)2 and Article 104-2 unchanged.
For app stores, this is a data duty, not a tax: the operator does not become liable for the developer’s VAT, but the National Tax Service now receives the sales figures to match against what developers declare. It runs alongside Law No. 20776, which from the same date extended the reporting duty to foreign platforms (kr-foreign-platform-reporting-2025). Article 104-2 completes the ad-hoc assessment power created by Law No. 20614 (kr-animal-blood-exemption-2024).
Proof
앱 마켓사업자로 하여금 국내에서 판매를 대행하거나 중개한 관련 명세를 국세청장 등에게 제출하도록 함.App-market operators are required to submit to the Commissioner of the National Tax Service and others the relevant particulars of domestic sales they have acted as agent for or brokered.
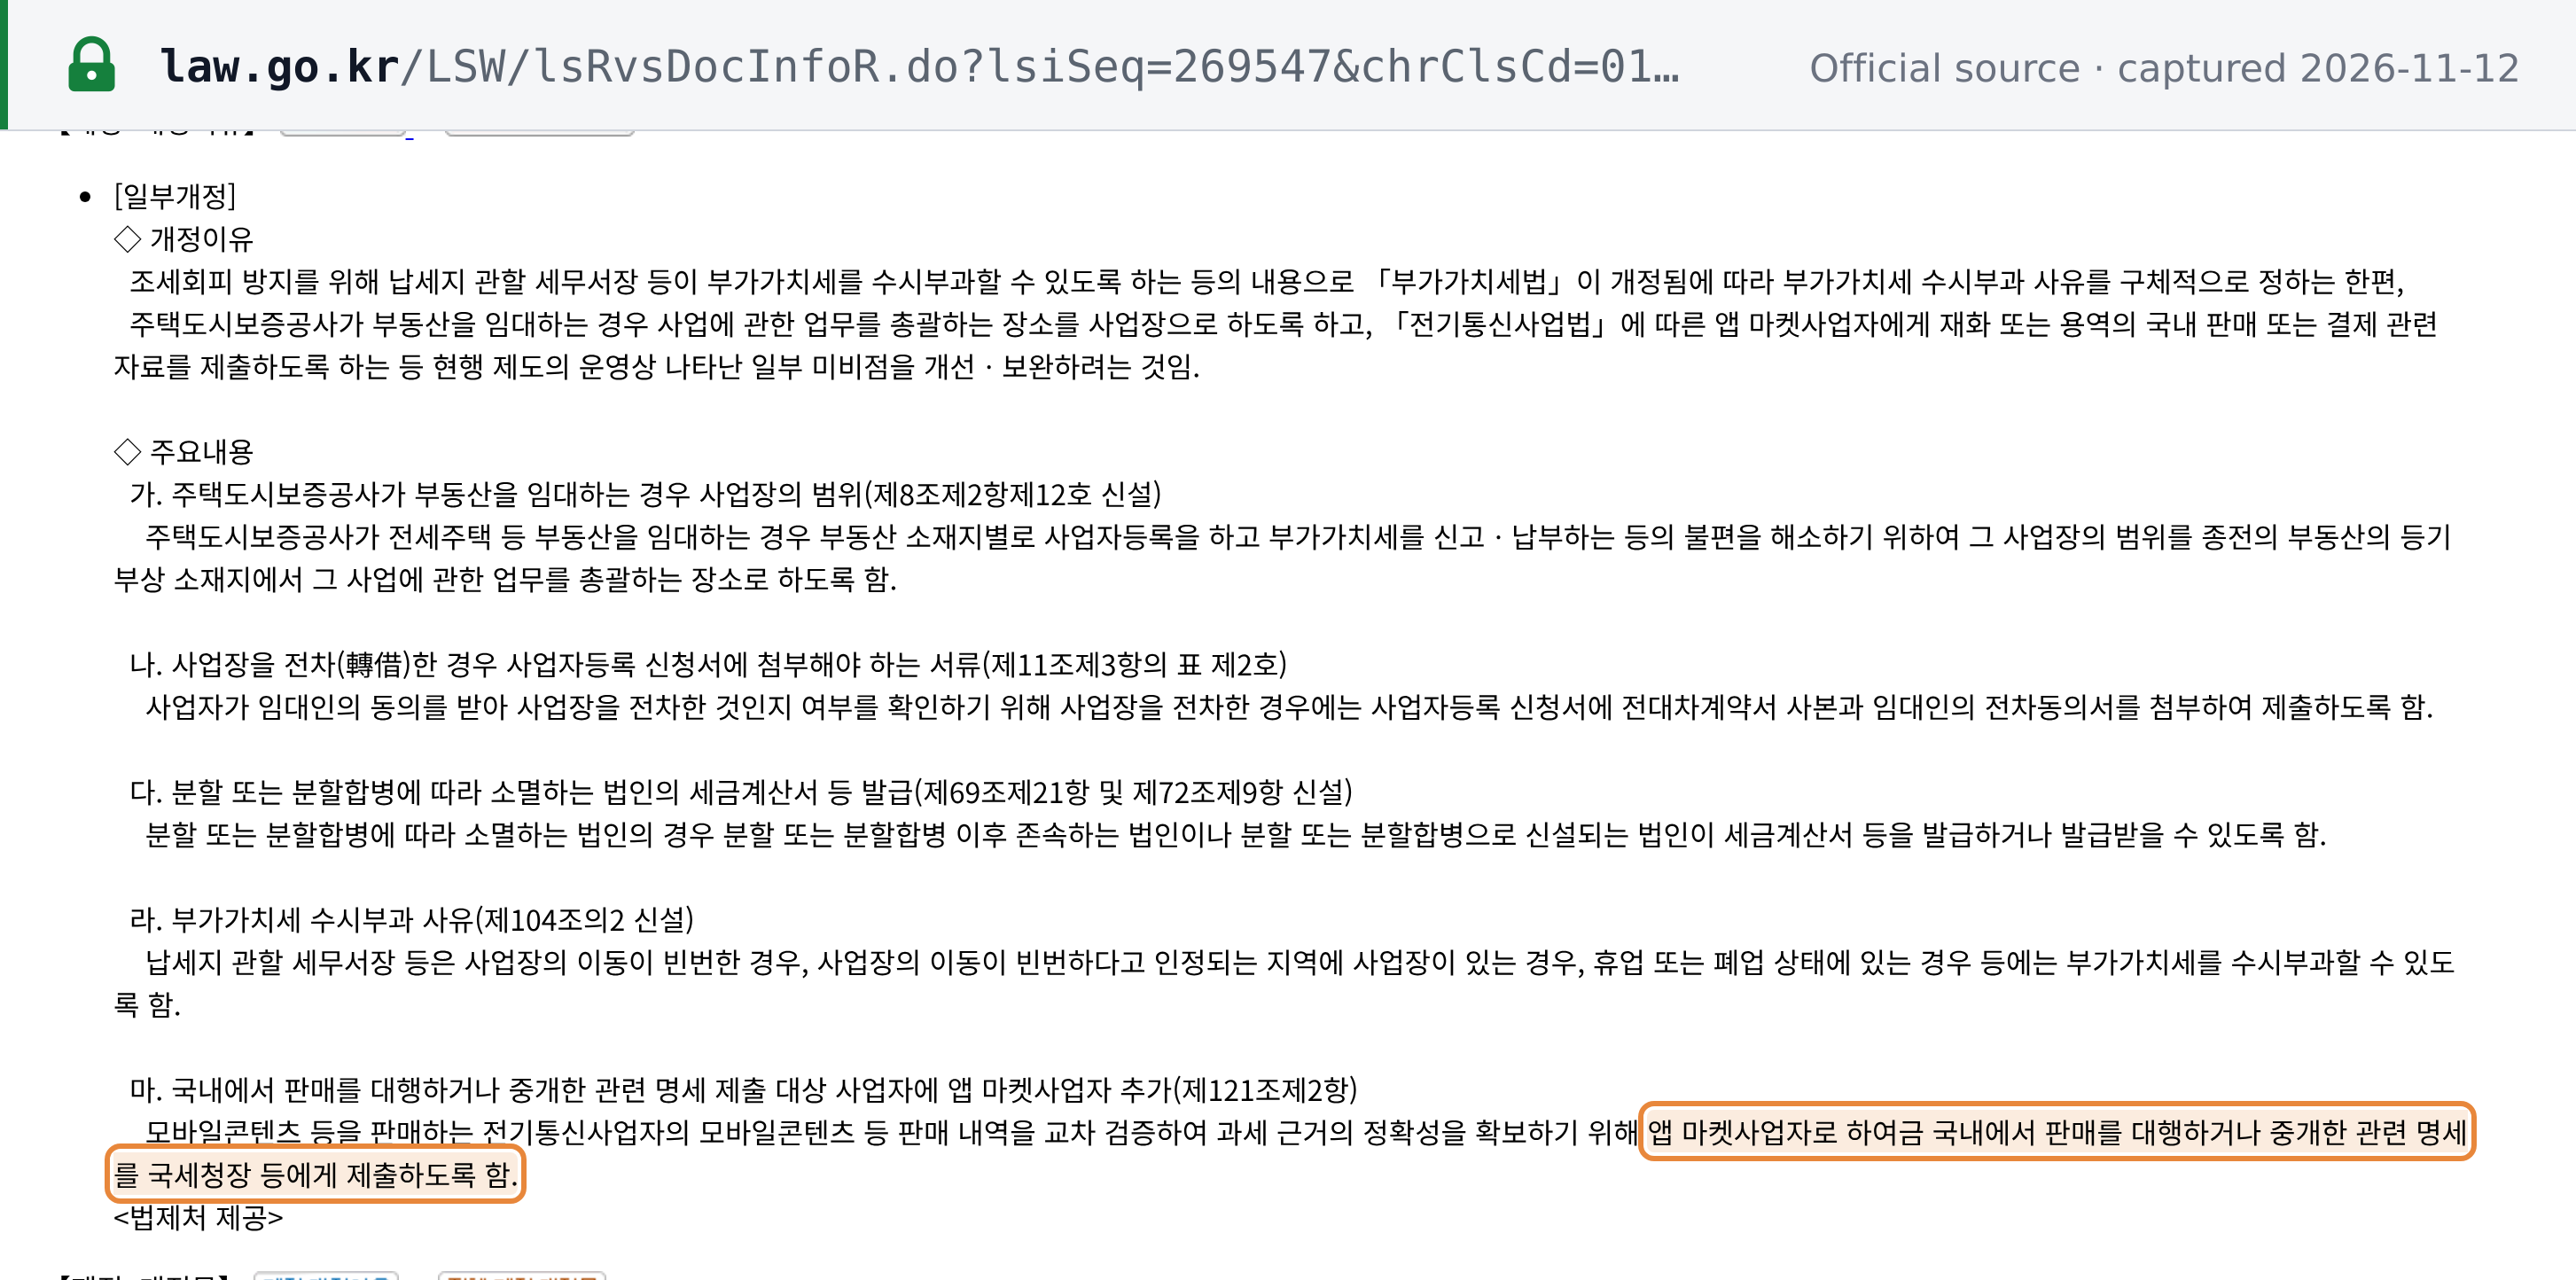 Source snapshot of the official page. Open full size ↗