South Korea raises the simplified VAT taxpayer threshold from KRW 80 million to KRW 104 million
This page records one dated change. For the rules in South Korea as they stand today, see the South Korea guide →
- Jurisdiction
- South Korea
- Tax
- VAT
- Change type
- Threshold
- Status
- In force
- Impact
- FYI
- Announced
- 29 February 2024
- Effective
- 1 July 2024
- Instrument
- KR-ENFORCEMENT-DECREE-34270
- Authority
- 법제처 국가법령정보센터 (Ministry of Government Legislation, Republic of Korea)
- Verified
- Fetched from official source · high confidence
Individual business operators whose prior-year supply proceeds (공급대가, VAT included) are below KRW 104 million, subject to the excluded business types.
No action — monitoring only.
Presidential Decree No. 34270 of 29 February 2024 amended Article 109(1) of the VAT Enforcement Decree to raise the simplified taxpayer (간이과세자) annual supply threshold from KRW 80 million to KRW 104 million. Per the addendum (Article 10), the amended threshold applies when determining simplified taxpayer status for 1 July 2024 to 30 June 2025 based on 2023 supply proceeds. The threshold is set at 130% of the statutory 80-million ceiling by enforcement decree.
What changed in detail
Presidential Decree No. 34270, signed on 29 February 2024, amended Article 109(1) of the Enforcement Decree of the Value Added Tax Act. It replaced “8천만원” (KRW 80 million) with “1억4백만원” (KRW 104 million) as the amount below which an individual business operator’s prior-year supply proceeds (공급대가) qualify it for simplified taxation (간이과세). The VAT Act lets the Enforcement Decree set this amount; KRW 104 million is 130% of the KRW 80 million in the Act.
Under Article 10 of the decree’s addendum, the new threshold applies from the determination of simplified-taxpayer status for 1 July 2024 to 30 June 2025, made on 2023 supply proceeds. The same decree added a re-entry rule (Article 116(3) and (4)): a sole proprietor who gave up simplified status to issue tax invoices may, subject to conditions, return to it within three years of giving it up if its prior-year supply proceeds are at least KRW 48 million and below KRW 104 million.
Article 109(1) of the consolidated Enforcement Decree in force from 1 April 2026 still reads KRW 104 million, with the 29 February 2024 amendment noted against it.
What it means
This change is still in force. The addendum makes KRW 104 million apply from the 2024–25 determination onwards, not only for that one year, and the consolidated decree on law.go.kr, current from 1 April 2026, still sets it.
Simplified taxpayers pay VAT at reduced, sector-based rates on supply proceeds and have lighter filing duties. The cost is that a simplified taxpayer below KRW 48 million cannot issue tax invoices, which matters to business customers who need them to claim input VAT. The re-entry rule added by the same decree is aimed at proprietors in that position. The test runs on VAT-inclusive proceeds of the previous calendar year and is redone each year.
Proof
간이과세가 적용되는 직전 연도 공급대가의 합계액 기준을 현행 8천만원에서 1억4백만원으로 확대함.The prior-year supply-proceeds threshold for simplified taxation is raised from the current KRW 80 million to KRW 104 million.
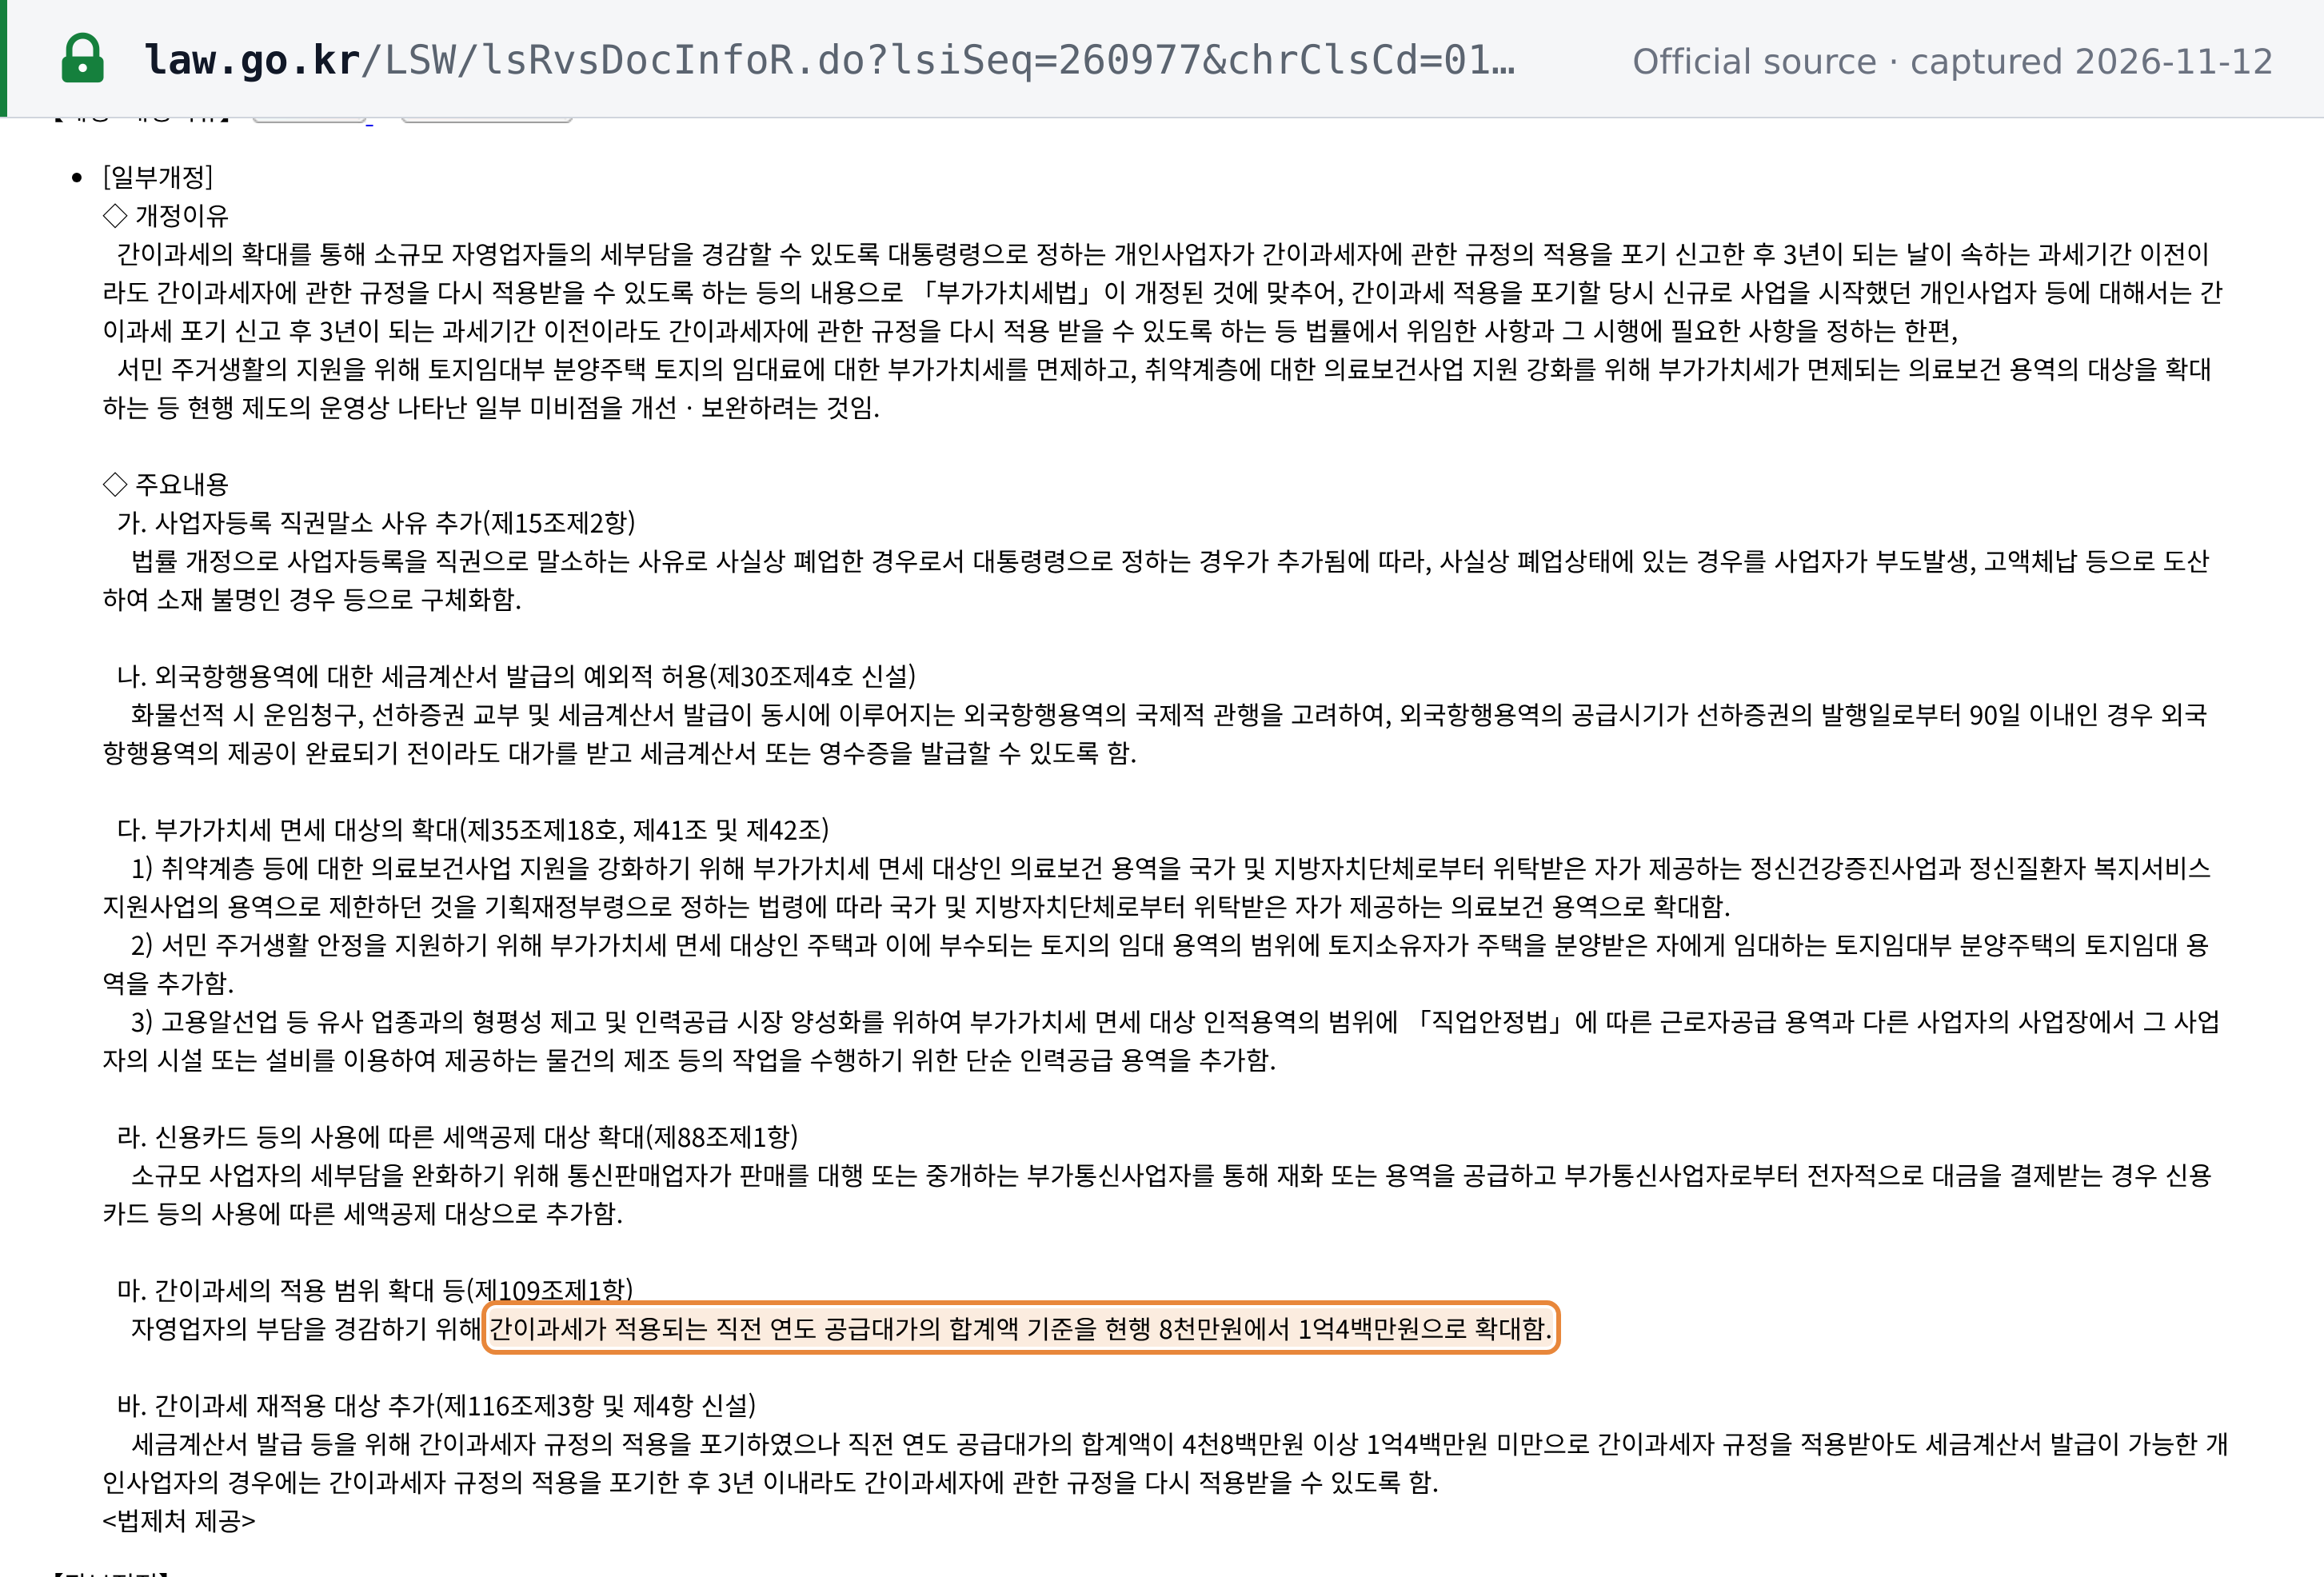 Source snapshot of the official page. Open full size ↗