Spain phases out its food VAT cuts over the second half of 2024 and moves olive oil to 4% for good (RDL 4/2024)
This page records one dated change. For the rules in Spain as they stand today, see the Spain guide →
- Jurisdiction
- Spain
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 27 June 2024
- Effective
- 1 July 2024
- Instrument
- ES-ROYAL-DECREE-LAW-4-2024
- Authority
- Boletín Oficial del Estado (BOE)
- Verified
- Fetched from official source · high confidence
Spanish suppliers and importers of bread, flour, milk, cheese, eggs, fruit, vegetables, legumes, tubers, cereals, olive oil, seed oils and pasta, including retailers under the equivalence surcharge.
No action — monitoring only. The transitional food VAT rates under RDL 4/2024 expired 31 December 2024; standard rates (4% for basic foods, 10% for seed oils and pasta) restored from 1 January 2025. Olive oil is permanently at the 4% super-reduced rate from 1 January 2025.
Real Decreto-ley 4/2024, de 26 de junio (BOE-A-2024-12944, 27 June 2024) phases out the food VAT emergency reductions in two tranches: (1) 1 July – 30 September 2024: 0% VAT on basic foods (bread, milk, cheese, eggs, fruits, vegetables, legumes, tubers, cereals and olive oil) and 5% on seed oils and pasta; (2) 1 October – 31 December 2024: 2% VAT on basic foods and olive oil, 7.5% on seed oils and pasta. From 1 January 2025 standard reduced rates (4%/10%) are restored. Article 2 also permanently classifies olive oil as a basic foodstuff taxed at the 4% super-reduced rate under Article 91.Two.1.1.° of Ley 37/1992 (the VAT Law).
What changed in detail
Real Decreto-ley 4/2024, de 26 de junio, was published in the BOE (no. 155) on 27 June 2024, entered into force on 28 June 2024 and was validated by Congress on 23 July 2024.
Article 1 sets two transitional tranches for food VAT:
| Period | Basic foods and olive oil | Seed oils and pasta |
|---|---|---|
| 1 July – 30 September 2024 | 0% (equivalence surcharge 0%) | 5% (surcharge 0.62%) |
| 1 October – 31 December 2024 | 2% (surcharge 0.26%) | 7.5% (surcharge 1%) |
Basic foods are common bread, bread-making flour, the listed milks, cheese, eggs, and natural fruits, vegetables, legumes, tubers and cereals. Olive oil joins them in both tranches, while seed oils stay with pasta.
Article 2, with effect from 1 January 2025, adds “g) Los aceites de oliva” to article 91.Dos.1.1.º of the VAT Law (Ley 37/1992), so olive oil is taxed at the 4% super-reduced rate on a permanent basis. From the same date the other products return to their ordinary rates: 4% for basic foods and 10% for seed oils and pasta.
What it means
The transitional rates in article 1 are spent: they ended on 31 December 2024, closing the temporary food VAT cuts that began in January 2023 and were last extended by Real Decreto-ley 8/2023.
Article 2 is the lasting change. Olive oil is still listed at 4% in article 91 of the VAT Law, so it no longer sits at 10% with other oils. Product master data built before 2025 often groups all edible oils together; olive oil and seed oils now need separate rate codes.
Proof
Dos. Con efectos desde el 1 de octubre de 2024 y vigencia hasta el 31 de diciembre de 2024: 1. Se aplicará el tipo del 7,5 por cientoTwo. With effect from 1 October 2024 and in force until 31 December 2024: 1. The 7.5 per cent rate of VAT shall apply
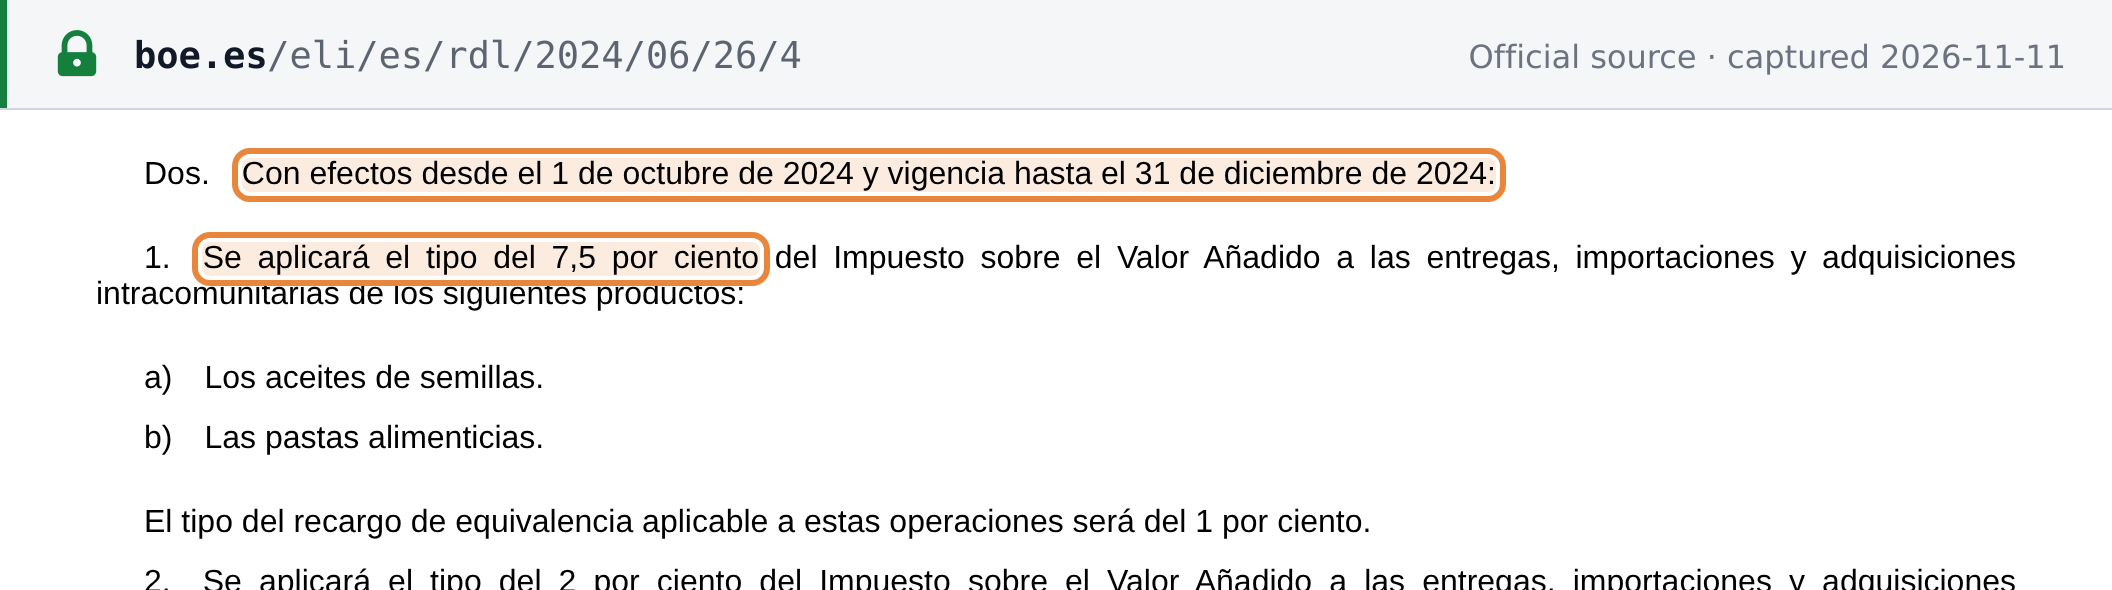 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BOE-A-2024-12944 (Real Decreto-ley 4/2024, BOE no. 155 of 27 June 2024) · www.boe.es