Sweden’s Riksdag adopts the ViDA step 2 VAT Act amendments on OSS, IOSS and platforms, effective 1 January 2027
This page records one dated change. For the rules in Sweden as they stand today, see the Sweden guide →
- Jurisdiction
- Sweden
- Tax
- VAT
- Change type
- Registration
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 11 November 2026
- Effective
- 1 January 2027
- Authority
- Sveriges riksdag (riksdagen.se)
- Systems
- Reporting, Tax engine
- Verified
- Fetched from official source · high confidence
Businesses using the Swedish non-Union, Union or import OSS schemes, operators of electronic interfaces facilitating supplies of goods within the EU, and suppliers of gas, electricity, heating and cooling to consumers in other Member States.
Businesses using the OSS/IOSS special schemes in Sweden and marketplace operators: review the amended reporting rules ahead of 1 January 2027.
ReportingTax engine
Sweden's Riksdag decided on 11 November 2026 to adopt the Government's proposal (Proposition 2025/26:278, committee report 2026/27:SkU2) amending the VAT Act (mervärdesskattelagen 2023:200) for the second step of the EU ViDA package: a technical review of VAT rules for cross-border trade covering the special schemes (OSS/IOSS) and the reporting of output tax within them, including for taxable persons facilitating supplies through electronic interfaces. The amendments take effect on 1 January 2027.
What changed in detail
On 11 November 2026 the Riksdag adopted the Government’s bill Proposition 2025/26:278, “Teknisk översyn av mervärdesskattereglerna vid gränsöverskridande handel” (technical review of VAT rules for cross-border trade), on the recommendation of the Committee on Taxation in report 2026/27:SkU2 of 3 November 2026. The committee backed the bill with only editorial changes, and no motions had been tabled against it. The amendments to the VAT Act (mervärdesskattelagen 2023:200) take effect on 1 January 2027; publication in the Swedish Code of Statutes (SFS) is pending.
The amendments implement the second step of Council Directive (EU) 2025/516 (VAT in the Digital Age), which Member States must transpose by 31 December 2026 and apply from 1 January 2027. According to the report, they:
- extend the deemed-supplier rule for electronic interfaces facilitating supplies of goods within the EU (5 ch. 6 § ML) to supplies to certain taxable persons and non-taxable legal persons (Article 14a(2) of the Directive);
- limit the threshold rule in 6 ch. 62 § ML (SEK 99,680, the Swedish figure for the EUR 10,000 threshold in Article 59c of the VAT Directive) to intra-EU distance sales dispatched from Sweden, and treat registration for the Union scheme as an opt-out from the threshold;
- set specific rules for reporting output VAT under the non-Union, Union and import schemes, and where a person is a deemed supplier through an electronic interface;
- allow the non-Union scheme for services to non-EU customers and the Union scheme for certain supplies of gas, electricity, heating and cooling;
- clarify input VAT refunds for non-EU-established persons and bar small-business-scheme users from the import scheme.
What it means
For most OSS users this is a technical update rather than a new obligation, but marketplaces should check the wider deemed-supplier rule: from 1 January 2027 it can apply to sales to some business buyers, not only consumers. Swedish sellers registered for the Union scheme can no longer rely on the EUR 10,000 threshold to charge Swedish VAT on small cross-border volumes. Energy suppliers gain an OSS route. Watch for the SFS number to cite the final text.
Proof
Lagändringarna föreslås träda i kraft den 1 januari 2027.The amendments are proposed to enter into force on 1 January 2027.
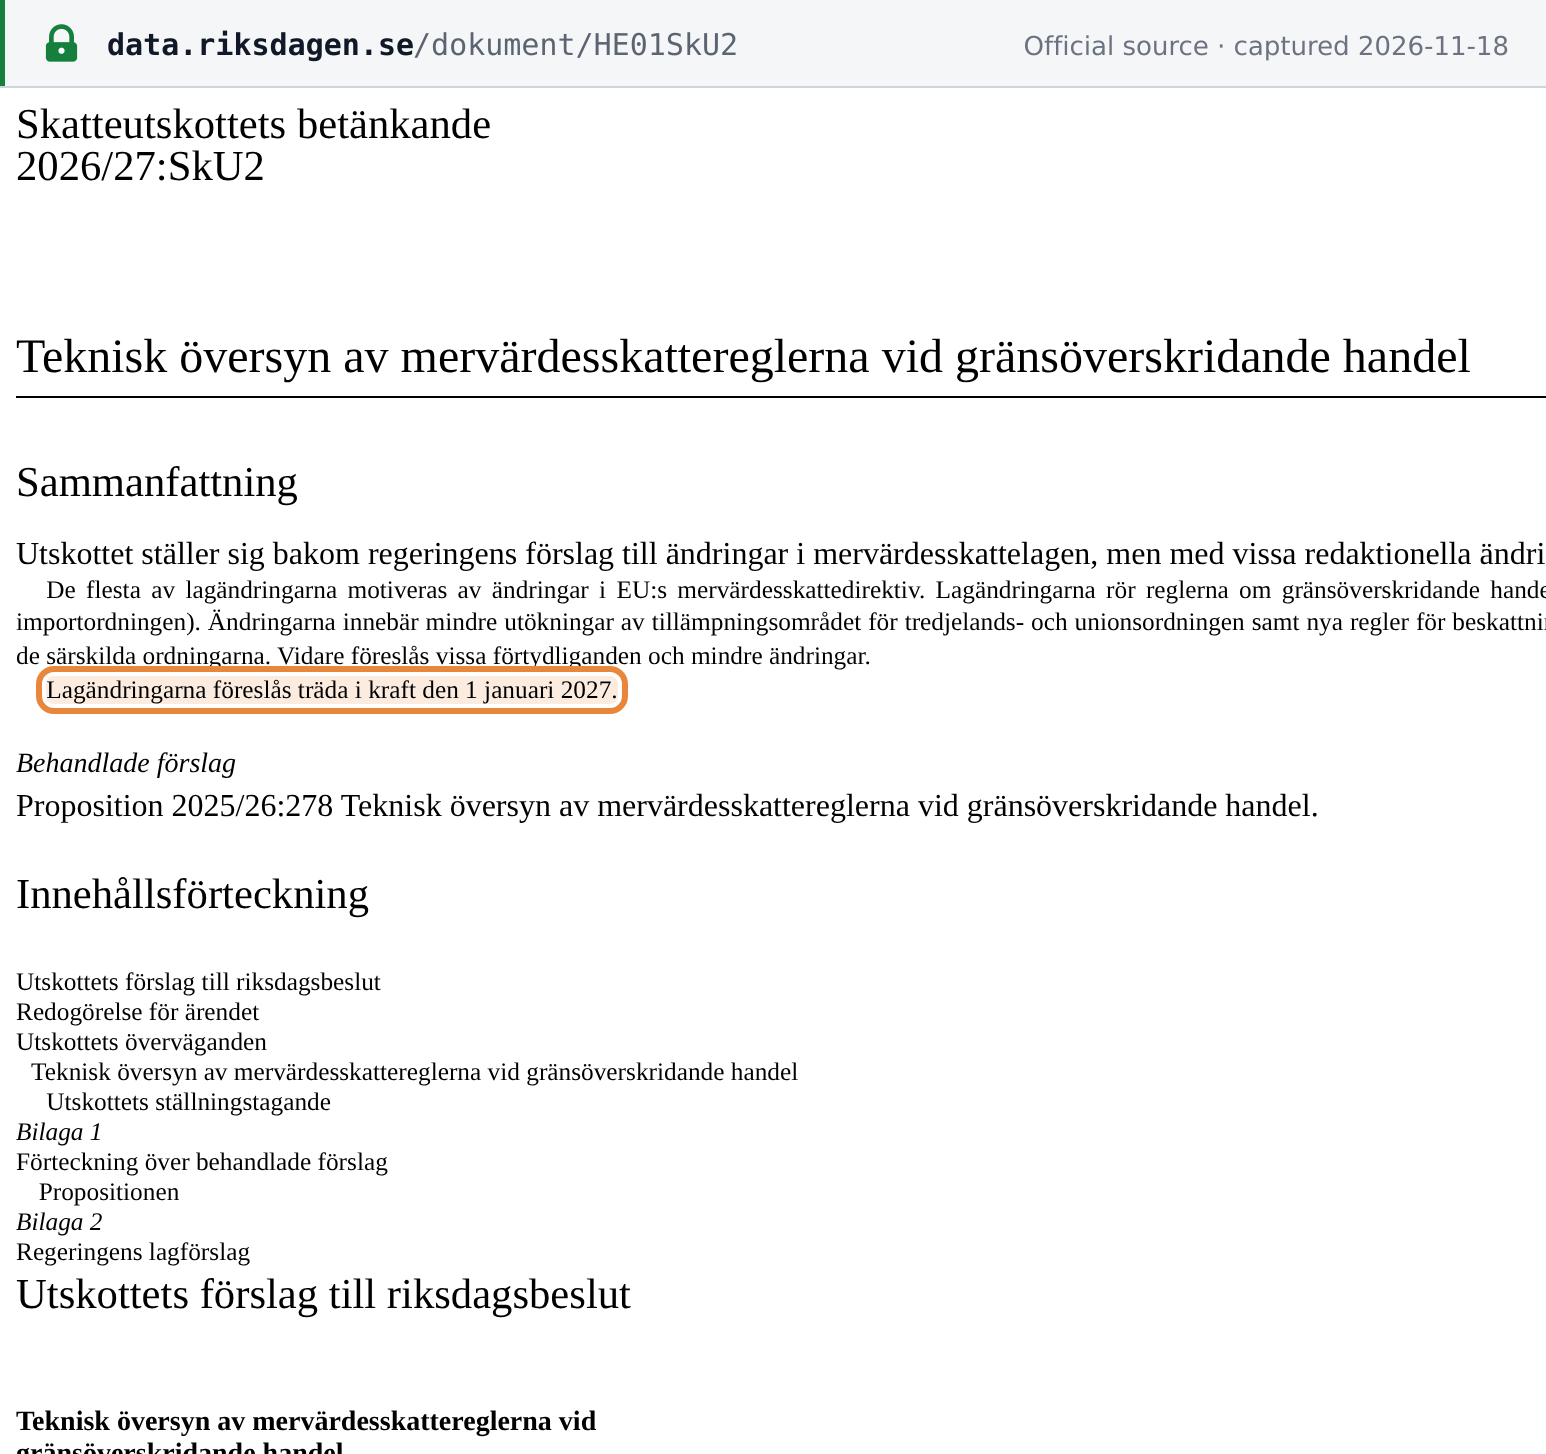 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Sweden proposes ViDA step 2 VAT changes from 1 January 2027 in Proposition 2025/26:278 effective 1 January 2027