Tanzania deems intending traders deregistered for VAT if they miss a 90-day notice after failing registration conditions
This page records one dated change. For the rules in Tanzania as they stand today, see the Tanzania guide →
- Jurisdiction
- Tanzania
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 30 June 2024
- Effective
- 1 July 2024
- Authority
- Parliament of the United Republic of Tanzania (Bunge)
- Verified
- Fetched from official source · high confidence
Persons registered for VAT in Mainland Tanzania under section 29(3) as intending traders, before making taxable supplies, who do not meet the conditions of that registration within the required period.
No action — monitoring only.
Tanzania Finance Act 2024 (Act No. 6 of 2024, effective 1 July 2024) added subsections (4) and (5) to section 29 of the VAT Act (CAP 148). A person registered under s.29(3) who does not comply with its conditions must notify the Commissioner General, with reasons, within 90 days after the end of the s.29(3)(c) period. A person who fails to notify is deemed deregistered for VAT. Finance Act 2025 (s.126) later inserted further subsections and renumbered this provision as s.29(7).
What changed in detail
Section 29(3) of Tanzania’s Value Added Tax Act (Cap. 148) lets a person register for VAT before making taxable supplies, subject to conditions that include a period, set by paragraph (c), within which the person must meet them.
Section 105 of the Finance Act, 2024 (Act No. 6 of 2024) adds two subsections after section 29(3):
- Subsection (4): a person who does not comply with the conditions under subsection (3) must notify the Commissioner General within 90 days after the end of the period required under subsection (3)(c), giving reasons for the failure.
- Subsection (5): a person who contravenes subsection (4) is deemed to be deregistered for VAT.
The Act was assented to on 30 June 2024 and came into operation on 1 July 2024. The amendment does not itself say anything about the treatment of input tax already claimed by a person who is deemed deregistered.
What it means
The rule is still in force but was built on in 2025. Section 126 of the Finance Act 2025 (Act No. 11 of 2025) inserted new subsections (5) and (6): on receiving the notification, the Commissioner General must serve a decision granting or refusing an extension of time, and a refusal also means the person is deemed deregistered. The 2024 deemed-deregistration subsection was renumbered (7). The Finance Act 2026 does not amend section 29.
So an intending trader who has not met the conditions now has two ways to lose registration: by staying silent past the 90 days, or by asking for more time and being refused. Silence is the worse option, since only notification opens the door to an extension.
Proof
A person who does not comply with conditions under subsection (3) shall notify the Commissioner General within a period of 90 days after the end of the period required under sub-section 3(c), by giving reasons for failure to comply with the conditions.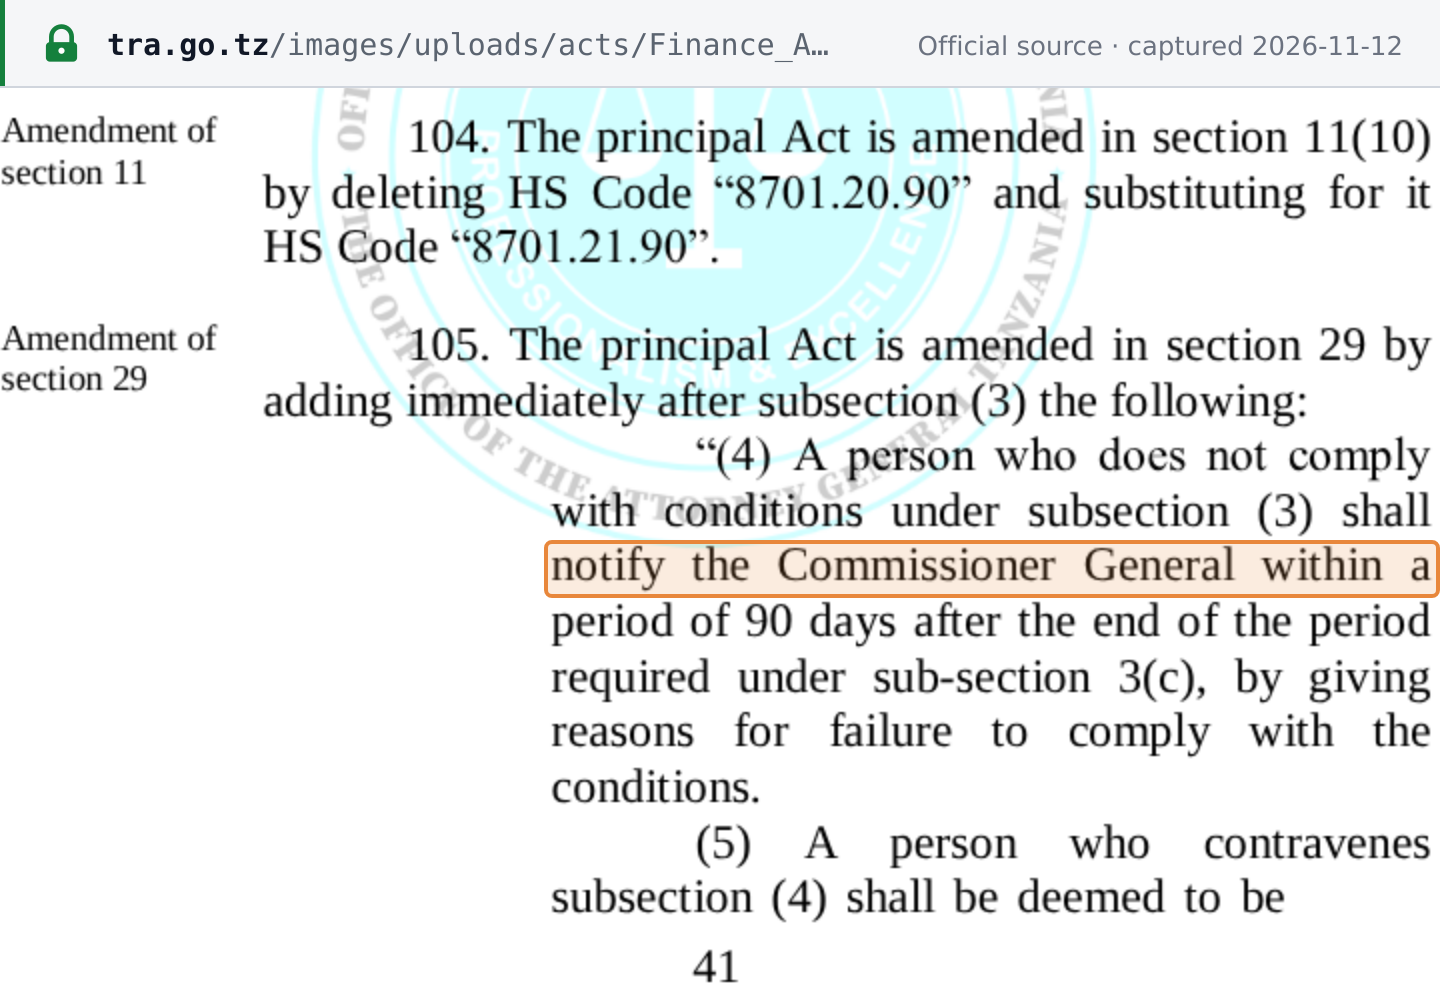 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · The Finance Act, 2024 (Act No. 6 of 2024), Act Supplement to the Special Gazette No. 27 Vol. 105 of 30 June 2024 · tra.go.tz