Tanzania introduces VAT withholding: agents keep 3 points on goods and 6 points on services from 1 July 2025
This page records one dated change. For the rules in Tanzania as they stand today, see the Tanzania guide →
- Jurisdiction
- Tanzania
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 30 June 2025
- Effective
- 1 July 2025
- Authority
- Parliament of the United Republic of Tanzania (Bunge)
- Verified
- Fetched from official source · high confidence
VAT-registered suppliers in Mainland Tanzania selling standard-rated goods or services to the Ministry of Finance, to Government entities that retain their collected revenue, or to registered persons appointed as withholding agents by the Commissioner General; and those agents.
No action — monitoring only.
Tanzania Finance Act 2025 (Act No. 11 of 2025, assented 30 June 2025, effective 1 July 2025) introduced VAT withholding (new s.5(5) VAT Act). On standard-rated supplies to a withholding agent the rate stays 18%, but the agent withholds 3 percentage points on goods and 6 percentage points on services, so the supplier accounts at 15% and 12% respectively. Withholding agents are the Ministry responsible for finance, Government entities that retain their collected revenue, and registered persons appointed by Commissioner General notice. Agents remit the withheld tax when the VAT return is due (s.71(5)). A supplier may subtract withheld output tax only if it holds a valid system-generated VAT withholding certificate (ss.70(2), 90B).
What changed in detail
The Finance Act, 2025 (Act No. 11 of 2025), assented to on 30 June 2025 and in force from 1 July 2025, introduced VAT withholding into Tanzania’s Value Added Tax Act (Cap. 148).
- Who withholds (s.2): a “withholding agent” is the Ministry responsible for finance, a Government entity that retains all or part of its collected revenue, and any registered person the Commissioner General appoints by notice.
- How much (new s.5(5)): on a standard-rated supply made in Mainland Tanzania to a withholding agent, the rate stays 18%, but the agent withholds three percentage points on a supply of goods and six on a supply of services. The Act states that the rate payable to the supplier of a service is therefore 12%; on goods the supplier’s share is the remaining 15 points.
- Certificate (new s.90B): the agent must issue a system-generated VAT withholding certificate by the time VAT becomes payable. A supplier may subtract withheld output tax in its return only if it holds a valid certificate when it files (new s.70(2)).
- Remittance (new s.71(5)): the agent accounts for and remits the withheld tax when its VAT return is due, or as the Commissioner General directs.
What it means
The mechanism is still in force but was tightened by the Finance Act 2026 (Act No. 2 of 2026). Section 91 of that Act wrote the supplier’s 15% share on goods into s.5(5) and added s.5(7), splitting a mixed supply 3:2 between goods and services. Section 95 replaced s.71(5): agents must now pay the withheld VAT within ten days after the end of each tax period and file a monthly withholding statement. See the 2026 withholding-agent filing change and the correction on the 15% and 12% figures.
The 15% and 12% figures are what the supplier collects, not what is withheld. Suppliers to government should reconcile certificates monthly: an output-tax credit claimed without a valid certificate is disallowed.
Proof
the rate shall be eighteen percent but the withholding agent shall be required to withhold the rate of three percent on supply of goods and the rate of six percent in respect of supply of service in which the rate payable to a taxable person supplying service shall be twelve percent.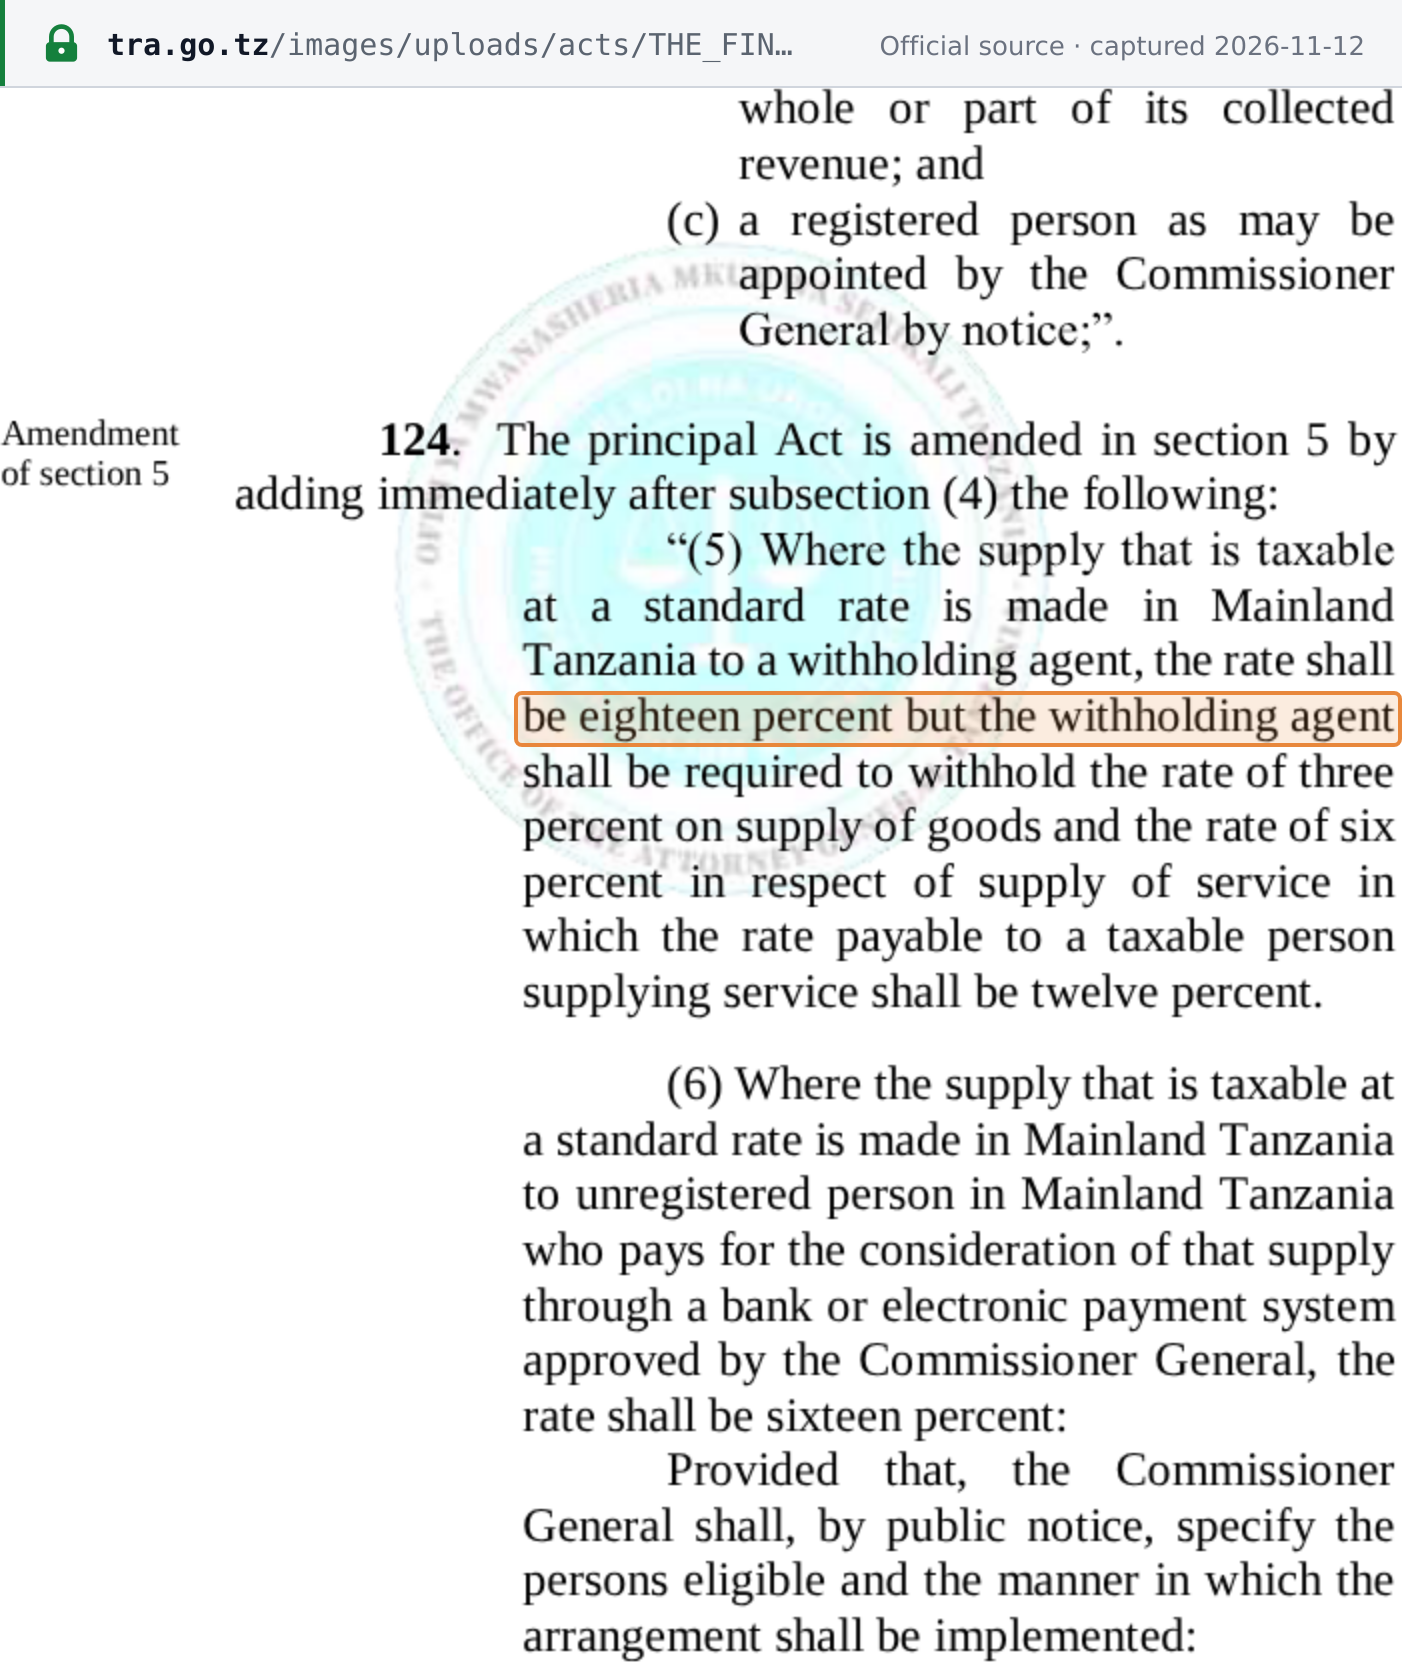 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · The Finance Act, 2025 (Act No. 11 of 2025), Act Supplement to the Special Gazette No. 6 Vol. 106 of 30 June 2025 · www.tra.go.tz