UK raises VAT late-payment penalties to 3% (first penalty) and 10% a year (second penalty) from 31 May 2025
This page records one dated change. For the rules in United Kingdom as they stand today, see the United Kingdom guide →
- Jurisdiction
- United Kingdom
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Plan ahead
- Announced
- 13 May 2025
- Effective
- 31 May 2025
- Instrument
- GB-STATUTORY-INSTRUMENT-SI-2025-589
- Authority
- The National Archives (legislation.gov.uk) / HM Treasury
- Verified
- Fetched from official source · high confidence
All UK VAT-registered businesses that pay VAT late for accounting periods beginning on or after 1 April 2025.
Ensure VAT is paid by its due date to avoid the increased late-payment penalty rates (3% first penalty, 10% per annum second penalty) which apply to VAT accounting periods beginning on or after 1 April 2025.
The Finance Act 2021 (Increase in Schedule 26 Penalty Percentages) Regulations 2025 (SI 2025/589), made 13 May 2025 and in force 31 May 2025, raise the Schedule 26 FA2021 late-payment penalty rates for VAT: the first penalty increases from 2% to 3% (applied where tax remains due after 15 days), and the second penalty increases from 4% to 10% per annum (applied where tax remains due after 30 days). The higher rates apply to VAT accounting periods beginning on or after 1 April 2025.
What changed in detail
The Finance Act 2021 (Increase in Schedule 26 Penalty Percentages) Regulations 2025 (SI 2025/589) were made on 13 May 2025, after a draft was approved by the House of Commons, and came into force on 31 May 2025. Regulation 2 amends Schedule 26 to the Finance Act 2021, the late-payment penalty regime that has applied to VAT since 1 January 2023.
- First penalty (paragraph 5). Where tax is still unpaid 15 days after it fell due, the penalty rises from 2% to 3% of the tax unpaid at day 15. If the tax is still unpaid at day 30 with no time-to-pay agreement, a further 3% (previously 2%) of the amount unpaid at day 30 is added.
- Second penalty (paragraph 8). On tax still unpaid after day 30, the daily-accruing penalty rises from 4% to 10% per annum until the tax is paid.
Under regulation 1(3), the higher rates apply where the specified date is on or after 31 May 2025, but not to VAT payable for a prescribed accounting period that began before 1 April 2025, or to VAT assessed under sections 80(4A) or 80B of the Value Added Tax Act 1994 for such a period. For income tax and capital gains tax, where Schedule 26 applies, the higher rates start with the 2025-26 tax year.
What it means
For a quarterly VAT payer, the first return caught is usually the one for the quarter starting on or after 1 April 2025. A business that pays in full within 15 days, or agrees time to pay within that window, still pays no penalty. Beyond that the cost rises at every stage, and most sharply after day 30, where the annual rate more than doubles. Late-payment interest runs alongside the penalties and is charged separately.
The rates were still in force in November 2026: the current text of Schedule 26 still shows 3% and 10%. Section 263 of the Finance Act 2026 amended other paragraphs of Schedule 26 from 1 April 2026, but did not change the penalty percentages. Interest went up at the same time; see the late-payment interest increase from 6 April 2025.
Proof
(3) In paragraph 8 (second penalty: tax remains due at end of 30 day period), in sub-paragraph (3), for “4%” substitute “10%”.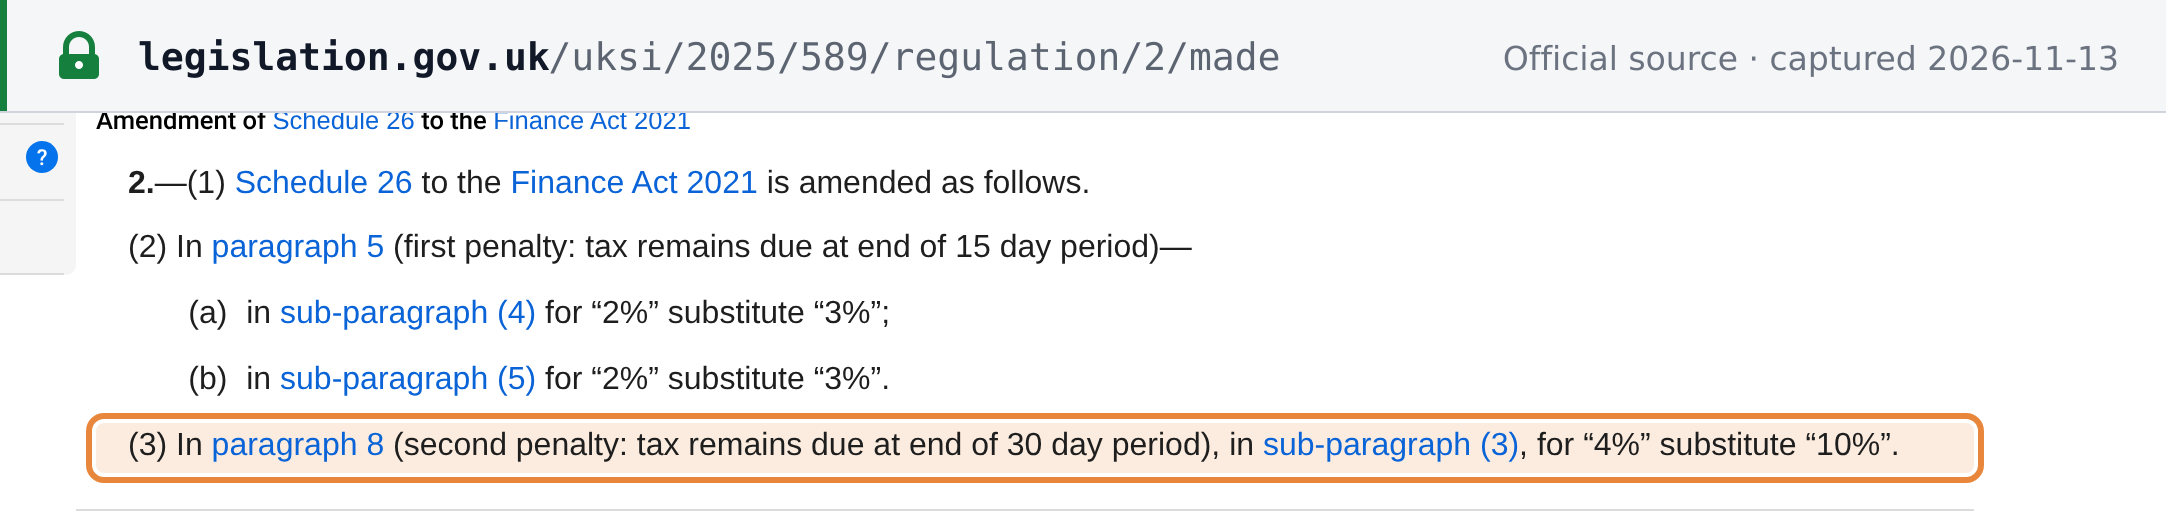 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · S.I. 2025 No. 589, The Finance Act 2021 (Increase in Schedule 26 Penalty Percentages) Regulations 2025, made 13 May 2025, in force 31 May 2025 · www.legislation.gov.uk