Northern Ireland IOSS representatives in force from 31 March 2026
This page records one dated change. For the rules in United Kingdom as they stand today, see the United Kingdom guide →
- Jurisdiction
- United Kingdom
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- FYI
- Announced
- 31 March 2026
- Effective
- 31 March 2026
- Instrument
- GB-STATUTORY-INSTRUMENT-SI-2026-315-C-24
- Authority
- The National Archives (legislation.gov.uk) / HM Treasury
- Verified
- Fetched from official source · high confidence
UK VAT-registered businesses with a Northern Ireland address acting as intermediaries, and non-established sellers of low-value goods imported into Northern Ireland.
No action — monitoring only.
In force from 31 March 2026, the remaining provisions of Finance Act 2021 section 95 and Schedule 18 (Northern Ireland distance selling) allow the Northern Ireland Import One Stop Shop (IOSS) scheme to be used through an IOSS representative. These are Part 5 of Schedule 9ZE to VATA 1994 (IOSS representatives) and the linked registration provisions in paragraphs 4(b)(iii), 5(3)(b) and 7(1). A business registered for UK VAT with a Northern Ireland address can register with HMRC as an IOSS intermediary, then register non-established sellers of low-value imported goods and file and pay their monthly IOSS returns. HMRC opened intermediary registration on 1 April 2026. The provisions were brought into force by the Finance Act 2021, Section 95 and Schedule 18 (Distance Selling: Northern Ireland) (Appointed Day No. 3) Regulations 2026 (SI 2026/315 (C. 24)), made 18 March 2026. The earlier commencement on 1 March 2024 (SI 2024/130) had excluded them.
What changed in detail
In force from 31 March 2026, the last provisions of section 95(1) of and Schedule 18 to the Finance Act 2021 (Northern Ireland distance selling) apply. They were brought into force by the Finance Act 2021, Section 95 and Schedule 18 (Distance Selling: Northern Ireland) (Appointed Day No. 3) Regulations 2026 (SI 2026/315 (C. 24)), made by the Treasury on 18 March 2026. Regulation 2 appoints 31 March 2026 for every part of section 95(1) and Schedule 18 “so far as not already in force”.
The earlier commencement order, SI 2024/130 (Appointed Day No. 2), had brought the rest of Schedule 18 into force on 1 March 2024 but held back:
- Part 5 of Schedule 9ZE to the Value Added Tax Act 1994, which provides for IOSS representatives (intermediaries); and
- the linked registration provisions in paragraphs 4(b)(iii), 5(3)(b) and 7(1) of Schedule 9ZE.
These are what commence. Under HMRC’s guidance, a business registered for UK VAT with a Northern Ireland address can register with HMRC as an IOSS intermediary, then register non-established sellers of low-value goods imported into Northern Ireland for the Import One Stop Shop and file and pay their monthly IOSS returns. HMRC opened intermediary registration on 1 April 2026.
What it means
Until 31 March 2026 the Northern Ireland IOSS could only be used by registering directly, with no intermediary route. Non-established sellers can now join it through a Northern Ireland intermediary, which mirrors how EU IOSS intermediaries work and gives sellers of low-value goods into Northern Ireland a practical way to collect VAT at the point of sale.
The provisions remain in force in November 2026. They complete the scheme reshaped in 2024, when goods sent from Great Britain or the Isle of Man were taken out of it: see the 1 March 2024 qualifying-supplies change.
Proof
The day appointed for the coming into force of section 95(1) of and Schedule 18 to the Finance Act 2021, so far as not already in force, is 31st March 2026.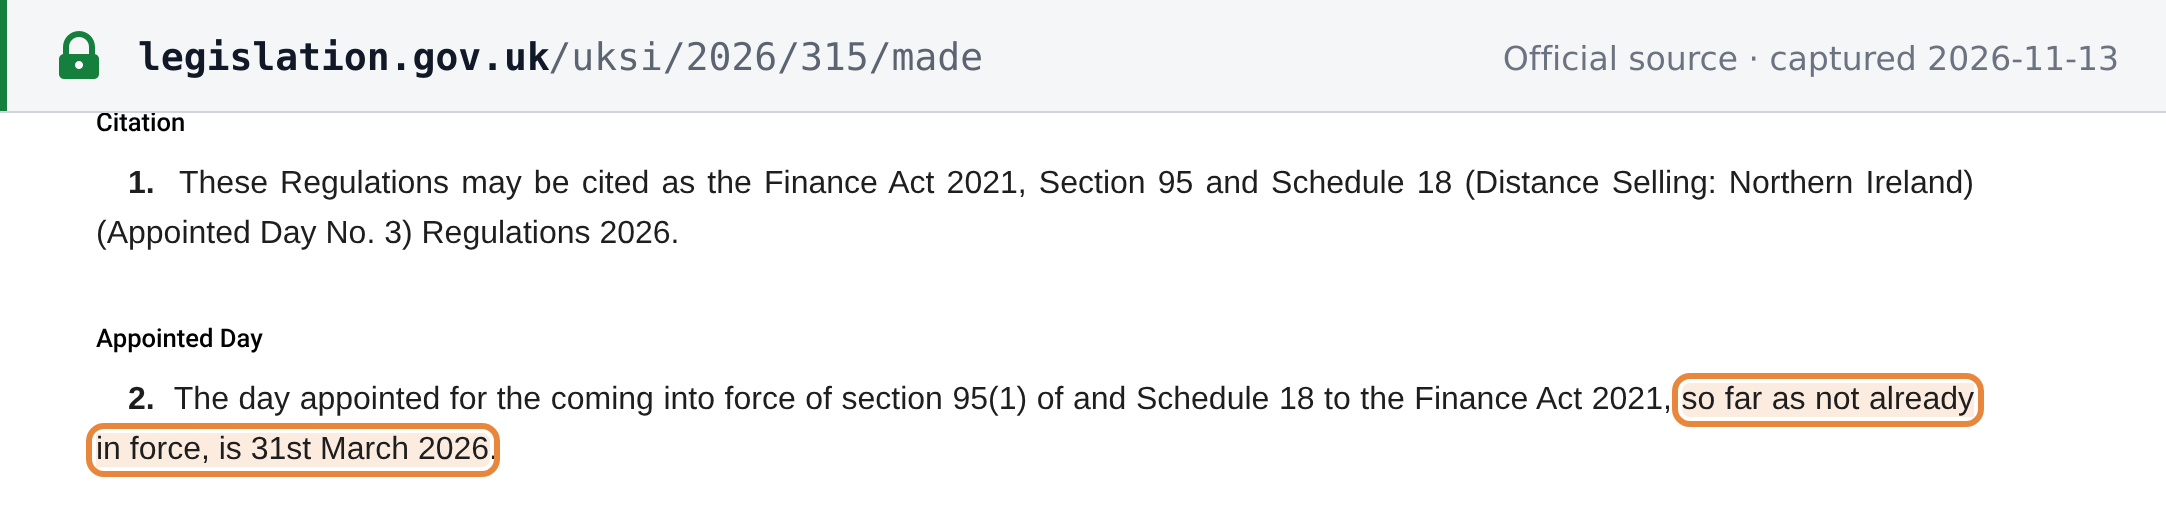 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · S.I. 2026 No. 315 (C. 24), The Finance Act 2021, Section 95 and Schedule 18 (Distance Selling: Northern Ireland) (Appointed Day No. 3) Regulations 2026, made 18 March 2026 · www.legislation.gov.uk
Sources
- The Finance Act 2021, Section 95 and Schedule 18 (Distance Selling: Northern Ireland) (Appointed Day No. 3) Regulations 2026 (SI 2026/315)
- The Finance Act 2021, Section 95 and Schedule 18 (Distance Selling: Northern Ireland) (Appointed Day No. 3) Regulations 2026 (SI 2026/315) (text the quote is taken from)