UK plans to make large private hire operators charge VAT on the full fare from 2 January 2028
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in United Kingdom as they stand today, see the United Kingdom guide →
- Jurisdiction
- United Kingdom
- Tax
- VAT
- Change type
- Update
- Status
- Proposed
- Impact
- Watch
- Announced
- 28 October 2026
- Effective
- 2 January 2028
- Authority
- HM Treasury / HMRC
- Systems
- Tax engine, Invoicing
- Verified
- Fetched from official source · high confidence
Taxi and private hire vehicle operators acting as agents for drivers, with annual fare turnover above a threshold still to be consulted on (£50 million is the lead option).
Large private hire operators: follow the threshold consultation; VAT on full fares from 2 January 2028.
Tax engineInvoicing
The UK government will legislate in Finance Bill 2026-27 so that taxi and private hire passenger transport supplied through an agent is deemed to be supplied by the agent, not the driver, making the operator charge VAT on the full fare. The rule will apply only to businesses with annual fare turnover above a threshold to be consulted on, with £50 million the lead option. The change takes effect from 2 January 2028.
What changed in detail
This is a proposal, not yet law. At Budget 2026 (28 October 2026) the UK government said it will introduce legislation in Finance Bill 2026-27 to change the VAT treatment of passenger transport by taxi or private hire vehicle when supplied through an agent. The service would be deemed to be made by the agent, not the driver, so the private hire vehicle operator would have to charge VAT on the full value of the fare.
The deeming would only apply to businesses whose annual fare turnover exceeds a specified threshold. The government will consult on the level of that threshold, with £50 million annual fare turnover the lead option; the consultation will also inform final policy design and implementation. The government states the change will take effect from 2 January 2028.
What it means
Many drivers trade below the VAT registration threshold, so under an agency model most of the fare carries no VAT. Deeming the operator to be the supplier puts 20% VAT on the whole fare for the largest platforms only, which will push either fares or driver pay. Operators near the £50 million figure should follow the consultation closely, because the threshold, not the deeming rule, decides who is in.
Proof
This means that the private hire vehicle operator will have to charge VAT on the full value of the fare. The deeming will only apply to businesses whose annual fare turnover exceeds a specified threshold.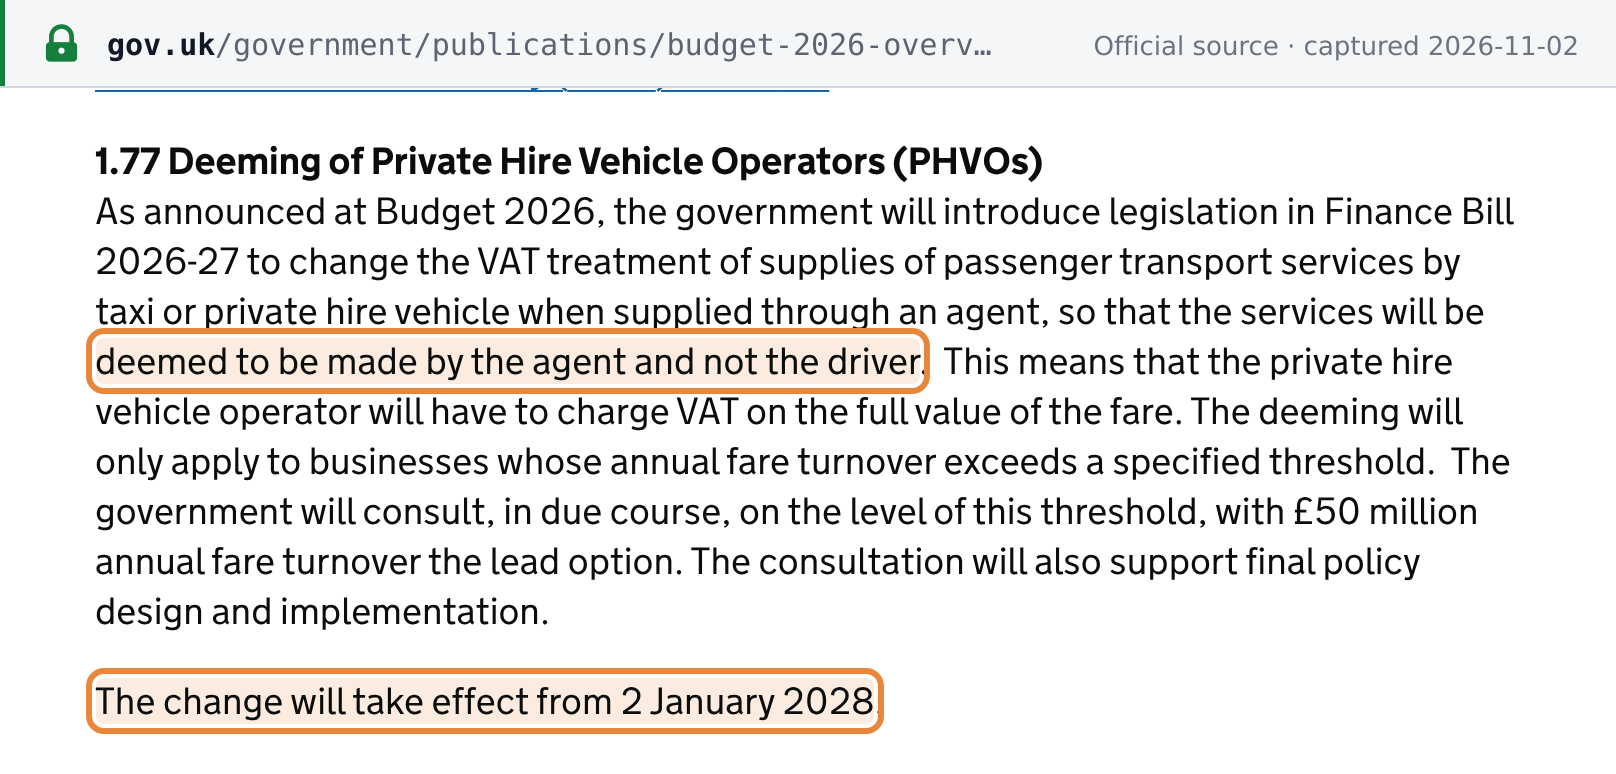 Source snapshot of the official page. Open full size ↗
The change will take effect from 2 January 2028. Source snapshot of the official page. Open full size ↗