Florida repeals its sales tax on commercial rent from 1 October 2025
- Jurisdiction
- United States — Florida
- Tax
- sales-tax
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 30 June 2025
- Effective
- 1 October 2025
- Instrument
- US-ACT-HB-7031
- Authority
- Florida Department of Revenue
- Verified
- Fetched from official source · high confidence
Landlords and licensors of commercial real property in Florida and their tenants. Transient rentals, parking, boat docks and aircraft tie-downs stay taxable under s. 212.03, F.S.
No action — monitoring only.
Florida House Bill 7031 (Chapter 2025-208, Laws of Florida), signed June 30, 2025, repealed the state sales tax on commercial real property rentals under section 212.031, F.S., effective October 1, 2025. No state sales tax or local discretionary surtax applies to commercial rent or license fees for occupancy periods beginning on or after October 1, 2025. Transient rentals, motor vehicle parking, boat dock, and aircraft tie-down charges remain taxable under section 212.03, F.S.
What changed in detail
Florida House Bill 7031 (Chapter 2025-208, Laws of Florida), approved by the Governor on 30 June 2025, repealed section 212.031, F.S. from 1 October 2025 (section 37 of the Act). Section 212.031 was the state sales tax on rent or license fees for the use of commercial real property. The Department of Revenue explained the repeal in Tax Information Publication 25A01-04, issued on 24 July 2025.
- No state sales tax or discretionary sales surtax applies to rent or license fees for rental or occupancy periods beginning on or after 1 October 2025.
- Rent for periods through September 2025 stays taxable at 2% plus surtax, even if it is paid on or after 1 October 2025.
- Rent paid before 1 October 2025 for later periods is not taxable.
- Sales tax under section 212.03, F.S., continues to apply to transient rentals of six months or less, to motor vehicle parking or storage, to boat docking or storage, and to aircraft tie-down or storage.
- Lessors whose accounts cover only commercial rentals must still file returns through the September 2025 reporting period. No new Florida Tax Credit Scholarship Program allocations tied to commercial rentals are issued on or after 1 July 2025.
What it means
The repeal is in force and ends the three-step phase-out. The rate went from 5.5% to 4.5% in December 2023, then to 2.0% in June 2024, and then to nothing.
Two things remain live. Tax and surtax are still due on rent for periods before October 2025, whenever it is paid. And mixed leases need care: vehicle parking, boat dock and aircraft tie-down charges billed alongside untaxed office rent are still taxable under s. 212.03.
Proof
Effective October 1, 2025, the state sales tax imposed on rent or license fees for the use of real property (commercial rentals) under section 212.031, Florida Statutes (F.S.), is repealed. This means no state sales tax or discretionary sales surtax applies to rent or license fees for rental or occupancy periods beginning on or after October 1, 2025.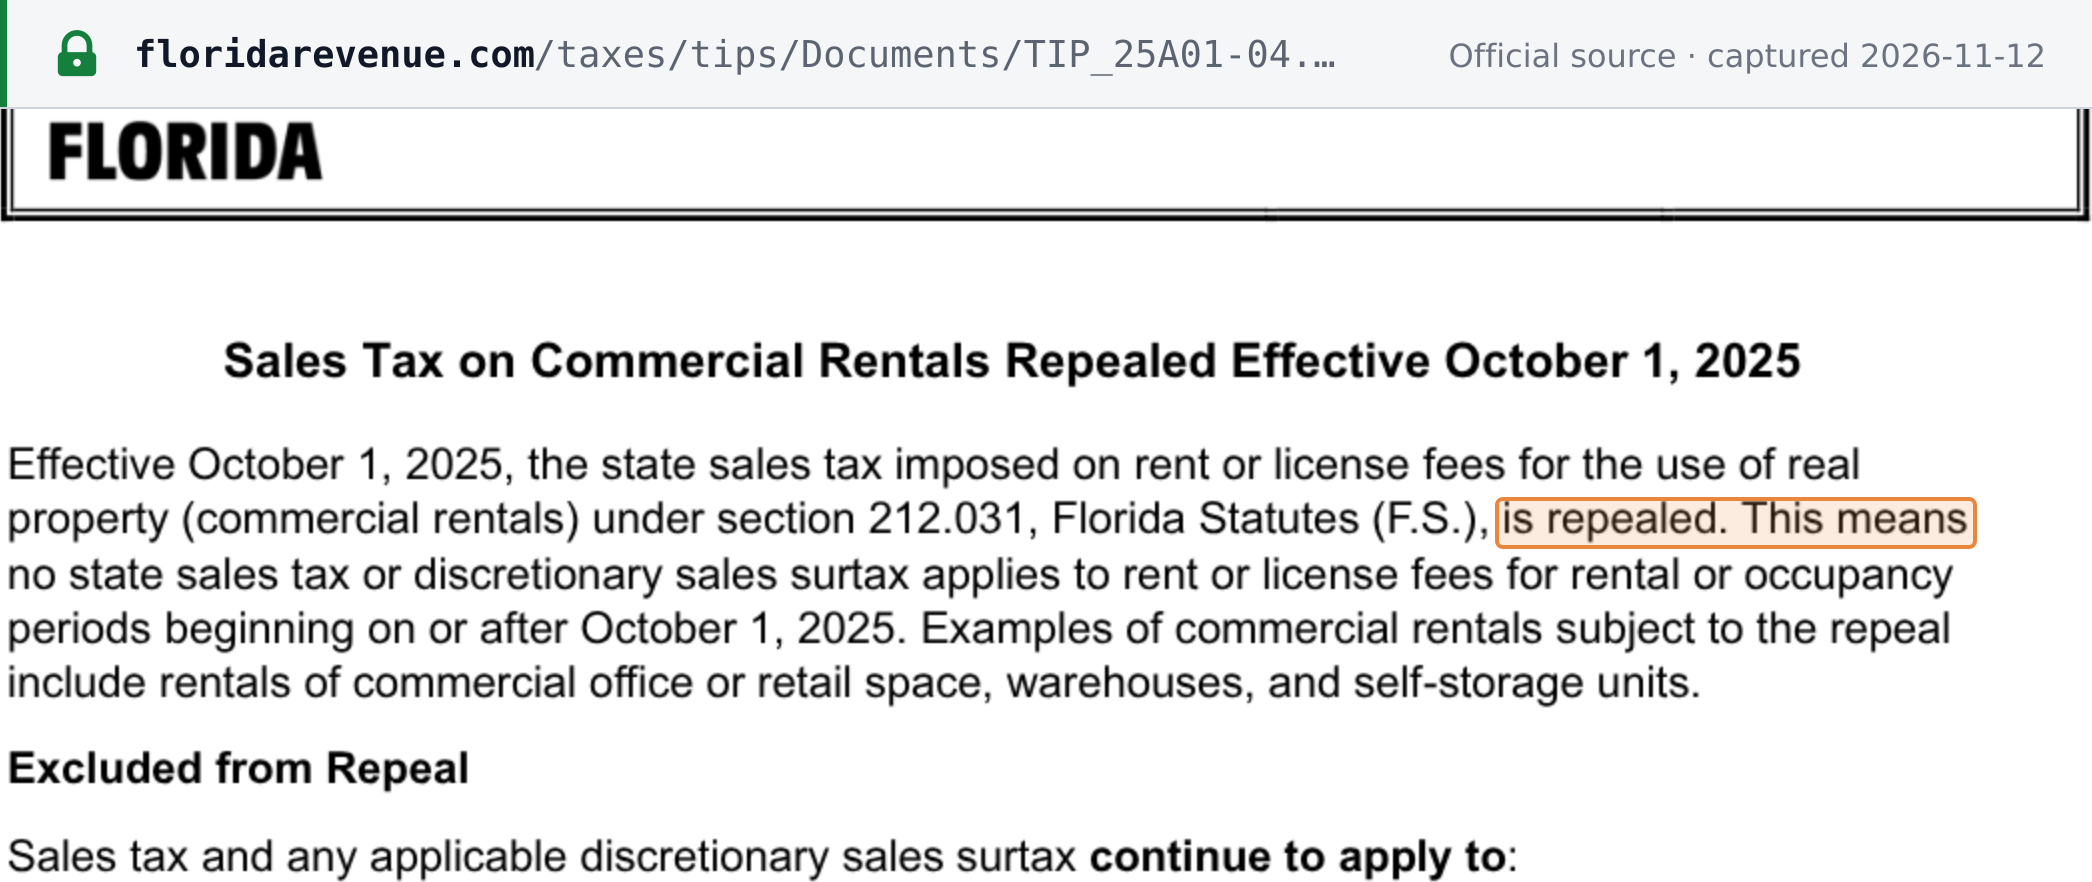 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Florida DOR Tax Information Publication No. 25A01-04, issued July 24, 2025 · floridarevenue.com
Sources
What this replaces
- Florida cuts the state sales tax on commercial rent from 4.5% to 2.0% effective 1 June 2024