Vietnam extends the 8% VAT rate to 31 December 2024 (Decree 72/2024/NĐ-CP)
This page records one dated change. For the rules in Vietnam as they stand today, see the Vietnam guide →
- Jurisdiction
- Vietnam
- Tax
- VAT (GTGT)
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 30 June 2024
- Effective
- 1 July 2024
- Instrument
- VN-DECREE-72-2024-ND-CP
- Authority
- Chính phủ (Government of Vietnam)
- Verified
- Fetched from official source · high confidence
Vietnamese businesses supplying goods and services taxed at 10%, other than telecoms, finance, real estate, metals, mining, excise goods and IT; household businesses on the turnover method.
No action — the H2 2024 reduction period expired 31 December 2024; monitoring only.
Decree 72/2024/ND-CP, signed 30 June 2024, implemented National Assembly Resolution 142/2024/QH15 (passed 29 June 2024) by extending the 2-percentage-point VAT reduction (10% to 8%) for eligible goods and services from 1 July 2024 to 31 December 2024. The scope of eligible goods and services was not expanded relative to Decree 94/2023/ND-CP; the same exclusion lists (Appendices I–III) continued to apply.
What changed in detail
The Government issued Decree No. 72/2024/NĐ-CP on 30 June 2024, signed by Deputy Prime Minister Lê Minh Khái. It implements National Assembly Resolution 142/2024/QH15 of 29 June 2024.
The decree repeats the mechanics of the earlier cut:
- deduction-method businesses apply 8% instead of 10% to qualifying goods and services;
- turnover-method businesses, including household and individual businesses, reduce their VAT percentage on turnover by 20%.
The excluded scope is unchanged: Appendix I (telecoms, financial, banking, securities and insurance services, real estate, metals, mining products (coal mining excepted), coke, refined petroleum and chemical products), Appendix II (goods and services subject to special consumption tax) and Appendix III (information technology). Invoices must show the 8% rate, or note the reduced amount “theo Nghị quyết số 142/2024/QH15” for turnover-method sellers, and reduced supplies are declared on Form 01 of Appendix IV.
Under Article 2(1) the decree applied from 1 July 2024 to 31 December 2024.
What it means
This reduction is spent: it ended on 31 December 2024 by its own terms. It did not replace Decree 94/2023/NĐ-CP, which had already expired on 30 June 2024; it restarted the same cut for the next six months, so 1 July 2024 brought no rate change for qualifying supplies.
The cut was renewed again by Decree 180/2024/NĐ-CP for the first half of 2025, and then by Resolution 204/2025/QH15 to 31 December 2026. Today the decree matters only for checking second-half 2024 invoices and returns.
Proof
Nghị định này có hiệu lực thi hành từ ngày 01 tháng 7 năm 2024 đến hết ngày 31 tháng 12 năm 2024.This Decree takes effect from 1 July 2024 to the end of 31 December 2024.
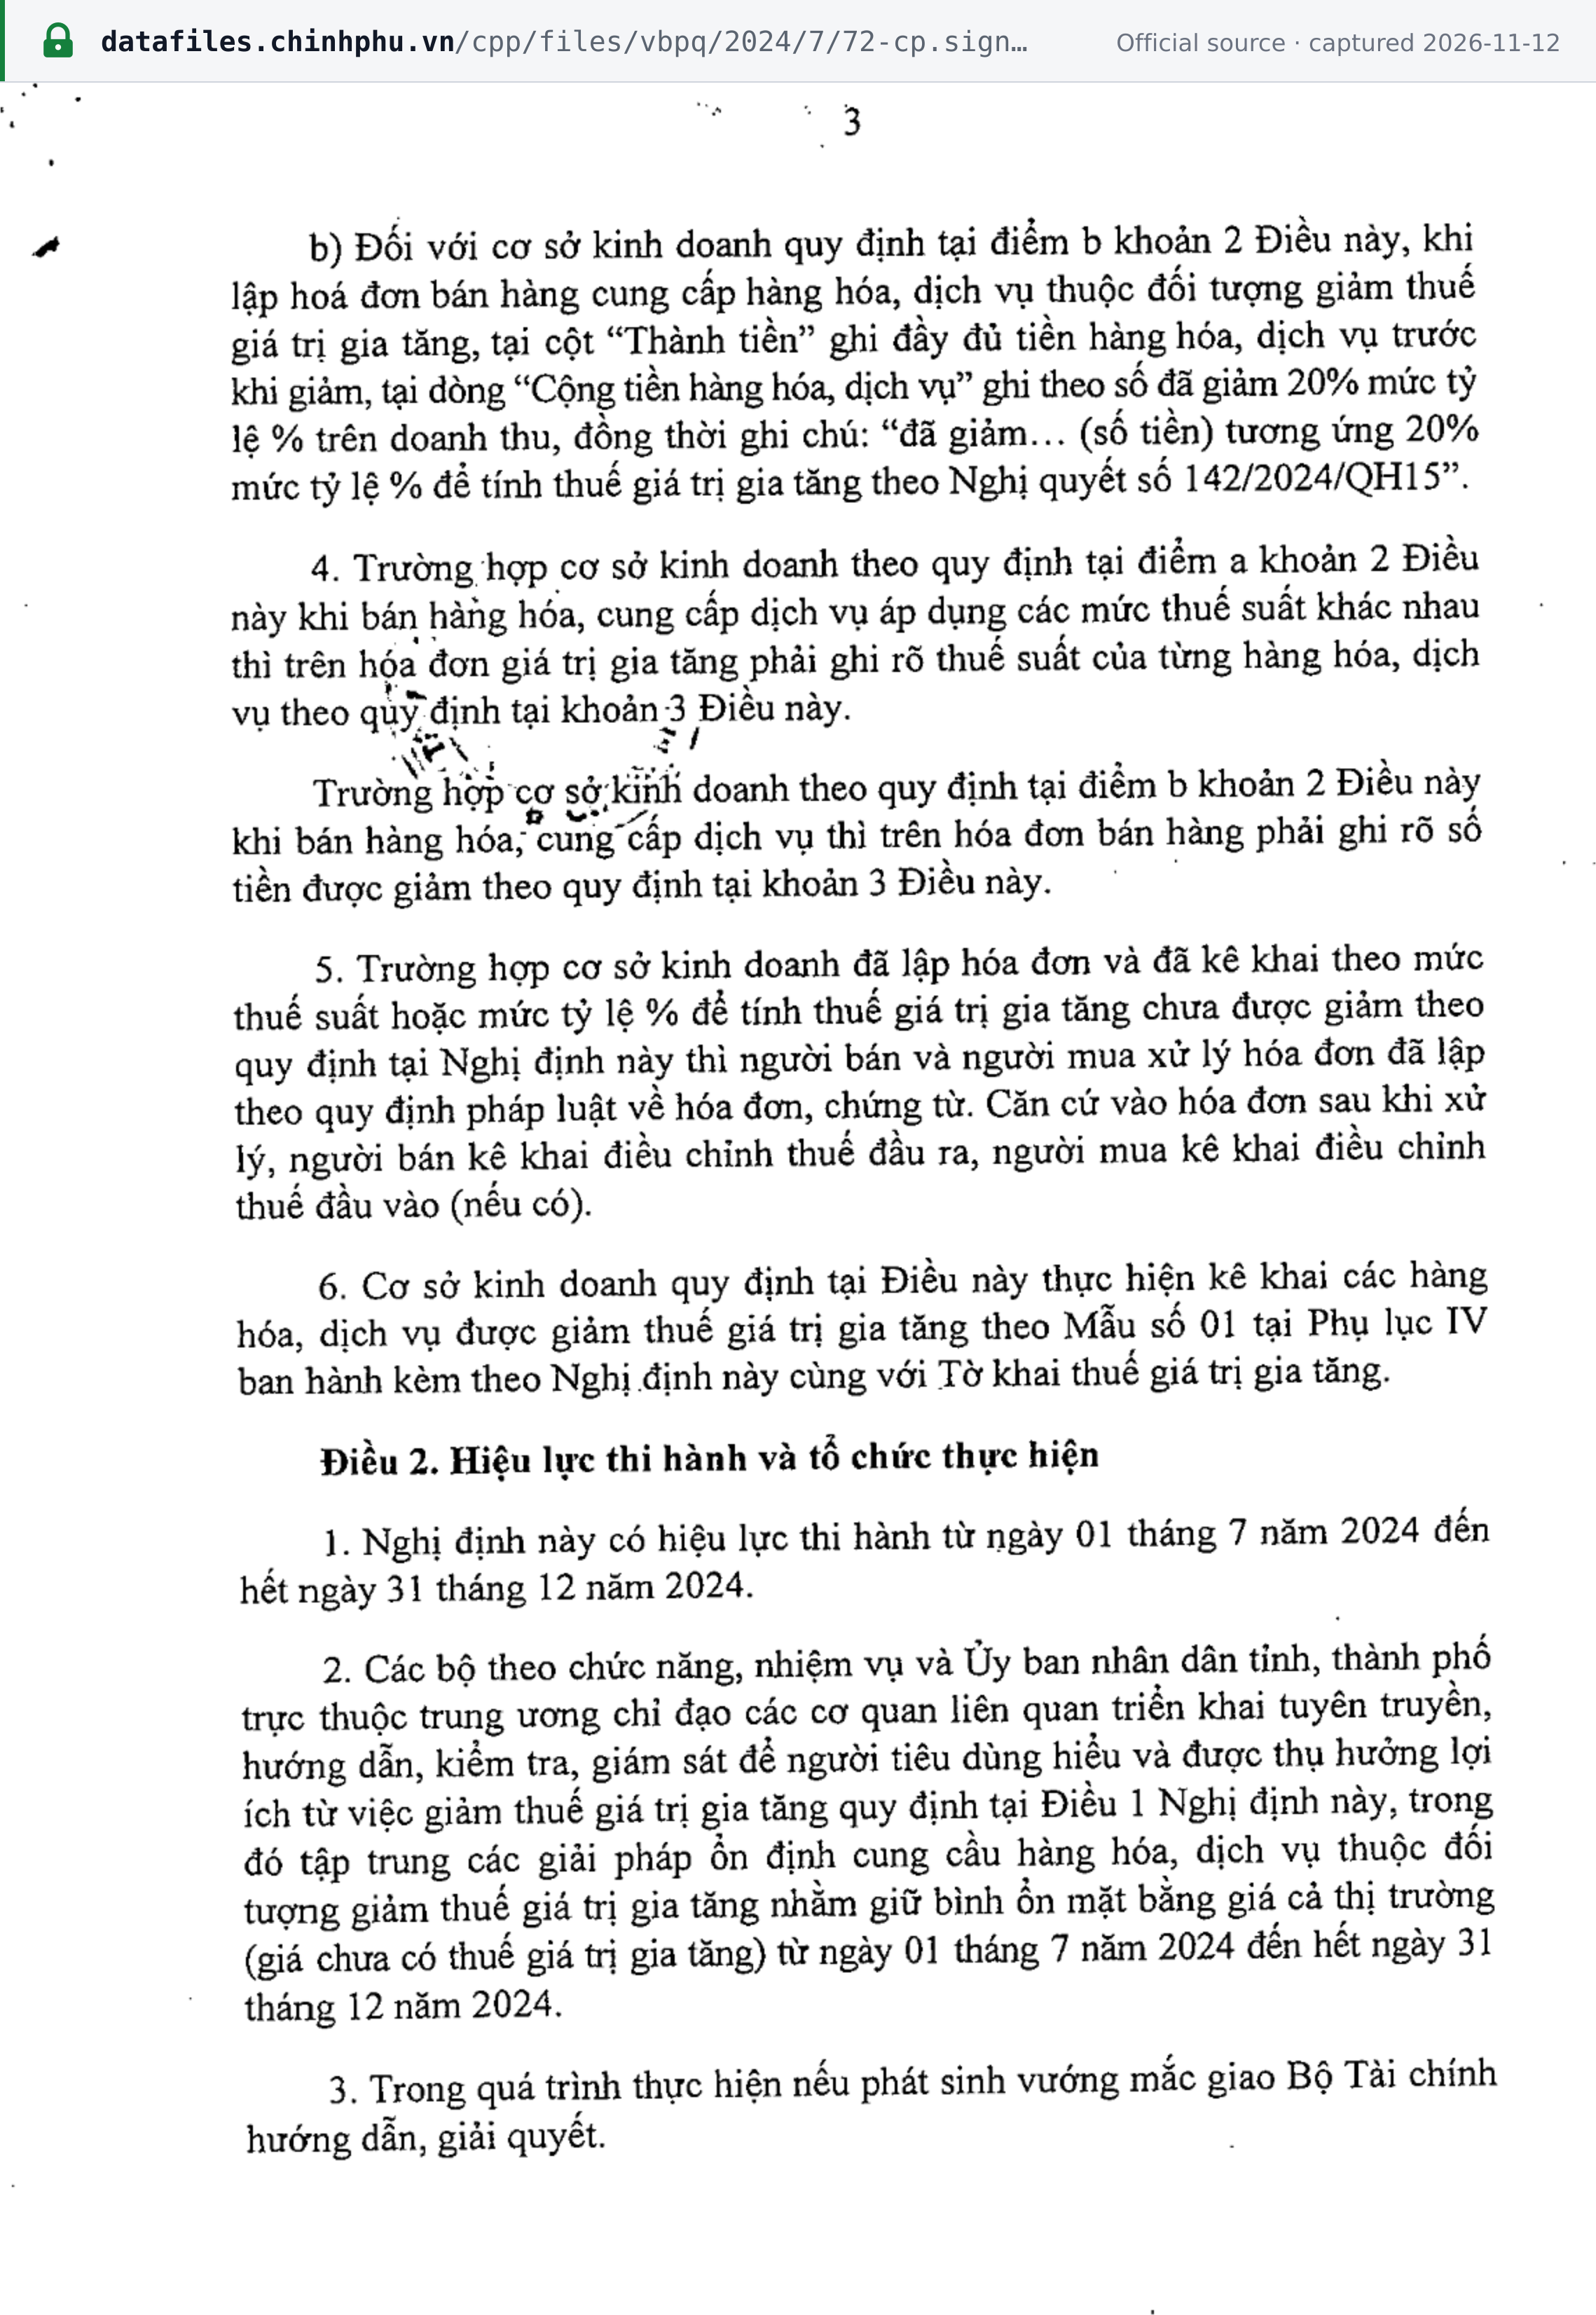 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Nghị định số 72/2024/NĐ-CP ngày 30 tháng 6 năm 2024 (signed copy, Government Electronic Portal) · datafiles.chinhphu.vn