Austria exempts contraceptives and menstrual products from VAT from 1 January 2026
This page records one dated change. For the rules in Austria as they stand today, see the Austria guide →
- Jurisdiction
- Austria
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 30 June 2025
- Effective
- 1 January 2026
- Instrument
- AT-FEDERAL-LAW-BGBl-I-Nr-25-2025
- Authority
- Rechtsinformationssystem des Bundes (RIS)
- Verified
- Fetched from official source · high confidence
Retailers, pharmacies, wholesalers and importers supplying chemical, hormonal or mechanical contraceptives or menstrual-hygiene products in Austria.
Retailers, pharmacies and importers of contraceptives and menstrual-hygiene products should invoice these supplies as VAT-exempt from 1 January 2026 and keep claiming input VAT on related purchases; check till and ERP tax codes no longer apply the 10% rate.
The Budgetbegleitgesetz 2025 (BGBl. I Nr. 25/2025, published 30 June 2025), Article 58, added § 6 Abs. 1 Z 5b to the Umsatzsteuergesetz 1994: from 1 January 2026, supplies of chemical, hormonal and mechanical contraceptives and of monthly feminine-hygiene goods of all kinds (from CN subheadings 3924 90, 4014 90, 0511 99 39 and 9619 00) are VAT-exempt, with the right to deduct input VAT kept. The 10% reduced-rate entry for feminine-hygiene goods (Anlage 1 Z 35) was repealed from the same date. The Abgabenänderungsgesetz 2025 (BGBl. I Nr. 97/2025, Article 4) extended the import exemption in § 6 Abs. 4 Z 1 to these goods from 1 January 2026.
What changed in detail
Article 58 of the Budgetbegleitgesetz 2025, published on 30 June 2025 as BGBl. I Nr. 25/2025, added § 6 Abs. 1 Z 5b to the Umsatzsteuergesetz 1994. Under § 28 Abs. 66 Z 1 it applies to supplies after 31 December 2025, so from 1 January 2026.
The new exemption covers supplies of:
- chemical, hormonal and mechanical contraceptives; and
- monthly feminine-hygiene goods of all kinds,
taken from Combined Nomenclature subheadings 3924 90, 4014 90, 0511 99 39 and 9619 00.
Because § 12 Abs. 3 keeps the input-VAT deduction for exemptions under § 6 Abs. 1 Z 1 to 6, suppliers charge no VAT on these goods and can still deduct the VAT on their own purchases.
The same article repealed Anlage 1 Z 35, the entry that had taxed monthly feminine-hygiene goods at the 10% reduced rate, with effect from the end of 31 December 2025 (§ 28 Abs. 66 Z 3).
The Abgabenänderungsgesetz 2025 (BGBl. I Nr. 97/2025, Article 4) then extended the import exemption in § 6 Abs. 4 Z 1 to the goods in Z 5b, for imports after 31 December 2025 (§ 28 Abs. 67 Z 1).
What it means
The exemption is in force and has not been amended since it started. The 2026 UStG amendments (BGBl. I Nr. 37/2026, 43/2026 and 62/2026) left § 6 Abs. 1 Z 5b unchanged; the new 4.9% rate from BGBl. I Nr. 37/2026 covers staple foods, not these goods.
In effect this is a zero rate: the shelf price no longer carries VAT, and the seller recovers its input VAT. Tills and ERP tax codes need these products moved from the 10% code (menstrual products) or their previous rate (contraceptives) to an exempt-with-deduction code. Products outside the four CN subheadings stay taxable. The same law raised the flat-rate input VAT cap.
Proof
die Lieferungen von chemischen, hormonellen und mechanischen Verhütungsmitteln sowie von Waren der monatlichen Damenhygiene aller Art (aus Unterpositionen 3924 90, 4014 90, 0511 99 39 und 9619 00 der Kombinierten Nomenklatur);(§ 6 Abs. 1 Z 5b) supplies of chemical, hormonal and mechanical contraceptives and of monthly feminine-hygiene goods of all kinds (from subheadings 3924 90, 4014 90, 0511 99 39 and 9619 00 of the Combined Nomenclature);
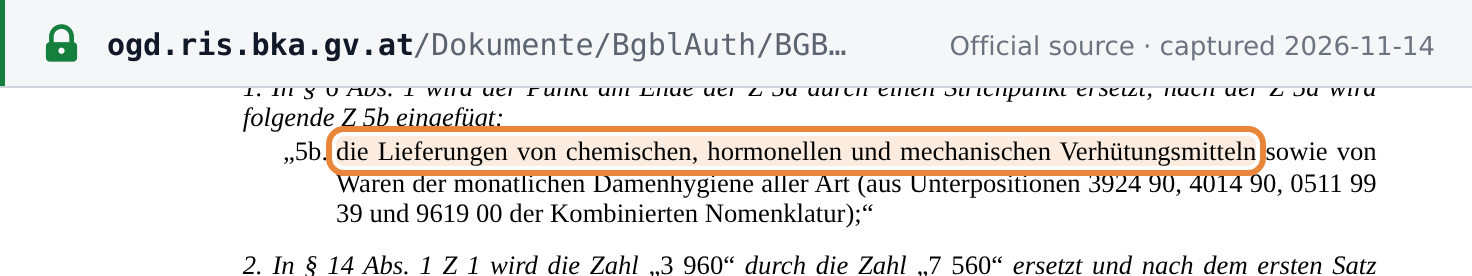 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BGBl. I Nr. 25/2025 (Budgetbegleitgesetz 2025), ausgegeben am 30. Juni 2025, Artikel 58 Z 1 (§ 6 Abs. 1 Z 5b UStG 1994) · ogd.ris.bka.gv.at