Austria exempts food and soft-drink donations to charities from VAT from 1 August 2024
This page records one dated change. For the rules in Austria as they stand today, see the Austria guide →
- Jurisdiction
- Austria
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 19 July 2024
- Effective
- 1 August 2024
- Instrument
- AT-ACT-BGBl-I-Nr-113-2024
- Authority
- Rechtsinformationssystem des Bundes (RIS)
- Verified
- Fetched from official source · high confidence
Food retailers, wholesalers and producers in Austria donating food listed in Annex 1 UStG or non-alcoholic drinks to charitable bodies approved by notice under § 4a EStG.
No action — monitoring only.
Abgabenänderungsgesetz 2024 (BGBl. I Nr. 113/2024, published 19 July 2024) added § 6 Abs. 1 Z 5a UStG 1994. It exempts from VAT donations of food listed in Annex 1 and of non-alcoholic beverages to bodies approved by notice under § 4a EStG for charitable purposes (mildtätige Zwecke). The exemption applies to supplies after 31 July 2024, so in force from 1 August 2024.
What changed in detail
Article 6 of the Abgabenänderungsgesetz 2024, published on 19 July 2024 as BGBl. I Nr. 113/2024, inserted a new § 6 Abs. 1 Z 5a into the Umsatzsteuergesetz 1994.
It exempts from VAT the donation of:
- food listed in Annex 1 of the UStG (the goods otherwise taxed at the reduced rate), and
- non-alcoholic beverages,
to bodies granted favoured status by notice under § 4a Abs. 1 of the Income Tax Act (EStG 1988), where the donation serves the charitable purposes in § 4a Abs. 2 Z 2 EStG (mildtätige Zwecke).
Under § 28 Abs. 64, Z 5a came into force on 1 August 2024 and applies to supplies after 31 July 2024.
The same Act changed the income-tax side in parallel. For food and non-alcoholic drinks exempted under § 6 Abs. 1 Z 5a, the donor deducts the book value at the time of the donation as a business expense, not the market value.
What it means
The exemption is still in force. The current consolidated § 6 UStG (version in force from 1 January 2026, last amended by BGBl. I Nr. 98/2025) carries Z 5a in the same words.
Two conditions are easy to miss. The recipient must hold a § 4a EStG notice for charitable purposes; an unregistered food bank or a general non-profit does not qualify. And the exemption covers only Annex 1 foods and non-alcoholic drinks, so donations of alcohol, hygiene products or household goods still carry VAT.
Proof
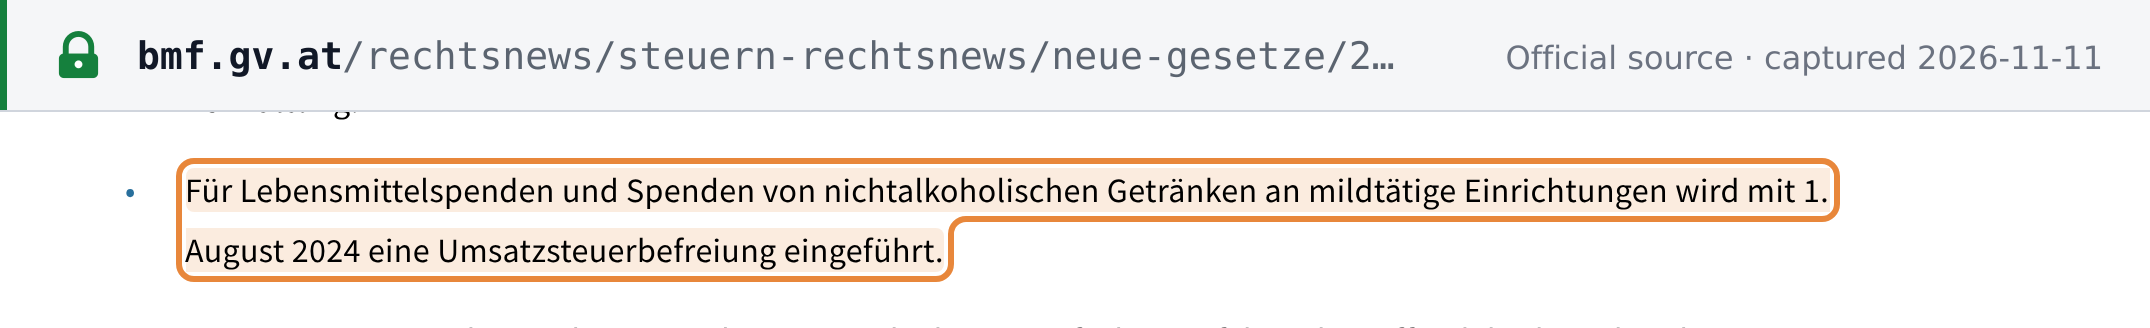
Für Lebensmittelspenden und Spenden von nichtalkoholischen Getränken an mildtätige Einrichtungen wird mit 1. August 2024 eine Umsatzsteuerbefreiung eingeführt.A VAT exemption is introduced from 1 August 2024 for donations of food and of non-alcoholic beverages to charitable institutions.
 Source snapshot of the official page. Open full size ↗
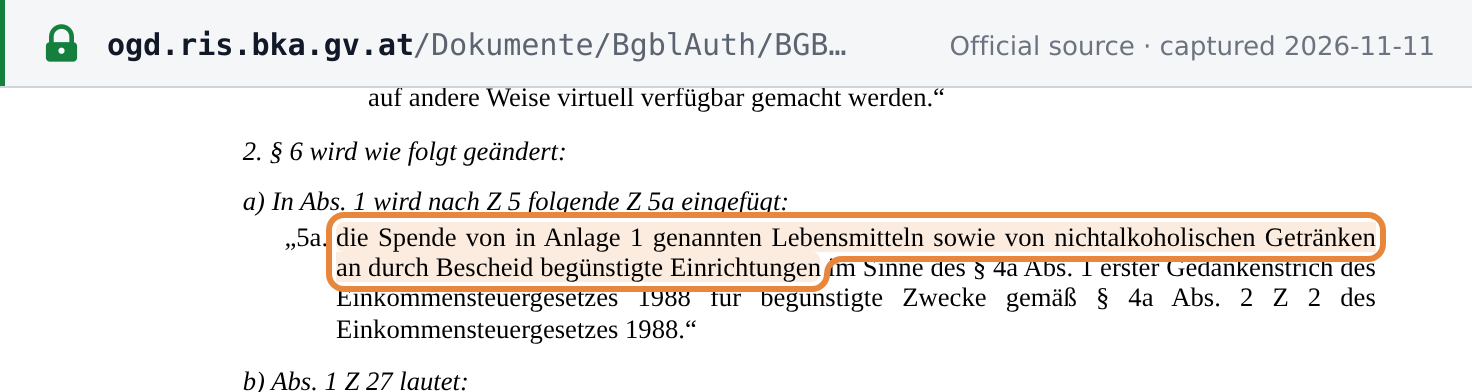
die Spende von in Anlage 1 genannten Lebensmitteln sowie von nichtalkoholischen Getränken an durch Bescheid begünstigte Einrichtungen im Sinne des § 4a Abs. 1 erster Gedankenstrich des Einkommensteuergesetzes 1988 für begünstigte Zwecke gemäß § 4a Abs. 2 Z 2 des Einkommensteuergesetzes 1988.the donation of foodstuffs listed in Annex 1 and of non-alcoholic beverages to bodies granted favoured status by notice within the meaning of § 4a(1), first indent, of the Income Tax Act 1988 for favoured purposes under § 4a(2) no. 2 of the Income Tax Act 1988.
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BGBl. I Nr. 113/2024 (Abgabenänderungsgesetz 2024), ausgegeben am 19. Juli 2024, Artikel 6 Z 2 lit. a (§ 6 Abs. 1 Z 5a UStG 1994) · ogd.ris.bka.gv.at