Austria opens its small-business VAT exemption across the EU from 1 January 2025
This page records one dated change. For the rules in Austria as they stand today, see the Austria guide →
- Jurisdiction
- Austria
- Tax
- VAT
- Change type
- Threshold
- Status
- In force
- Impact
- FYI
- Announced
- 19 July 2024
- Effective
- 1 January 2025
- Instrument
- AT-ACT-BGBl-I-Nr-113-2024
- Authority
- Rechtsinformationssystem des Bundes (RIS)
- Verified
- Fetched from official source · high confidence
Small businesses established in Austria that want the VAT exemption in other Member States, and small businesses from other Member States with EU-wide turnover up to EUR 100,000 that sell in Austria.
No action — monitoring only. The EU SME cross-border exemption scheme has been in force since 1 January 2025.
Abgabenänderungsgesetz 2024 (BGBl. I Nr. 113/2024, published 19 July 2024) transposed the EU SME scheme (Directive (EU) 2020/285) into Austrian VAT law from 1 January 2025. (1) Small businesses established in Austria can claim the VAT exemption in other Member States. (2) Businesses established in another Member State can use the Austrian Kleinunternehmer exemption if they stay under the domestic threshold and under EUR 100,000 EU-wide turnover, and apply through the Art. 6a procedure. (3) The domestic threshold became EUR 42,000 measured gross (not on the deemed taxable base), with a 10% tolerance until the end of the calendar year; the Progressionsabgeltungsgesetz 2025 raised it to EUR 55,000 from the same date. (4) Kleinunternehmer may issue simplified small-amount invoices whatever the invoice amount (previously only up to EUR 400).
What changed in detail
Article 6 of the Abgabenänderungsgesetz 2024, published on 19 July 2024 as BGBl. I Nr. 113/2024, transposed the EU SME scheme (Directive (EU) 2020/285) into the Umsatzsteuergesetz 1994. The changes apply to supplies after 31 December 2024, so from 1 January 2025 (§ 28 Abs. 64).
The rewritten § 6 Abs. 1 Z 27 does four things:
- Austrian small businesses abroad. A small business established in Austria can claim the small-business exemption in other Member States, under those states’ rules.
- EU small businesses in Austria. A business established in another Member State can use the Austrian exemption if it stays within the Austrian limit and its EU-wide annual turnover does not exceed EUR 100,000 in the previous or the current year. It must apply through the procedure in Art. 6a.
- The domestic limit. The limit became EUR 42,000, measured on the actual turnover rather than on a notional taxable base as if VAT were charged. A business that exceeds the limit by no more than 10% keeps the exemption until the end of that calendar year.
- Invoices. § 11 Abs. 6 now lets a business using the exemption issue simplified small-amount invoices whatever the invoice amount. Before, these were allowed only up to EUR 400.
What it means
The cross-border scheme and the gross-measurement rule are still in force. The EUR 42,000 figure never applied in practice: the Progressionsabgeltungsgesetz 2025 raised it to EUR 55,000 before it took effect, also from 1 January 2025. The current consolidated § 6 Abs. 1 Z 27 (version in force from 1 January 2026) reads 55,000 with the same structure.
A small business with customers in several Member States can now stay exempt in each one, provided its EU-wide turnover stays within EUR 100,000.
Proof
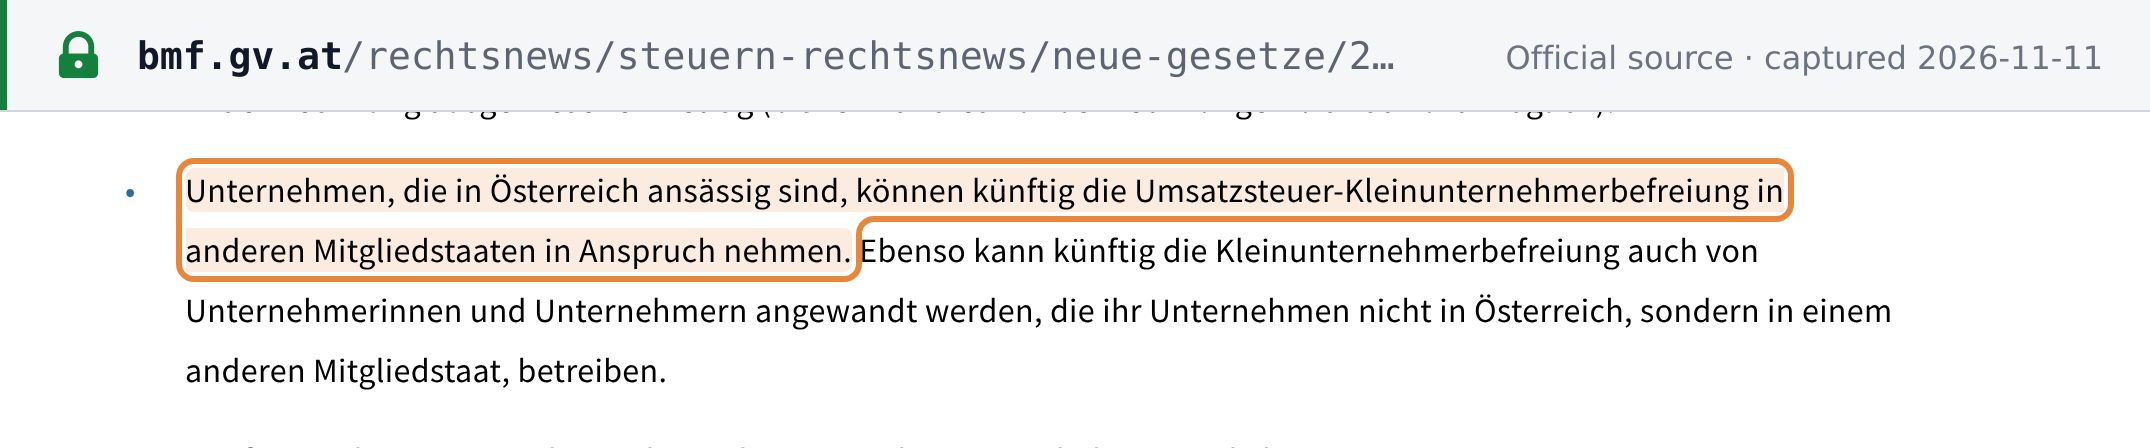
Unternehmen, die in Österreich ansässig sind, können künftig die Umsatzsteuer-Kleinunternehmerbefreiung in anderen Mitgliedstaaten in Anspruch nehmen.Businesses established in Austria will in future be able to claim the VAT small-business exemption in other Member States.
 Source snapshot of the official page. Open full size ↗
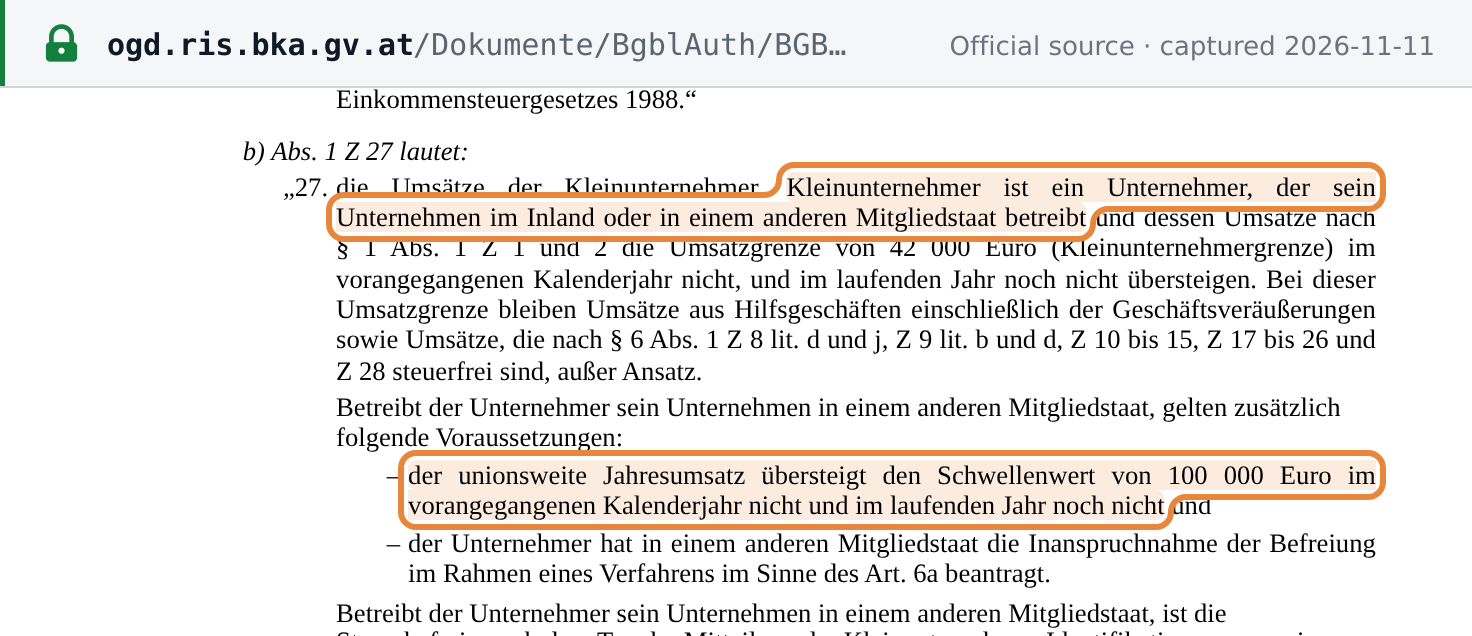
Kleinunternehmer ist ein Unternehmer, der sein Unternehmen im Inland oder in einem anderen Mitgliedstaat betreibt und dessen Umsätze nach § 1 Abs. 1 Z 1 und 2 die Umsatzgrenze von 42 000 Euro (Kleinunternehmergrenze) im vorangegangenen Kalenderjahr nicht, und im laufenden Jahr noch nicht übersteigen.A small business is a business that operates in Austria or in another Member State and whose turnover under § 1(1) nos. 1 and 2 did not exceed the turnover limit of EUR 42,000 (small-business limit) in the previous calendar year and has not yet exceeded it in the current year.
 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BGBl. I Nr. 113/2024 (Abgabenänderungsgesetz 2024), ausgegeben am 19. Juli 2024, Artikel 6 (§ 6 Abs. 1 Z 27 UStG 1994) · ogd.ris.bka.gv.at