Azerbaijan exempts locally made buses and bus spare-part imports from VAT for 8 years from 2025
This page records one dated change. For the rules in Azerbaijan as they stand today, see the Azerbaijan guide →
- Jurisdiction
- Azerbaijan
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 16 December 2024
- Effective
- 1 January 2025
- Instrument
- AZ-ACT-98-VIIQD
- Authority
- Milli Məclis (National Assembly of the Republic of Azerbaijan)
- Verified
- Fetched from official source · high confidence
Bus manufacturers in Azerbaijan and legal entities importing bus spare parts for production; also agricultural-product traders and ship-repair enterprises serving non-residents.
No action — monitoring only.
Law No. 98-VIIQD of 16 December 2024 amending the Tax Code (published on AZERTAC on 27 December 2024; in force 1 January 2025) adds Article 164.1.41-4. It exempts from VAT, for 8 years from 1 January 2025, sales of buses manufactured in Azerbaijan and imports of bus spare parts by legal entities for bus production, on the basis of a confirming document from the authorised body. The same law extends from 3 to 5 years (Article 174.4) the period during which VAT on wholesale and retail sales of agricultural products is charged only on the trade mark-up. It also adds to the zero-rate list (Article 165.1.11) the repair of ships, other water vessels and hydraulic structures by shipbuilding and ship-repair enterprises on a non-resident's order. Law No. 297-VIIQD of 9 December 2025 later extended Article 164.1.41-4 to domestically made trucks and their spare parts (7 years from 1 January 2026).
What changed in detail
Azerbaijan’s Law No. 98-VIIQD of 16 December 2024 amending the Tax Code was published on AZERTAC on 27 December 2024 and, under its Article 3.4, entered into force on 1 January 2025.
Its Article 1.22.3 adds Article 164.1.41-4 to the Tax Code. It exempts from VAT, for 8 years from 1 January 2025:
- sales of buses manufactured in Azerbaijan; and
- imports of bus spare parts by legal entities for production, on the basis of a confirming document from the body designated by the relevant executive authority.
The same law also:
- extends from 3 to 5 years the period in Article 174.4 during which VAT on wholesale and retail sales of agricultural products is charged only on the trade mark-up (Article 1.20, which makes the same “3” to “5” change in Articles 153.3, 159.1 and 175.12);
- adds Article 165.1.11 to the zero-rate list: repair of ships, other water vessels and hydraulic structures by shipbuilding and ship-repair enterprises on a non-resident’s order (Article 1.23.1).
What it means
The bus exemption is in force and, on its own terms, runs to 1 January 2033. It has since been widened rather than cut back: Law No. 297-VIIQD of 9 December 2025 rewrote Article 164.1.41-4 to add domestically made trucks and their spare parts, for 7 years from 1 January 2026.
For spare-part importers the exemption is not automatic. It depends on a confirming document from the designated body, so imports without one are taxed at the border. Bus sales qualify only where the bus is manufactured in Azerbaijan.
Proof
164.1.41-4. Azərbaycan Respublikasının ərazisində istehsal olunan avtobusların satışı, habelə müvafiq icra hakimiyyəti orqanının müəyyən etdiyi orqanın (qurumun) təsdiqedici sənədi əsasında hüquqi şəxslər tərəfindən istehsal məqsədilə avtobusların ehtiyat hissələrinin idxalı – 2025-ci il yanvarın 1-dən 8 il müddətinə;164.1.41-4. sale of buses produced in the territory of the Republic of Azerbaijan, and import by legal entities of bus spare parts for production purposes on the basis of a confirming document of the body (institution) designated by the relevant executive authority – for 8 years from 1 January 2025;
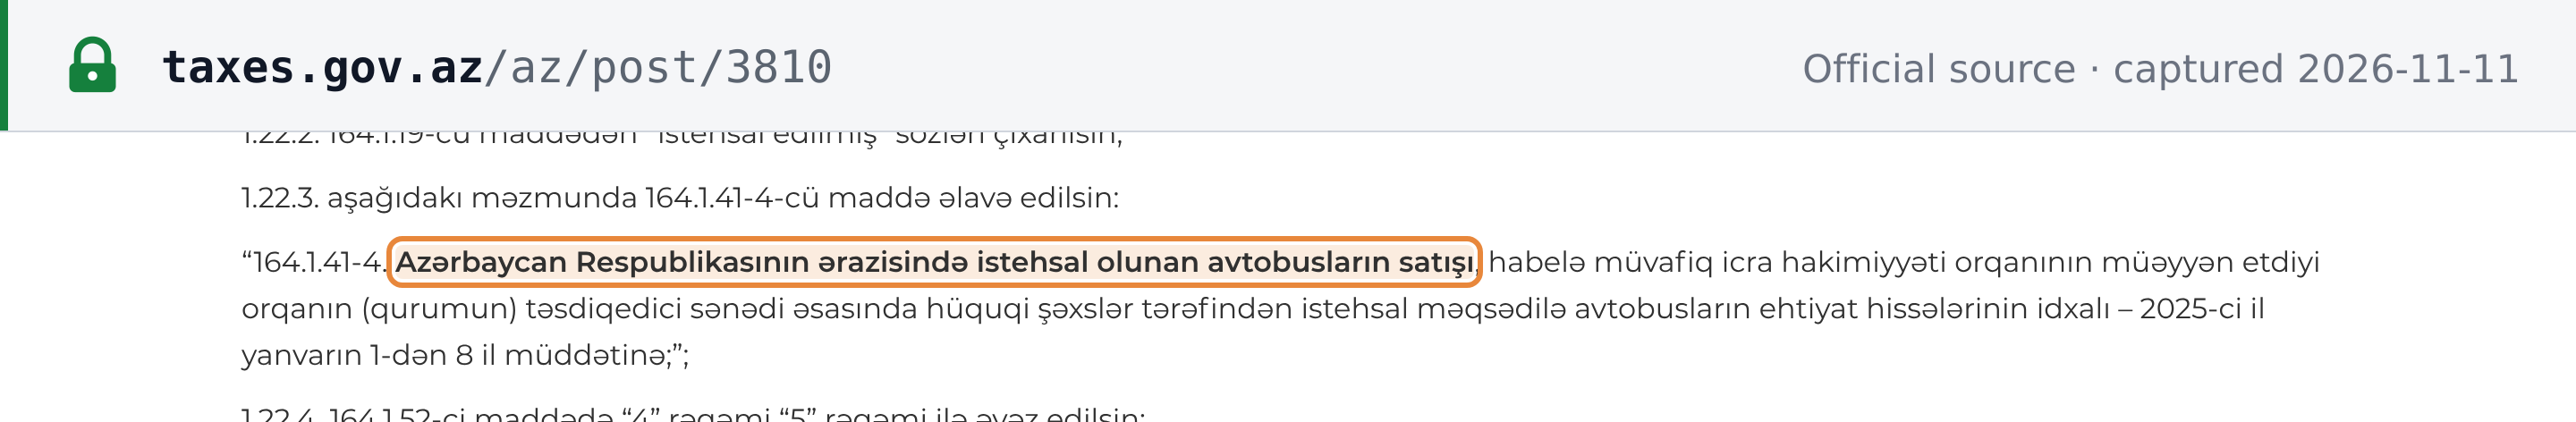 Source snapshot of the official page. Open full size ↗