Azerbaijan extends the VAT exemption for electric-vehicle chargers to 1 January 2027
This page records one dated change. For the rules in Azerbaijan as they stand today, see the Azerbaijan guide →
- Jurisdiction
- Azerbaijan
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 8 October 2024
- Effective
- 15 October 2024
- Instrument
- AZ-ACT-45-VIIQD
- Authority
- Milli Məclis (National Assembly of the Republic of Azerbaijan)
- Verified
- Fetched from official source · high confidence
Importers and sellers in Azerbaijan of second- and third-level electric charging equipment for electric-motor vehicles.
No action — monitoring only. The VAT exemption on second- and third-level EV charger imports and sales now runs until 1 January 2027.
Law No. 45-VIIQD of 8 October 2024 amending the Tax Code (published on AZERTAC on 15 October 2024) replaces '3' with '5' in Article 164.1.41-2. The VAT exemption for imports and sales of second- and third-level chargers for electric vehicles, running from 1 January 2022, now lasts 5 years instead of 3, so it ends on 1 January 2027 instead of 1 January 2025.
What changed in detail
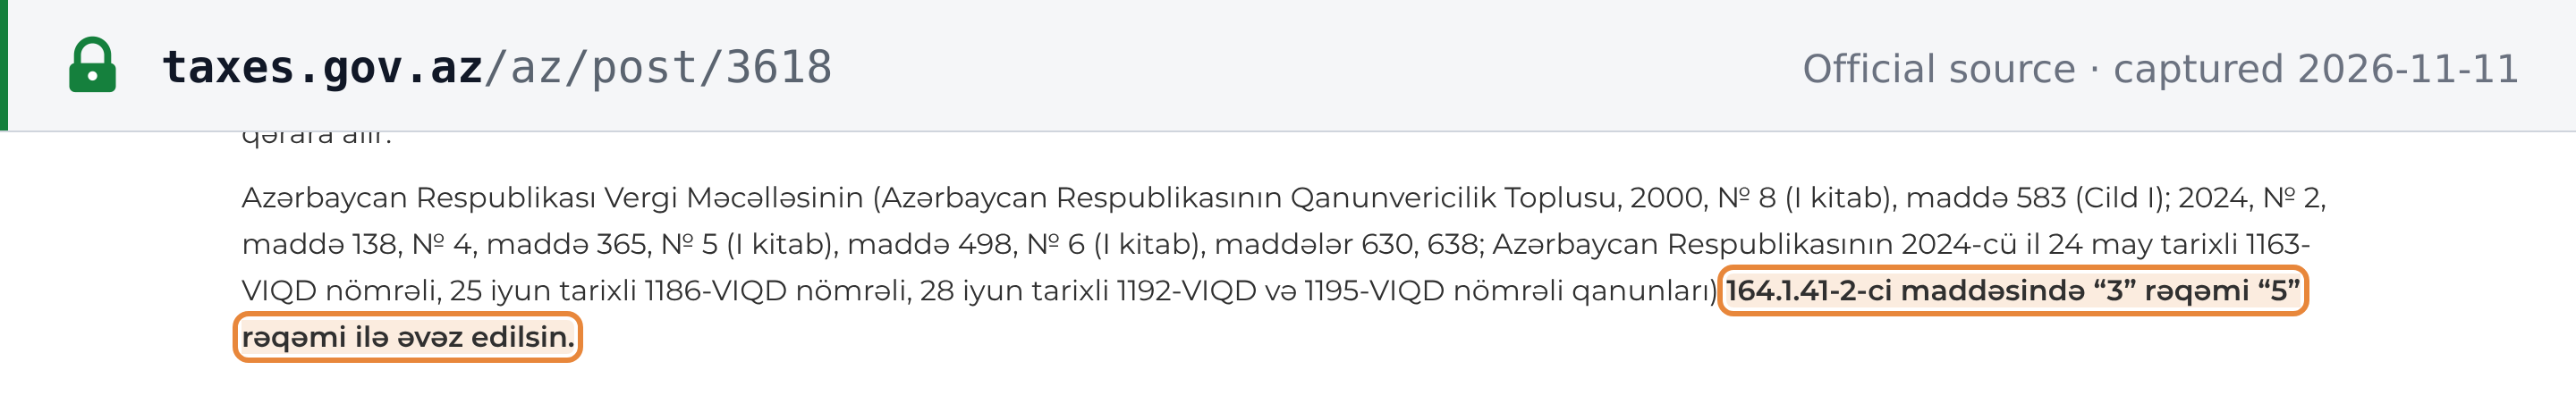
Azerbaijan’s Law No. 45-VIIQD of 8 October 2024 on an amendment to the Tax Code has a single operative provision: in Article 164.1.41-2, the figure “3” is replaced by “5”. The law has no commencement clause of its own, so it took effect on publication on AZERTAC on 15 October 2024. It was also printed in the Azərbaycan newspaper on 16 October 2024.
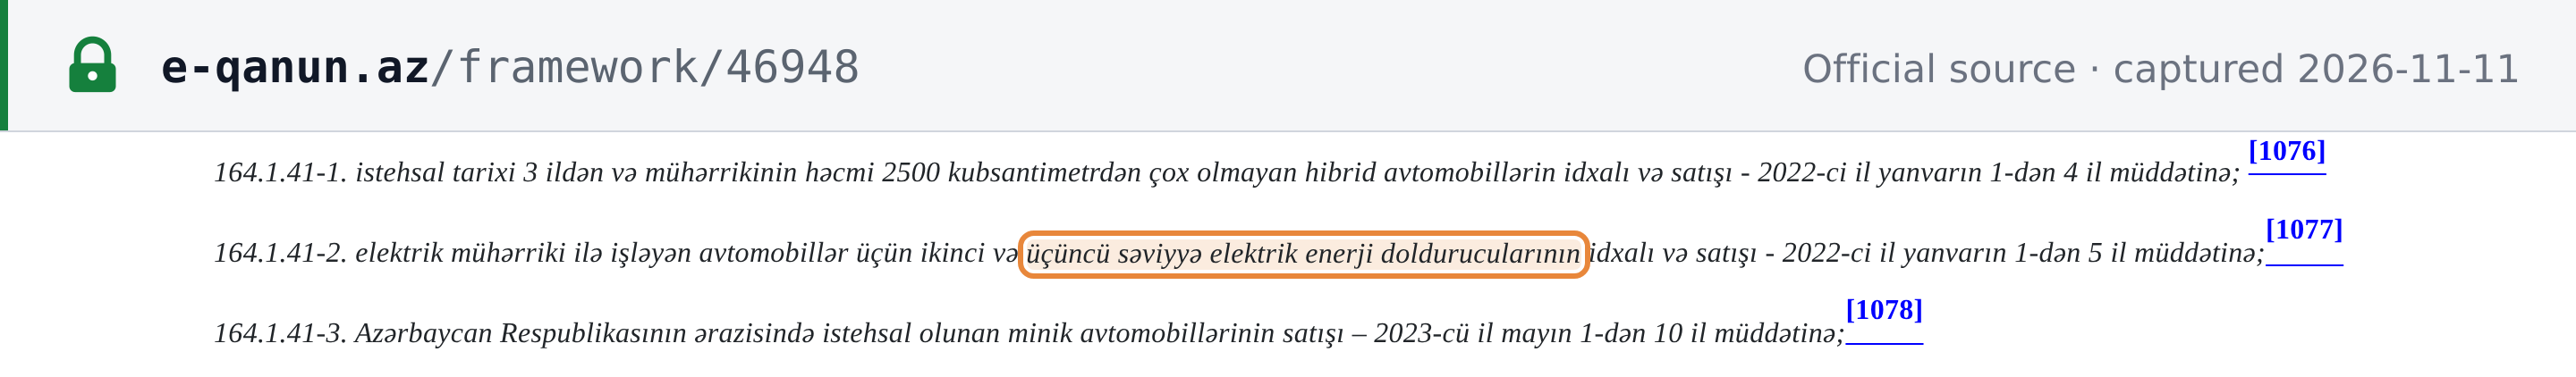
Article 164.1.41-2 exempts from VAT the import and sale of second- and third-level electric chargers for electric-motor vehicles, counted from 1 January 2022. The original term was 3 years, ending on 1 January 2025. The amendment makes it 5 years, so the exemption now runs until 1 January 2027.
The consolidated Tax Code on e-qanun.az shows the article in its amended form, with footnote [1077] citing Law 45-VIIQD.
What it means
The exemption is still in force but has less than two months left: on the statute’s own terms it ends on 1 January 2027. The consolidated Tax Code checked on 11 November 2026 shows no further extension of Article 164.1.41-2. Importers and sellers of chargers should plan for VAT at the standard 18% rate on imports and sales from that date unless another amending law is published before then, and should check stock bought VAT-free that will be sold after 1 January 2027.
Proof
164.1.41-2. elektrik mühərriki ilə işləyən avtomobillər üçün ikinci və üçüncü səviyyə elektrik enerji doldurucularının idxalı və satışı - 2022-ci il yanvarın 1-dən 5 il müddətinə;164.1.41-2. import and sale of second- and third-level electric chargers for electric-motor vehicles – for 5 years from 1 January 2022;
 Source snapshot of the official page. Open full size ↗
164.1.41-2-ci maddəsində “3” rəqəmi “5” rəqəmi ilə əvəz edilsin.In Article 164.1.41-2, the figure “3” shall be replaced by the figure “5”.
 Source snapshot of the official page. Open full size ↗