Belgium lets suppliers skip the structured e-invoice when the customer cannot technically receive one
This page records one dated change. For the rules in Belgium as they stand today, see the Belgium guide →
- Jurisdiction
- Belgium
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- Action required
- Announced
- 20 February 2026
- Effective
- 20 February 2026
- Instrument
- BE-ACT-2026001291
- Authority
- SPF Finances (FPS Finance), Belgium
- Verified
- Fetched from official source · high confidence
Belgian suppliers within the structured B2B e-invoicing obligation, and non-Belgian-established customers registered for Belgian VAT that buy for an establishment outside Belgium.
Suppliers may fall back to a non-structured invoice only when the customer genuinely cannot receive a structured e-invoice (keep evidence). Supplies made exclusively for a foreign establishment of a non-Belgian-established customer need no Peppol e-invoice from 2 March 2026.
The Law of 10 February 2026 on miscellaneous VAT provisions (Moniteur belge 20 February 2026, Numac 2026001291) amends the Belgian B2B e-invoicing rules. From 20 February 2026 (art. 4), a supplier does not have to issue a structured e-invoice under art. 53, §2bis when the recipient cannot, for technical reasons, receive one itself or through a third party; an ordinary invoice under §2 is still required. From 2 March 2026 (art. 5), customers registered for Belgian VAT do not give their Belgian VAT number for supplies of goods or services in Belgium made exclusively for their establishment outside Belgium, unless they are established in Belgium (previously this covered services only). Such supplies therefore fall outside the structured e-invoicing obligation, which depends on the customer having to give that number.
What changed in detail
The Law of 10 February 2026 on miscellaneous VAT provisions (Moniteur belge 20 February 2026, Numac 2026001291) makes two changes to the scope of Belgium’s structured B2B e-invoicing obligation.
Technical inability (article 4, from 20 February 2026). A new subparagraph in article 53, §2bis of the VAT Code: a supplier does not have to issue a structured e-invoice when the recipient cannot, for technical reasons, receive one, either itself or through a third party acting on its behalf. The supplier must still issue an ordinary invoice under §2.
Supplies for a foreign establishment (article 5, from 2 March 2026). Article 53quater, §1, second subparagraph, 3° previously covered services only. It now covers supplies of goods and services that take place in Belgium but are made exclusively for an establishment of the customer outside Belgium, unless the customer is established in Belgium. For those supplies, a customer registered for Belgian VAT does not give its Belgian VAT number. Because the structured e-invoicing obligation depends on the customer having to give that number, these supplies fall outside it.
What it means
Both changes are in force and unchanged since. They narrow the B2B e-invoicing mandate, which took effect on 1 January 2026, without touching the Peppol BIS format rules.
The technical-inability exception is a fallback, not a choice. Keep evidence that the customer could not receive a structured invoice, and expect it to matter more if the planned e-reporting system goes ahead. For supplies made exclusively for a foreign branch of a non-Belgian business, a Peppol invoice is not required from 2 March 2026.
Proof
L’assujetti visé à l’alinéa 1er n’est pas tenu d’émettre ou de faire émettre une facture électronique structurée lorsque le destinataire de cette facture électronique structurée visé au présent paragraphe n’est pas en mesure, pour des raisons techniques, lui-même ou via un tiers en son nom et pour son compte, de recevoir cette facture.The taxable person referred to in the first subparagraph is not required to issue, or have issued, a structured electronic invoice where the recipient referred to in this paragraph is unable, for technical reasons, itself or through a third party on its behalf, to receive that invoice.
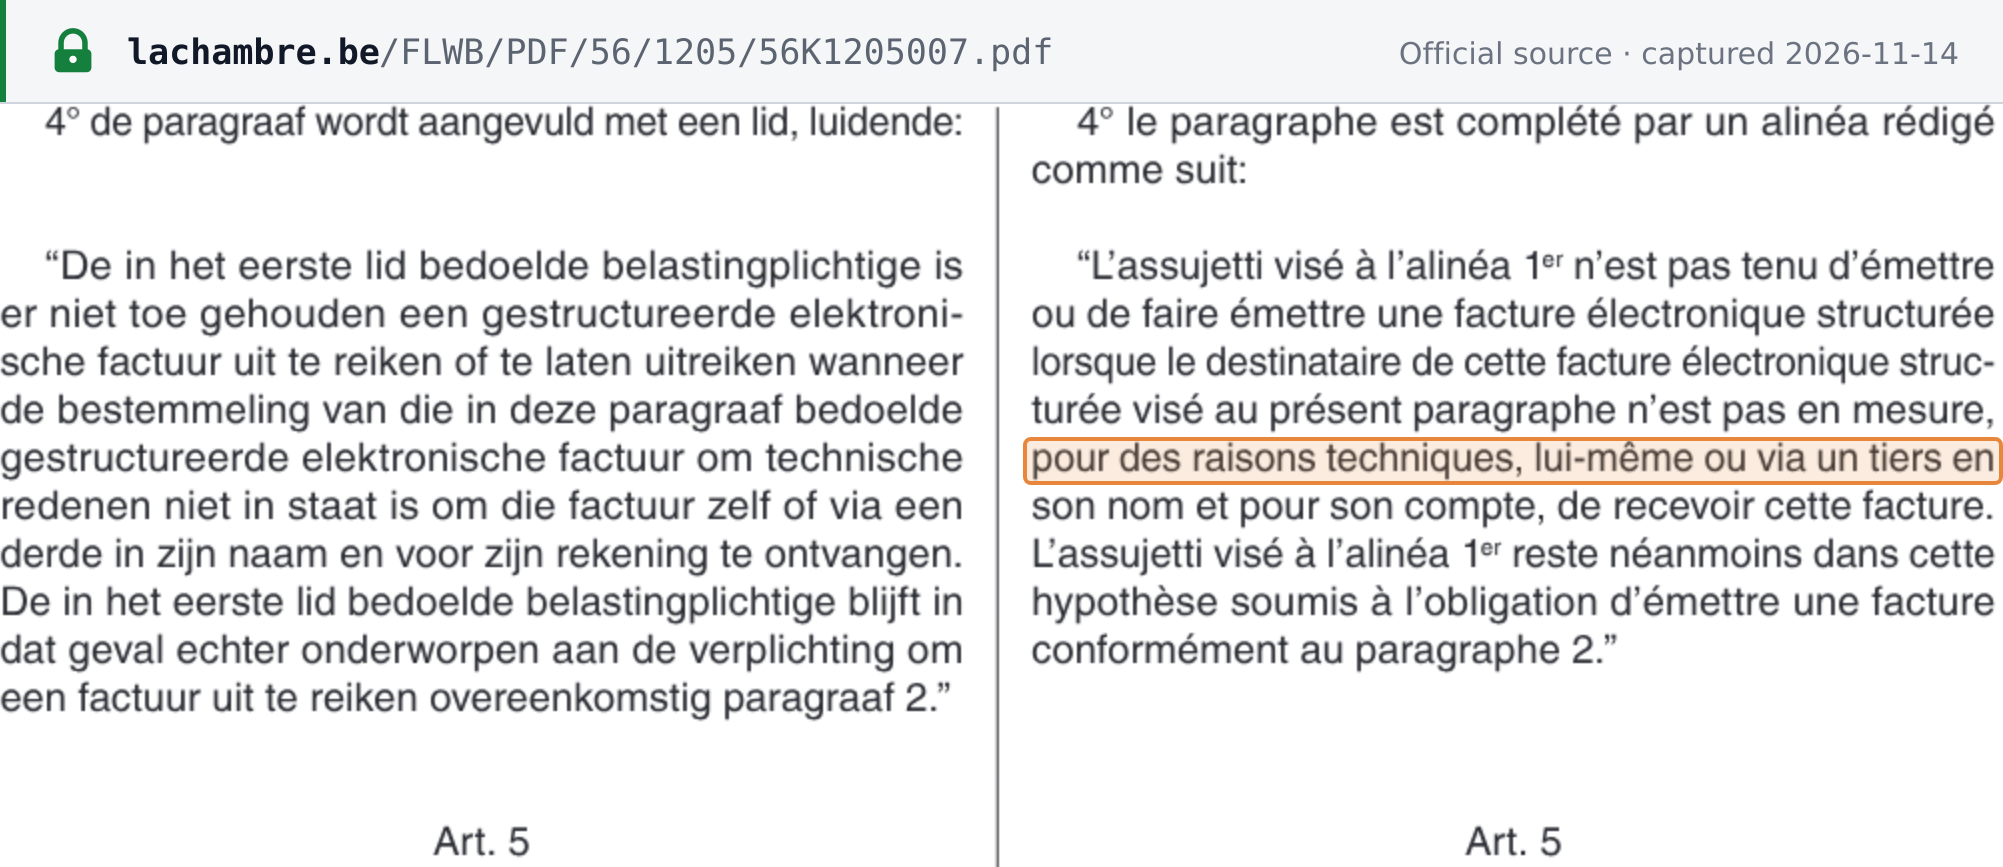 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Chambre des représentants, DOC 56 1205/007 (texte adopté en deuxième lecture; adopté tel quel en séance plénière, DOC 56 1205/009) · www.lachambre.be
L'assujetti visé à l'alinéa 1er n'est pas tenu d'émettre ou de faire émettre une facture électronique structurée lorsque le destinataire de cette facture électronique structurée visé au présent paragraphe n'est pas en mesure, pour des raisons techniques, lui-même ou via un tiers en son nom et pour son compte, de recevoir cette facture.The taxable person referred to in the first subparagraph is not required to issue, or have issued, a structured electronic invoice where the recipient referred to in this paragraph is unable, for technical reasons, itself or through a third party on its behalf, to receive that invoice.
Archived from the official distribution · Fisconetplus 3295c43b-f632-4c76-af1c-21d249b36cf3: Article 53, Code de la TVA (texte actuel et historique) · www.minfin.fgov.be