Belgium prorates the small-business VAT franchise ceiling for mid-year starters and requires prior notice
This page records one dated change. For the rules in Belgium as they stand today, see the Belgium guide →
- Jurisdiction
- Belgium
- Tax
- VAT
- Change type
- Threshold
- Status
- In force
- Impact
- Plan ahead
- Announced
- 20 February 2026
- Effective
- 20 February 2026
- Instrument
- BE-ACT-2026001291
- Authority
- SPF Finances (FPS Finance), Belgium
- Verified
- Fetched from official source · high confidence
Businesses established in Belgium using or planning to use the small-business VAT franchise, especially those starting their activity during a calendar year.
Businesses starting mid-year must check the reduced pro-rata franchise ceiling and notify SPF Finances before using the franchise. Franchise users cannot reclaim input VAT on their exempt activity.
The Law of 10 February 2026 on miscellaneous VAT provisions (Moniteur belge 20 February 2026, Numac 2026001291) corrects the SME franchise in force since 1 January 2025. From 20 February 2026 (art. 16, art. 56ter §1 al. 2 of the VAT Code), for a taxable person that starts its activity during the calendar year, the EUR 25,000 ceiling is reduced pro rata to the days elapsed between 1 January and the start date. From early March 2026 (2 March in the Code modifications list), the intention to use the franchise must be notified in advance rather than at the start of activity. From 2 March 2026, a new art. 56bis §4 (art. 15) states that franchise users cannot deduct input VAT on goods and services used for their exempt supplies.
What changed in detail
The Law of 10 February 2026 on miscellaneous VAT provisions (Moniteur belge 20 February 2026, Numac 2026001291) corrects the small-business VAT franchise that has applied since 1 January 2025.
Pro-rata ceiling (article 16, 1°, from 20 February 2026). A new second subparagraph in article 56ter, §1 of the VAT Code: when a taxable person starts its activity during the calendar year, the EUR 25,000 ceiling is reduced pro rata to the days elapsed between 1 January and the start date. Article 22 puts this provision into force on the day of publication.
Prior notice (article 16, 2°). The intention to use the franchise must now be notified to the administration in advance, replacing notification at the start of activity. This applies from early March 2026: the law sets no special date for it, and Fisconetplus gives 2 March 2026 in its list of Code changes and 1 March 2026 on the article page.
No deduction (article 15). A new article 56bis, §4 states that franchise users cannot deduct VAT on the goods and services they use for their exempt supplies.
What it means
These corrections are in force and sit inside a regime that keeps moving. The base scheme, including the cross-border route for EU businesses, came from the Law of 21 March 2024. The Law of 23 September 2026 raises the ceiling from 2027, from EUR 26,000 up to EUR 30,000 in 2031, and leaves the pro-rata subparagraph in place.
So a business starting on 1 July 2027 compares its turnover with roughly half of EUR 26,000, not the full amount. The notice now has to go in before the franchise is used.
Proof
Lorsque l’assujetti visé à l’alinéa 1er commence son activité économique dans le courant de l’année civile, le montant visé à l’alinéa 1er est réduit au prorata du nombre de jours écoulés entre le 1er janvier de l’année civile concernée et la date du commencement de l’activité.Where the taxable person referred to in the first subparagraph starts its economic activity during the calendar year, the amount referred to in the first subparagraph is reduced pro rata to the number of days elapsed between 1 January of that calendar year and the date the activity starts.
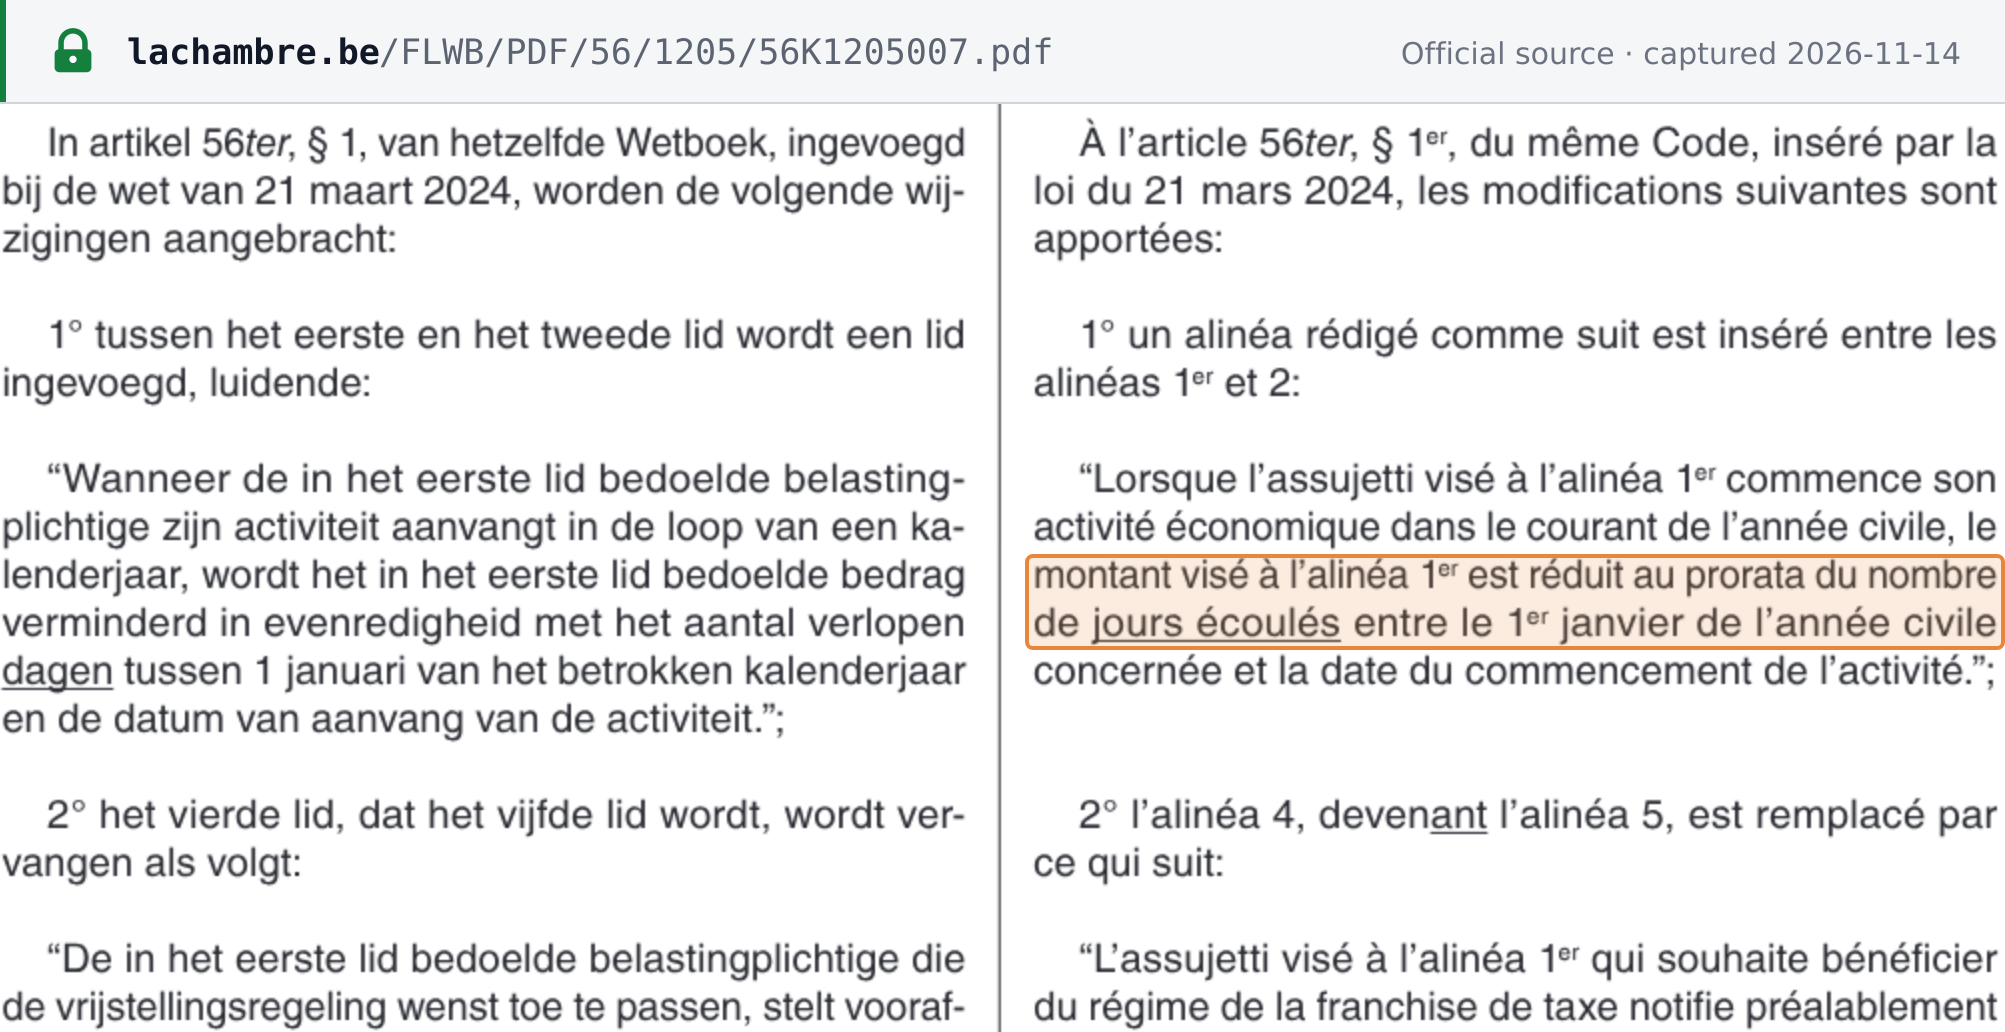 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Chambre des représentants, DOC 56 1205/007 (texte adopté en deuxième lecture; adopté tel quel en séance plénière, DOC 56 1205/009) · www.lachambre.be
Lorsque l'assujetti visé à l'alinéa 1er commence son activité économique dans le courant de l'année civile, le montant visé à l'alinéa 1er est réduit au prorata du nombre de jours écoulés entre le 1er janvier de l'année civile concernée et la date du commencement de l'activité.Where the taxable person referred to in the first subparagraph starts its economic activity during the calendar year, the amount referred to in the first subparagraph is reduced pro rata to the number of days elapsed between 1 January of that calendar year and the date the activity starts.
Archived from the official distribution · Fisconetplus 2df474a0-20a4-48cc-911b-298afbc32486: Article 56ter, Code de la TVA (texte actuel et historique) · www.minfin.fgov.be