Belgium removes fossil-fuel central heating from the 6% VAT rate for home renovation from 29 July 2025
This page records one dated change. For the rules in Belgium as they stand today, see the Belgium guide →
- Jurisdiction
- Belgium
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 29 July 2025
- Effective
- 29 July 2025
- Instrument
- BE-ACT-2025005578
- Authority
- SPF Finances (FPS Finance), Belgium
- Verified
- Fetched from official source · high confidence
Heating installers and renovation contractors supplying and fitting central-heating components fuelled by fossil fuels (gas, oil or other) in private dwellings, and the homeowners they invoice.
Contractors renovating dwellings must not apply the 6% rate to supplying and installing central-heating components fuelled by fossil fuels (gas, oil or other), including burners and boiler controls, for operations that become chargeable from 29 July 2025. Other renovation work on the same invoice can stay at 6% if the rubric XXXI conditions are met.
The Loi-programme of 18 July 2025 (Moniteur belge 29 July 2025, Numac 2025005578), art. 52, inserts §4, 3° into rubric XXXI of Table A of Royal Decree No. 20, in force from 29 July 2025 (art. 55). The 6% rate for renovation of private dwellings no longer applies to work that both supplies and fixes to a building all or part of the specific components of a central-heating installation fuelled by fossil fuels, including burners and the control devices connected to the boiler. Art. 53 of the same law writes the same exclusion into the replaced demolition-and-reconstruction rubric XXXVII.
What changed in detail
Article 52 of the loi-programme of 18 July 2025 (Moniteur belge 29 July 2025, Numac 2025005578) adds a 3° to §4 of rubric XXXI of Table A of Royal Decree No. 20. Rubric XXXI sets the 6% rate for renovating and repairing private dwellings. Under article 55 the change applies from 29 July 2025.
The 6% rate no longer applies to work that both supplies and fixes to a building all or part of the components of the specific part of a central-heating installation fuelled by fossil fuels. Burners and the regulating and control devices connected to the boiler are expressly included in the exclusion. That work is taxed at the standard rate of 21%.
Article 53 of the same law writes the same exclusion into each case of the replaced demolition-and-reconstruction rubric XXXVII.
The text does not address hybrid or mixed systems. Other renovation work in the same dwelling stays at 6% if the usual rubric XXXI conditions are met.
What it means
The exclusion is in force; the consolidated Royal Decree No. 20 carries rubric XXXI, §4, 3° unchanged. It is one of several moves that tilt Belgian VAT away from fossil heating. The same law moved coal and other solid fuels to 21%. Heat pumps went the other way: after the 2024 extension, they now carry a temporary 6% rate until 2030.
For installers, the practical step is to split the invoice: boiler, burner and controls at 21%, other qualifying renovation at 6%. The same carve-out applies in demolition-and-reconstruction projects.
Proof
aux opérations comportant à la fois la fourniture et la fixation à un bâtiment de tout ou partie des éléments constitutifs de la partie spécifique d’une installation de chauffage central alimentée par des combustibles fossiles, en ce compris les brûleurs et appareils de régulation et de contrôle reliés à la chaudière.[the reduced rate does not apply] to operations comprising both the supply and the fixing to a building of all or part of the components of the specific part of a central-heating installation fuelled by fossil fuels, including burners and the regulating and control devices connected to the boiler.
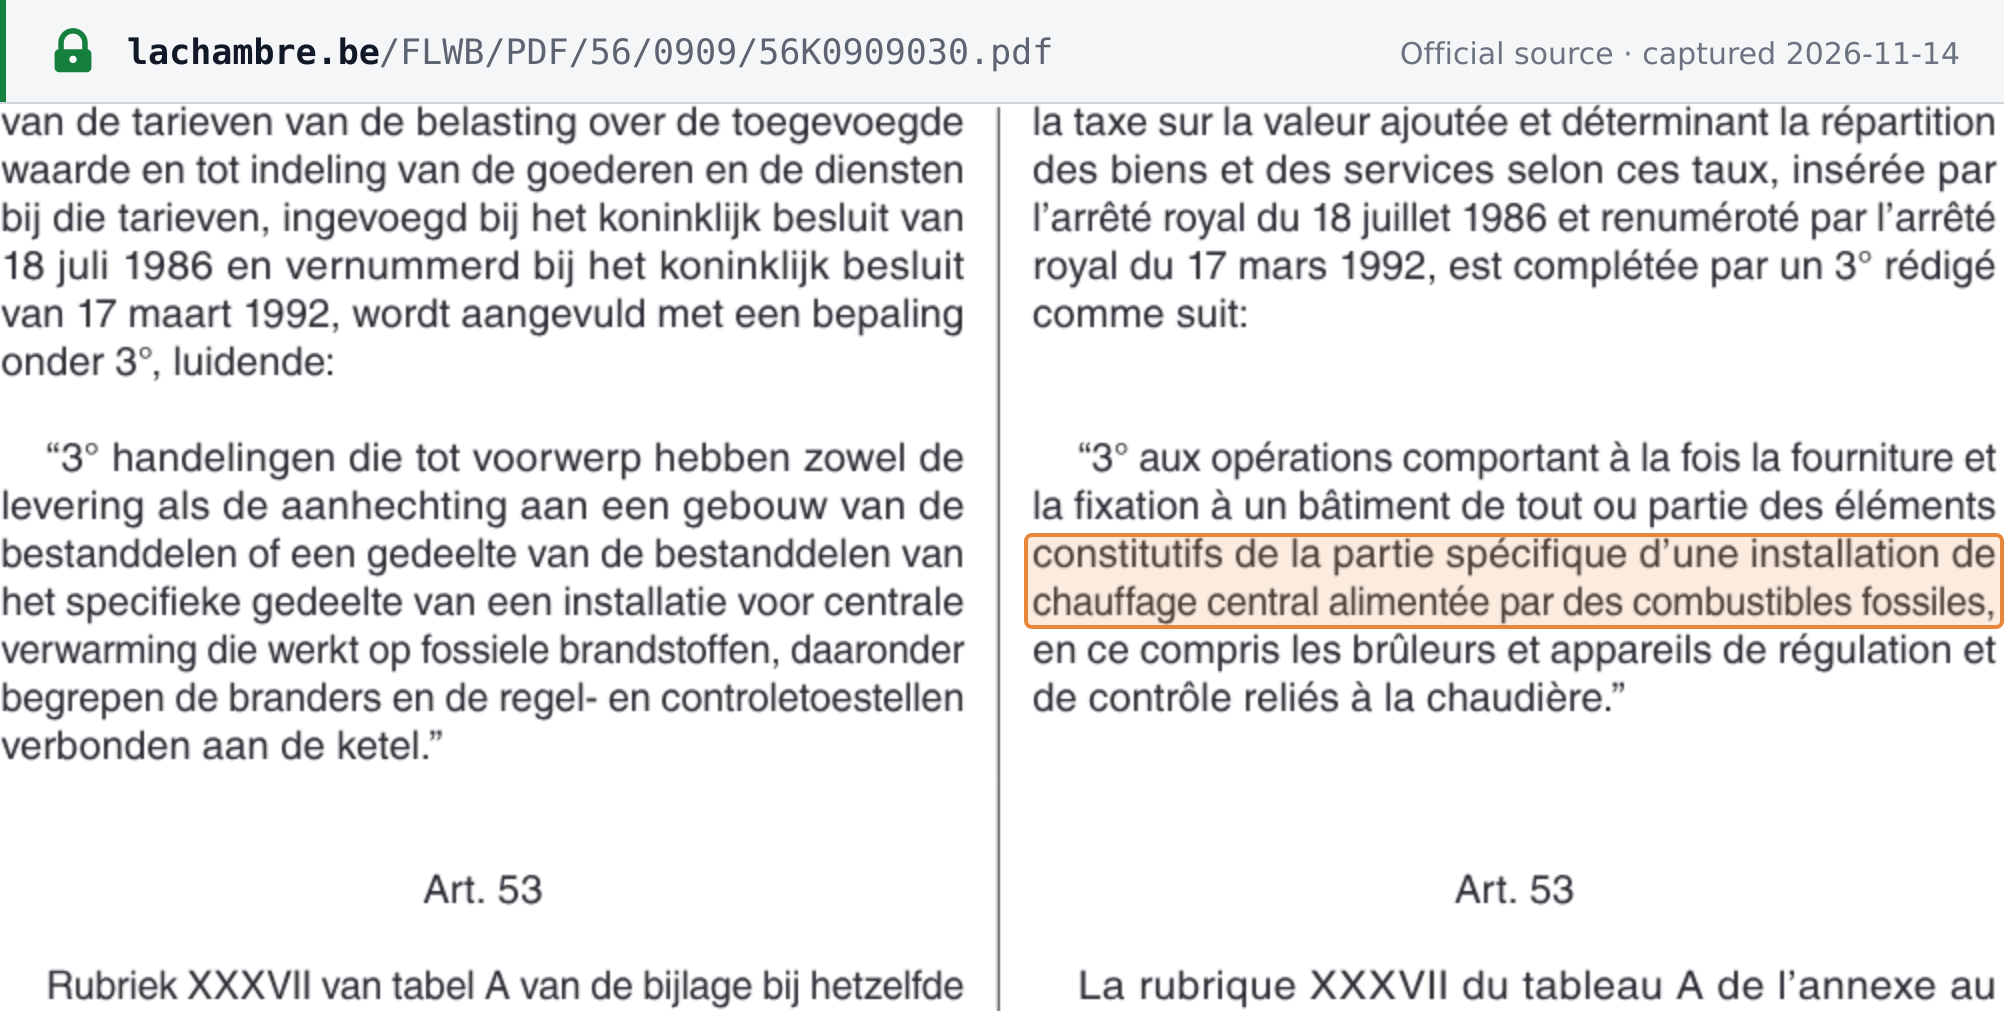 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Chambre des représentants, DOC 56 0909/030 (projet de loi-programme, articles adoptés en séance plénière; DOC 56 0909/031) · www.lachambre.be
aux opérations comportant à la fois la fourniture et la fixation à un bâtiment de tout ou partie des éléments constitutifs de la partie spécifique d'une installation de chauffage central alimentée par des combustibles fossiles, en ce compris les brûleurs et appareils de régulation et de contrôle reliés à la chaudière.[the reduced rate does not apply] to operations comprising both the supply and the fixing to a building of all or part of the components of the specific part of a central-heating installation fuelled by fossil fuels, including burners and the regulating and control devices connected to the boiler.
Archived from the official distribution · Fisconetplus b38e1cae-8676-4324-9ef8-2ef04ffee07d: TVA, Arrêté royal n° 20 (coordination officieuse n° 39), Tableau A, rubrique XXXI, § 4, 3° · www.minfin.fgov.be