Chile’s SII sets VAT filing rules for remote sellers of low-value goods and digital platforms
- Jurisdiction
- Chile
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- FYI
- Announced
- 30 July 2025
- Effective
- 25 October 2025
- Instrument
- CL-RESOLUTION-93-2025
- Authority
- Servicio de Impuestos Internos (SII), Chile
- Verified
- Fetched from official source · high confidence
Non-resident remote sellers of low-value goods (up to USD 500) to Chilean non-IVA buyers, and operators of digital intermediation platforms, registered in the simplified regime.
No action — monitoring only.
Resolución Ex. SII N° 93 (30 July 2025) regulated IVA declaration and payment for remote sellers of goods (ventas remotas, USD ≤ 500 to non-VAT-contributor Chilean buyers) and digital intermediation platform operators under the simplified régimen of Párrafo 7° bis, implementing the goods-via-platforms provisions of Ley 21.713 effective 25 October 2025.
What changed in detail
Resolución Exenta SII N° 93, dated 30 July 2025, regulates how contributors without domicile or residence in Chile declare and pay IVA under the simplified regime of Párrafo 7° bis of the IVA law when they:
- sell remotely tangible movable goods of low value (up to USD 500) located abroad to buyers in Chile who are not IVA contributors; or
- operate digital intermediation platforms that facilitate such sales, or the supply of services by third parties.
It implements the goods and platform provisions that Ley 21.713 added to the IVA law (articles 3 bis and 4), and applies to contributors registered under Resolución Ex. SII N° 84 de 2025, which sets the registration procedure for these sellers and platforms. Among other things it requires platforms to send lists of the sellers and service providers operating through them, and requires IVA to be charged item by item when a shipment contains goods with different IVA treatment.
Resolutive point 2° applies the resolution from 25 October 2025, to IVA accrued on sales and operations from that date. As a one-off, monthly filers may declare the IVA accrued from 25 to 31 October 2025 together with November 2025.
What it means
The resolution has applied since 25 October 2025 and is still in force; it is the filing rule for the goods and platform regime of Ley 21.713. Non-resident service providers that are not platforms keep filing under Resolución N° 107.
The split matters for platforms: a service-intermediation platform registers under Resolución N° 105 de 2024, but declares the IVA on the underlying services concluded through it under this resolution.
Proof
REGULA LA DECLARACIÓN Y PAGO DEL IVA POR PARTE DE VENDEDORES REMOTOS Y OPERADORES DE PLATAFORMAS DIGITALES DE INTERMEDIACIÓN CONFORME AL RÉGIMEN DE TRIBUTACIÓN SIMPLIFICADA DEL PÁRRAFO 7° BIS DE LA LEY SOBRE IMPUESTO A LAS VENTAS Y SERVICIOS.REGULATES THE DECLARATION AND PAYMENT OF VAT BY REMOTE SELLERS AND OPERATORS OF DIGITAL INTERMEDIATION PLATFORMS UNDER THE SIMPLIFIED TAX REGIME OF PARAGRAPH 7° BIS OF THE LAW ON SALES AND SERVICES TAX.
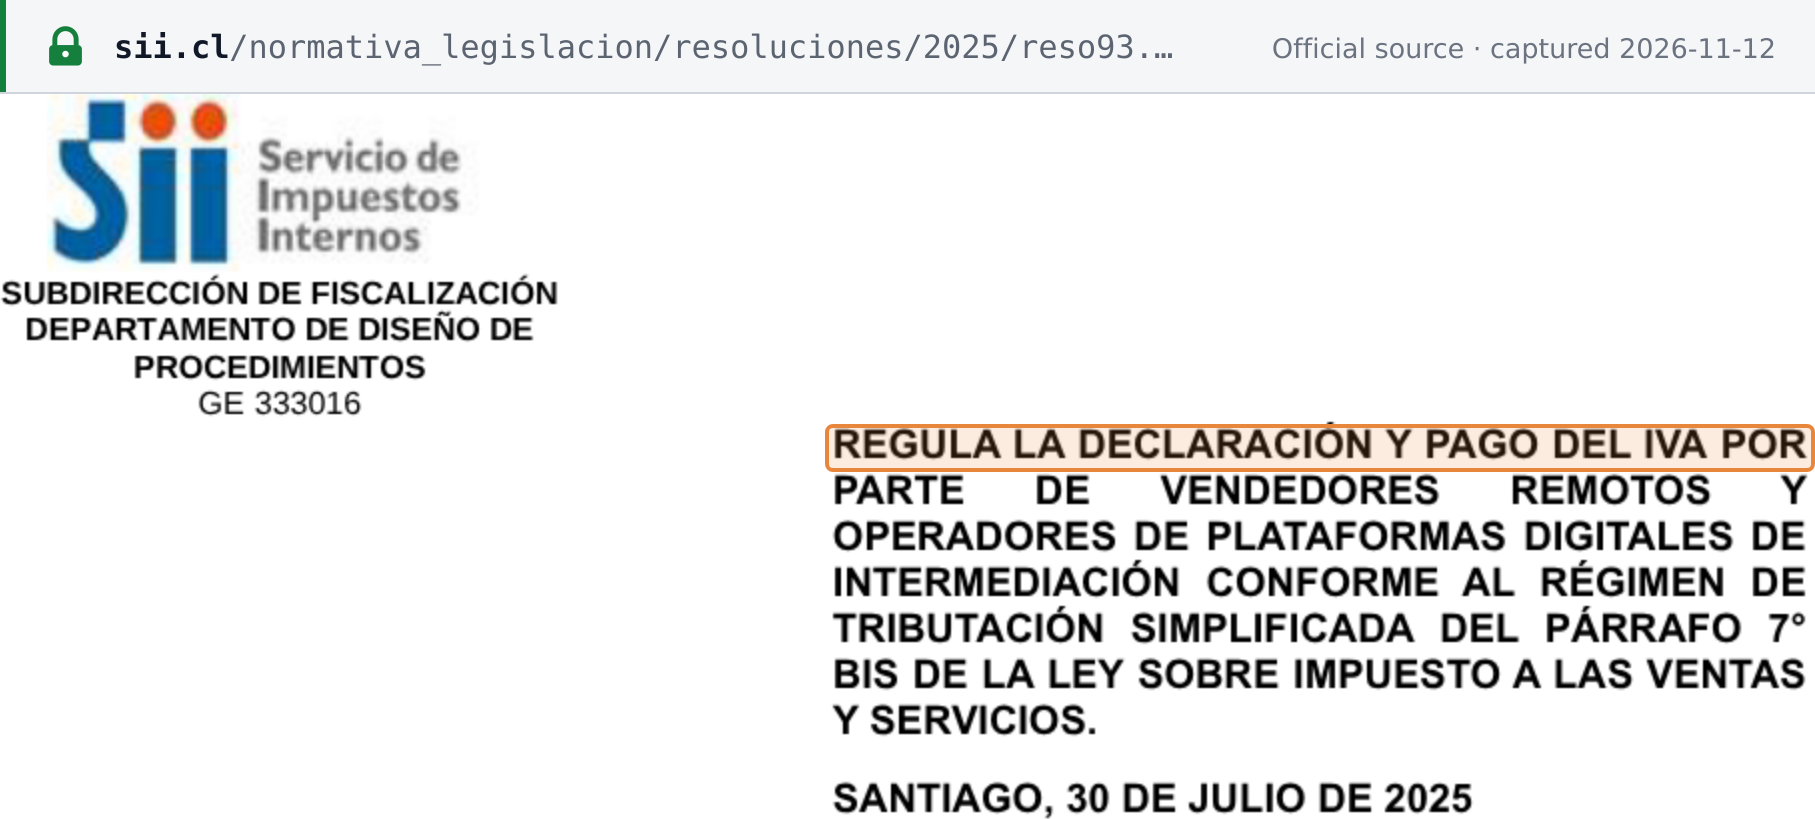 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Resolución Ex. SII N° 93, Santiago, 30 de julio de 2025 · www.sii.cl