Chile’s SII sets how non-resident providers file and pay VAT on form F129
- Jurisdiction
- Chile
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 14 November 2024
- Effective
- 1 December 2024
- Instrument
- CL-RESOLUTION-107-2024
- Authority
- Servicio de Impuestos Internos (SII), Chile
- Verified
- Fetched from official source · high confidence
Non-domiciled, non-resident providers registered in Chile’s simplified IVA regime (Párrafo 7° bis of DL 825).
No action — monitoring only.
Resolución Ex. SII N° 107 (14 November 2024) set the procedure for non-domiciled, non-resident contributors registered in the simplified regime to declare and pay IVA on form F129. Contributors choose a monthly or quarterly period and file and pay by the 20th of the following month. It replaced Resolución 67/2020 from 1 December 2024 and implements the administrative framework of Ley 21.713.
What changed in detail
Resolución Exenta SII N° 107, dated 14 November 2024, sets the procedure by which non-domiciled, non-resident contributors registered in Chile’s simplified IVA regime declare and pay the tax. It is the filing counterpart to the registration rules in Resolución N° 105 of the same year and implements the administrative side of Ley 21.713.
Under the resolution:
- the return is the IVA Digital form (F129), filed through the SII’s digital IVA portal, including for periods with no activity;
- the tax period is the one the contributor chose at registration: monthly or quarterly;
- each period is declared and paid between the 1st and the 20th of the following month;
- the return and payment are made in the currency chosen at registration (US dollars, euros or Chilean pesos), with payment by SWIFT transfer for foreign currency.
The resolution also covers what goes into the taxable base, the treatment of supplies to local IVA contributors, and how amended returns are handled after a change of currency.
Resolutive point 3° applies it from 1 December 2024 and revokes Resolución Ex. SII N° 67 de 2020 from the same date. Returns and payments already made under Resolución 67 stand.
What it means
The resolution is still in force as the filing procedure for non-resident service providers. Remote sellers of low-value goods and platform operators, brought in by Ley 21.713 from 25 October 2025, file under the separate rules of Resolución Ex. SII N° 93.
The practical consequences for a provider: the period choice made at registration fixes the filing rhythm, a late F129 attracts fines and interest, and the 20th-of-the-month deadline applies to payment as well as filing.
Proof
3º La presente resolución regirá a partir del 1° de diciembre de 2024. Déjese sin efecto la Resolución Ex. SII N° 67 de 2020 a partir de la misma fecha.3º This resolution shall apply from 1 December 2024. Resolución Ex. SII N° 67 of 2020 is revoked from the same date.
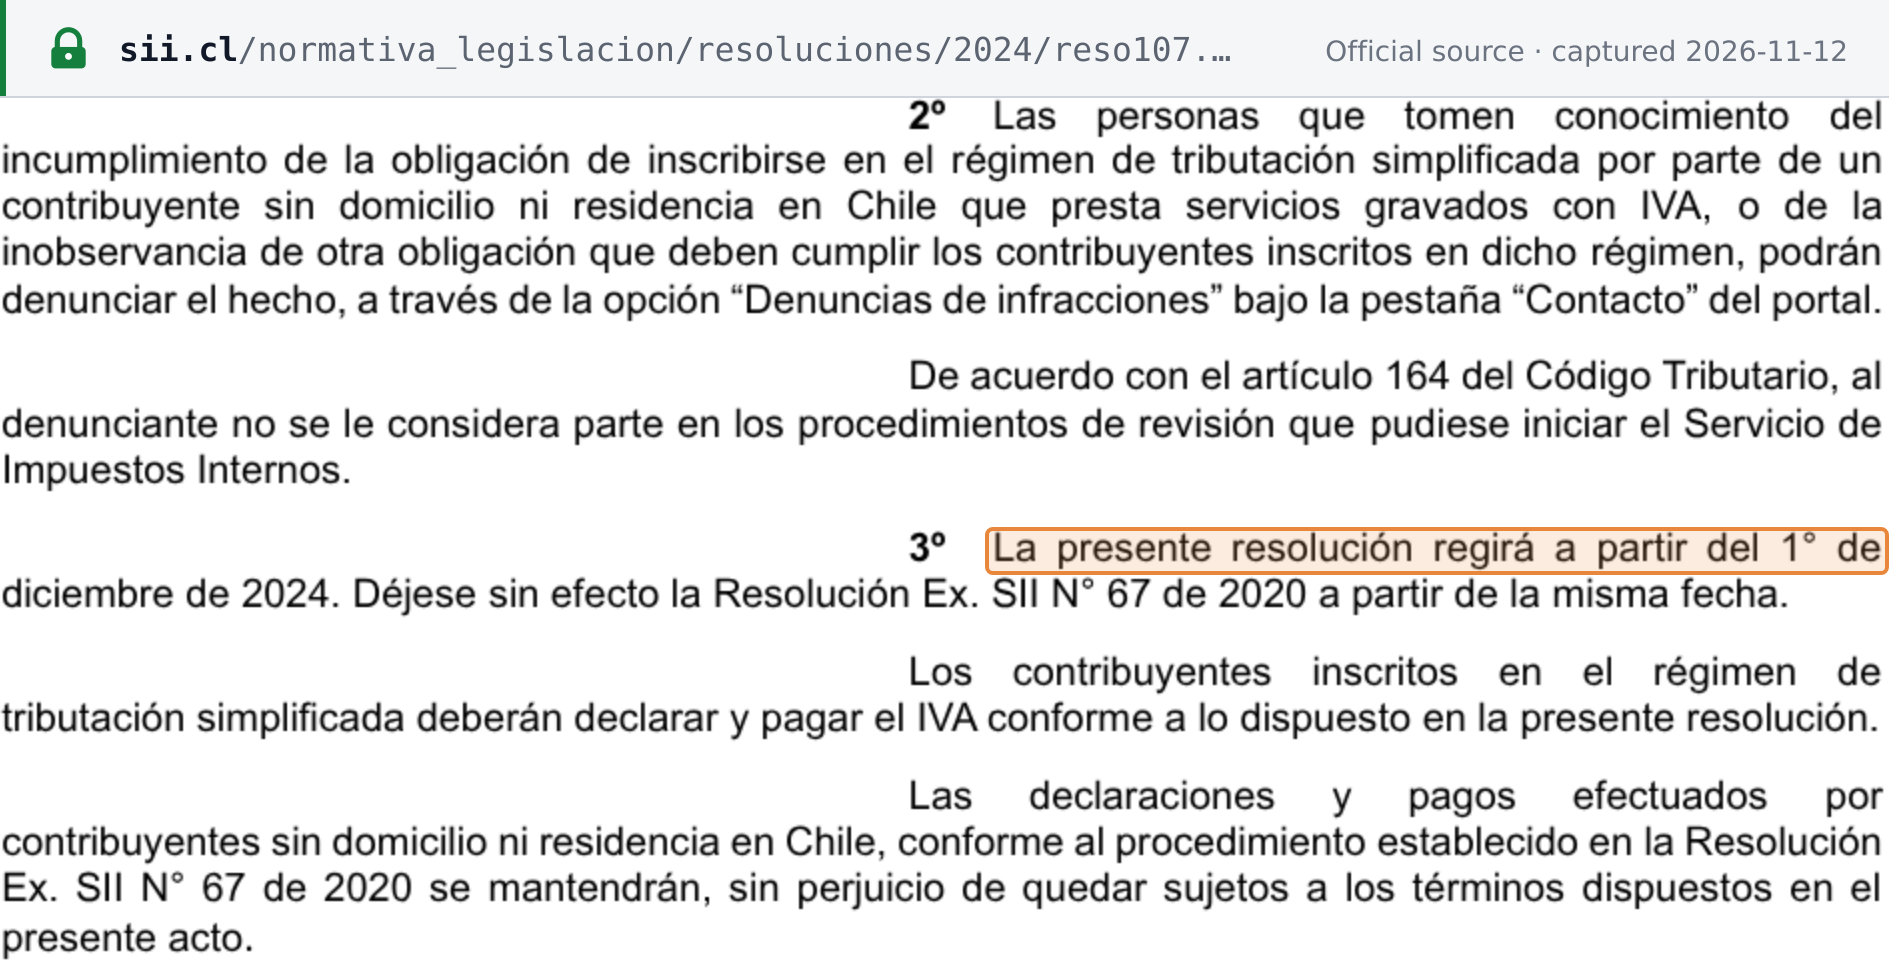 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Resolución Ex. SII N° 107, Santiago, 14 de noviembre de 2024 · www.sii.cl