China taxes express delivery as collection-and-delivery services and lets online freight platforms deduct fuel and tolls (MOF/STA No. 5 of 2025)
This page records one dated change. For the rules in China as they stand today, see the China guide →
- Jurisdiction
- China
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Announced
- 11 August 2025
- Effective
- 11 August 2025
- Instrument
- CN-JOINT-ANNOUNCEMENT-2025-5
- Authority
- 财政部 税务总局 (Ministry of Finance and State Taxation Administration of the People's Republic of China)
- Verified
- Fetched from official source · high confidence
Licensed express-delivery enterprises, their filed branches and last-mile outlets; taxpayers licensed for online road-freight platform operation (网络货运).
Express delivery enterprises must classify revenue as 收派服务 when filing VAT returns. Online freight platform operators may now claim input VAT deductions on fuel and tolls purchased for actual carriers — review accounts for eligible deductions from 11 August 2025.
MOF and STA Announcement No. 5 of 2025 (财政部 税务总局公告2025年第5号), effective from date of publication (11 August 2025), makes two VAT rulings: (1) Revenue of licensed express delivery enterprises (快递企业) from express services — defined as collecting, sorting, transporting and delivering within a committed time limit, excluding pure transport services — is classified as 收派服务 (pickup-and-delivery services) for VAT purposes. (2) Online road-freight platform operators (网络货运经营纳税人) holding a 网络货运 licence may deduct input VAT on refined oil, natural gas, electricity, hydrogen, methanol and road, bridge and lock (闸) tolls purchased and provided to actual carriers for transport services commissioned by the operator, provided deduction vouchers comply with current rules.
What changed in detail
The Ministry of Finance and the State Taxation Administration issued Announcement No. 5 of 2025 (财政部 税务总局公告2025年第5号), dated 11 August 2025 and effective on publication. Matters not yet handled before then follow it; matters already handled are not reopened (Article 3).
Express delivery (Article 1). Income of express-delivery enterprises from express services is taxed as collection and delivery services (收派服务). Express-delivery enterprises are those licensed for express business in China, their branches filed with the postal authority, and their filed last-mile outlets. Express service means collecting, sorting, transporting and delivering items within a committed time limit. It excludes cases where the enterprise only provides transport.
Online freight platforms (Article 2). A taxpayer licensed for online road-freight platform operation (网络货运) may deduct input VAT on refined oil, natural gas, electricity, hydrogen, dimethyl ether, methanol and other vehicle fuels it buys and hands to actual carriers, and on road, bridge and lock tolls it pays. Two conditions apply: the fuel or tolls are used for transport the platform has commissioned the actual carrier to perform, and the deduction vouchers meet current rules. The platform must contract with the shipper as carrier and bear carrier liability; pure information-matching services do not qualify.
What it means
The express-delivery classification is still the rule: since 1 January 2026 it is written into the services annex of MOF/STA Announcement No. 9 of 2026, the scope notes issued under the VAT Law. Collection and delivery is a logistics support service, taxed at 6% for general taxpayers rather than at the 9% transport rate, so express operators should not split contracts into a transport leg. The freight-platform deduction was not restated in the January 2026 input-credit announcement (MOF/STA Announcement No. 13 of 2026), and no repeal has been published. Platforms relying on it should keep the commissioning records that show each fuel or toll purchase went to a contracted haul.
Proof
一、快递企业提供快递服务取得的收入,按照“收派服务”缴纳增值税。1. Income obtained by express-delivery enterprises from express services is subject to VAT as "collection and delivery services".
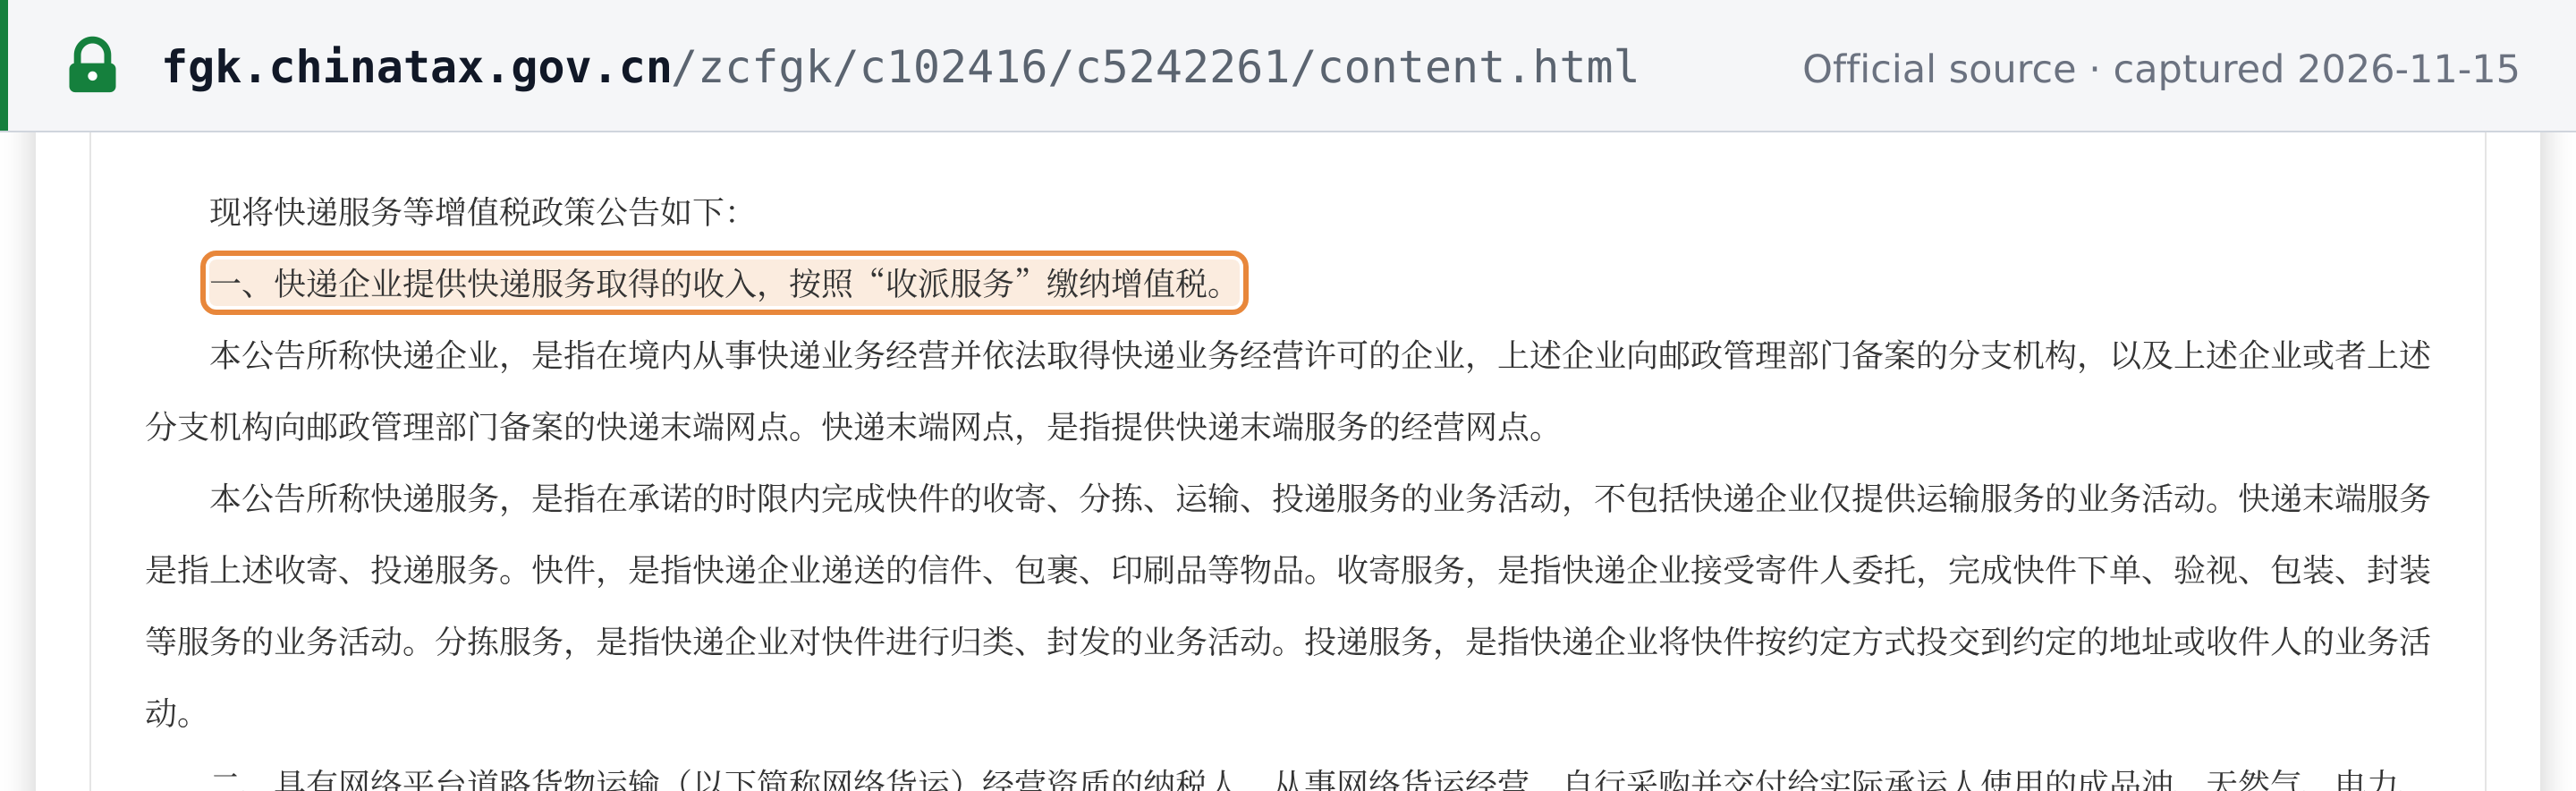 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · 财政部 税务总局公告2025年第5号《财政部 税务总局关于明确快递服务等增值税政策的公告》(成文日期 2025-08-11),第一条 · fgk.chinatax.gov.cn