China restores VAT on interest from government, local-government and financial bonds issued from 8 August 2025
This page records one dated change. For the rules in China as they stand today, see the China guide →
- Jurisdiction
- China
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 31 July 2025
- Effective
- 8 August 2025
- Instrument
- CN-JOINT-ANNOUNCEMENT-2025-4
- Authority
- 财政部 税务总局 (Ministry of Finance and State Taxation Administration of the People's Republic of China)
- Verified
- Fetched from official source · high confidence
Holders of PRC government bonds, local government bonds and financial bonds, mainly banks and other financial institutions, for bonds issued on or after 8 August 2025.
Financial institutions holding or issuing new government/local-government/financial bonds from 8 August 2025 must account for VAT on interest income. Bonds issued before that date remain exempt until maturity regardless of when interest is paid.
MOF and STA Announcement No. 4 of 2025 (财政部 税务总局公告2025年第4号), issued 31 July 2025 and effective 8 August 2025, restores VAT on interest income from newly issued government bonds (国债), local government bonds (地方政府债券) and financial bonds (金融债券) issued on or after 8 August 2025. Interest on bonds issued before that date (including further issuances under previously issued bonds) remains exempt until maturity. Financial bonds are defined as securities issued by legally established financial institution legal persons in China's national interbank or exchange bond markets, paying agreed principal and interest, and held by financial institutions.
What changed in detail
The Ministry of Finance and the State Taxation Administration issued Announcement No. 4 of 2025 (财政部 税务总局公告2025年第4号), dated 31 July 2025.
- Article 1: from 8 August 2025, VAT is restored on interest income from government bonds (国债), local government bonds (地方政府债券) and financial bonds (金融债券) newly issued on or after that date.
- Interest on bonds of those kinds issued before 8 August 2025, including further tranches of those bonds issued after that date (续发行), stays exempt until the bonds mature.
- Article 2: financial bonds are securities issued by financial-institution legal persons established in China, in the national interbank or exchange bond markets, that repay principal and interest as agreed and are held by financial institutions.
The announcement has two articles and no other conditions.
What it means
The rule is still in force. MOF/STA Announcement No. 10 of 2026 (cn-small-taxpayer-vat-law-2026), which ended most pre-2026 VAT reliefs on 1 January 2026, lists Announcement No. 4 of 2025 among the instruments whose reliefs continue (item 21(6)). So the grandfathering of bonds issued before 8 August 2025 survives the VAT Law. For bond desks the split now runs by issue date, not purchase date: a reopening of a pre-August 2025 bond stays exempt, while a new line issued after it is taxable. Pricing has to reflect that, and portfolio systems need the issue date of every holding to tag interest correctly.
Proof
自2025年8月8日起,对在该日期之后(含当日)新发行的国债、地方政府债券、金融债券的利息收入,恢复征收增值税。With effect from 8 August 2025, VAT is restored on interest income from government bonds, local government bonds and financial bonds newly issued on or after that date (inclusive).
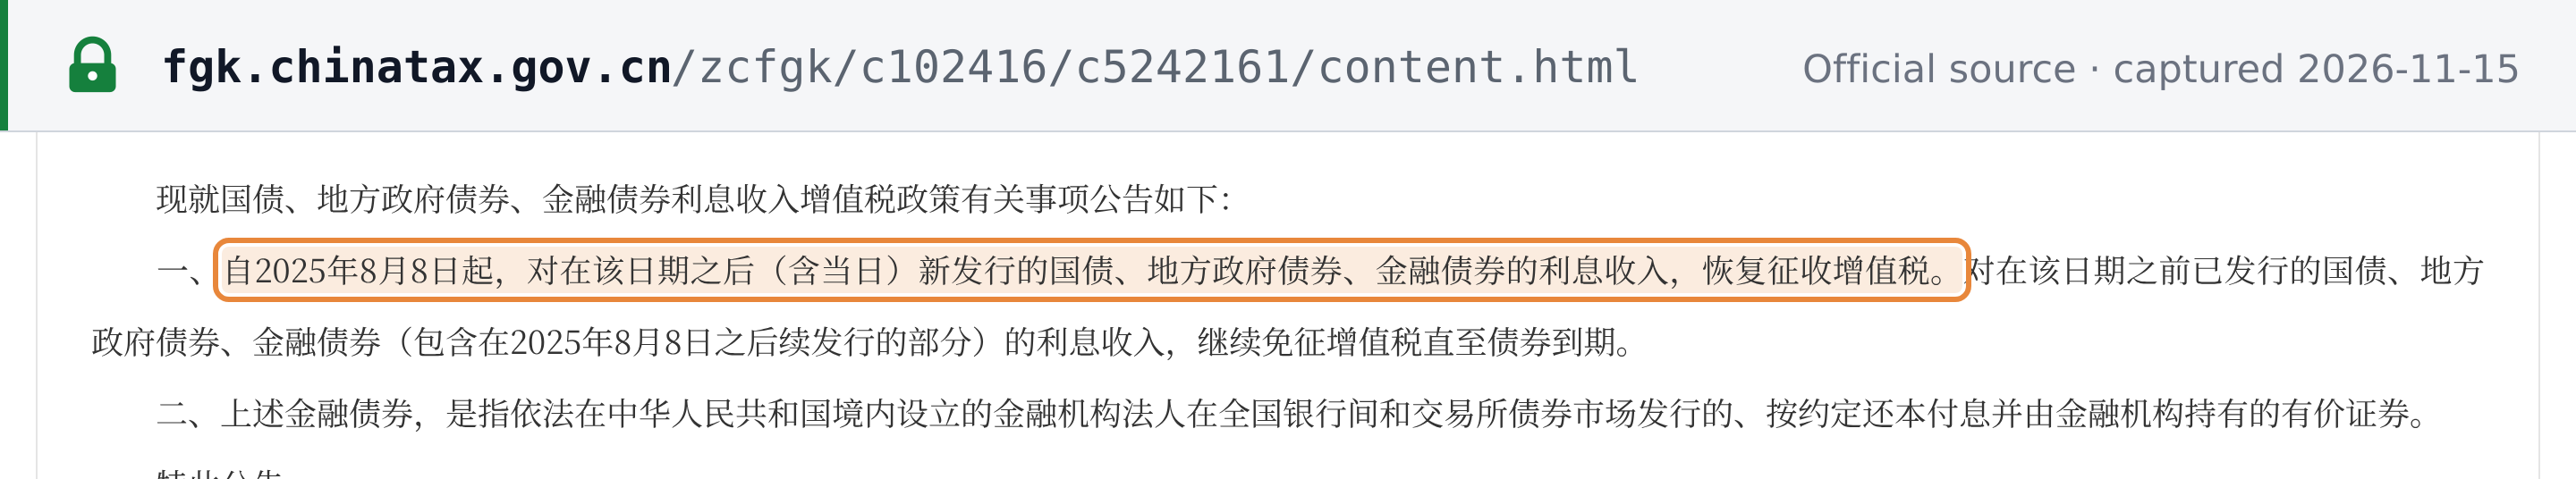 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · 财政部 税务总局公告2025年第4号(成文日期 2025-07-31),第一条、第二条 · fgk.chinatax.gov.cn