China sets import-VAT rules for Hainan's island-wide customs closure: zero-tariff first line, taxed second line
This page records one dated change. For the rules in China as they stand today, see the China guide →
- Jurisdiction
- China
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 18 July 2025
- Effective
- 18 December 2025
- Instrument
- CN-JOINT-NOTICE--2025-12
- Authority
- 财政部 海关总署 税务总局 (Ministry of Finance, General Administration of Customs and State Taxation Administration)
- Verified
- Fetched from official source · high confidence
Enterprises, public institutions and approved science and education non-profits registered in the Hainan Free Trade Port, and anyone moving zero-tariff goods to the mainland.
Entities operating in the Hainan FTP must determine whether they qualify as 享惠主体 and review supply chains accordingly. Goods entering from outside China's customs territory that are not on the dutiable catalogue are import-VAT-exempt at first line from 18 December 2025. Movement of goods to the mainland triggers import VAT and consumption tax on the imported inputs.
MOF, GAC and STA Notice 财关税〔2025〕12号, issued 18 July 2025 and in force from the start of Hainan Free Trade Port island-wide customs closure (18 December 2025), sets the tax rules for goods crossing the "first line" (abroad to Hainan), the "second line" (Hainan to the mainland) and moving within the island. Qualifying entities (享惠主体) importing goods not on the dutiable catalogue are exempt from import duty, import VAT and consumption tax; catalogued goods are taxed as normal. Zero-tariff goods and their products moving to the mainland, or to non-qualifying persons on the island, are charged import duty, import VAT and consumption tax on the imported inputs, with no import VAT again where domestic VAT was already paid on the island. Goods from encouraged-industry enterprises with island value-add of 30% or more enter the mainland free of import duty but bear import VAT and consumption tax.
What changed in detail
The Ministry of Finance, the General Administration of Customs and the State Taxation Administration issued Notice Caiguanshui [2025] No. 12 (财关税〔2025〕12号) on 18 July 2025. Under Article 14 it takes effect on the day Hainan’s island-wide customs closure starts. The NDRC announced that date on gov.cn as 18 December 2025.
First line (abroad to Hainan). Goods on a dutiable catalogue bear import duty, import VAT and consumption tax as normal. Qualifying entities (享惠主体) are exempt from all three on goods not on the catalogue. These entities are enterprises with independent legal-person status registered in the Free Trade Port, public institutions there, and approved science and education non-profits. An entity may choose to pay the import taxes instead, but cannot reapply for zero-tariff status on the same goods for 12 months.
Second line (Hainan to the mainland). Zero-tariff goods and their products pay import duty, import VAT and consumption tax on the imported inputs. Import VAT is not charged again where domestic VAT was already paid on the island. Goods made by encouraged-industry enterprises with island value-add of 30% or more enter the mainland free of import duty, but import VAT and consumption tax are charged as normal.
Within the island. Zero-tariff goods move between qualifying entities without import taxes being charged, but domestic VAT and consumption tax still apply. Goods transferred to non-qualifying persons or individuals pay the import taxes on their inputs.
What it means
The regime has applied since customs closure on 18 December 2025 and is still in force. For VAT the key test is entity status. Only a 享惠主体 imports VAT-free. Goods that leave the island for the mainland pick up import VAT on their inputs, even where island processing earns duty-free entry. Supply chains that route goods through Hainan should track which goods were imported zero-tariff, because the import VAT falls due when they cross the second line. The domestic-VAT side of the island still follows the VAT Law in force from 1 January 2026.
Proof
进口征税商品目录以外的货物,免征进口关税、进口环节增值税和消费税(以下简称“零关税”)。Goods outside the dutiable import catalogue [imported by qualifying entities] are exempt from import duty, import-stage VAT and consumption tax ("zero tariff").
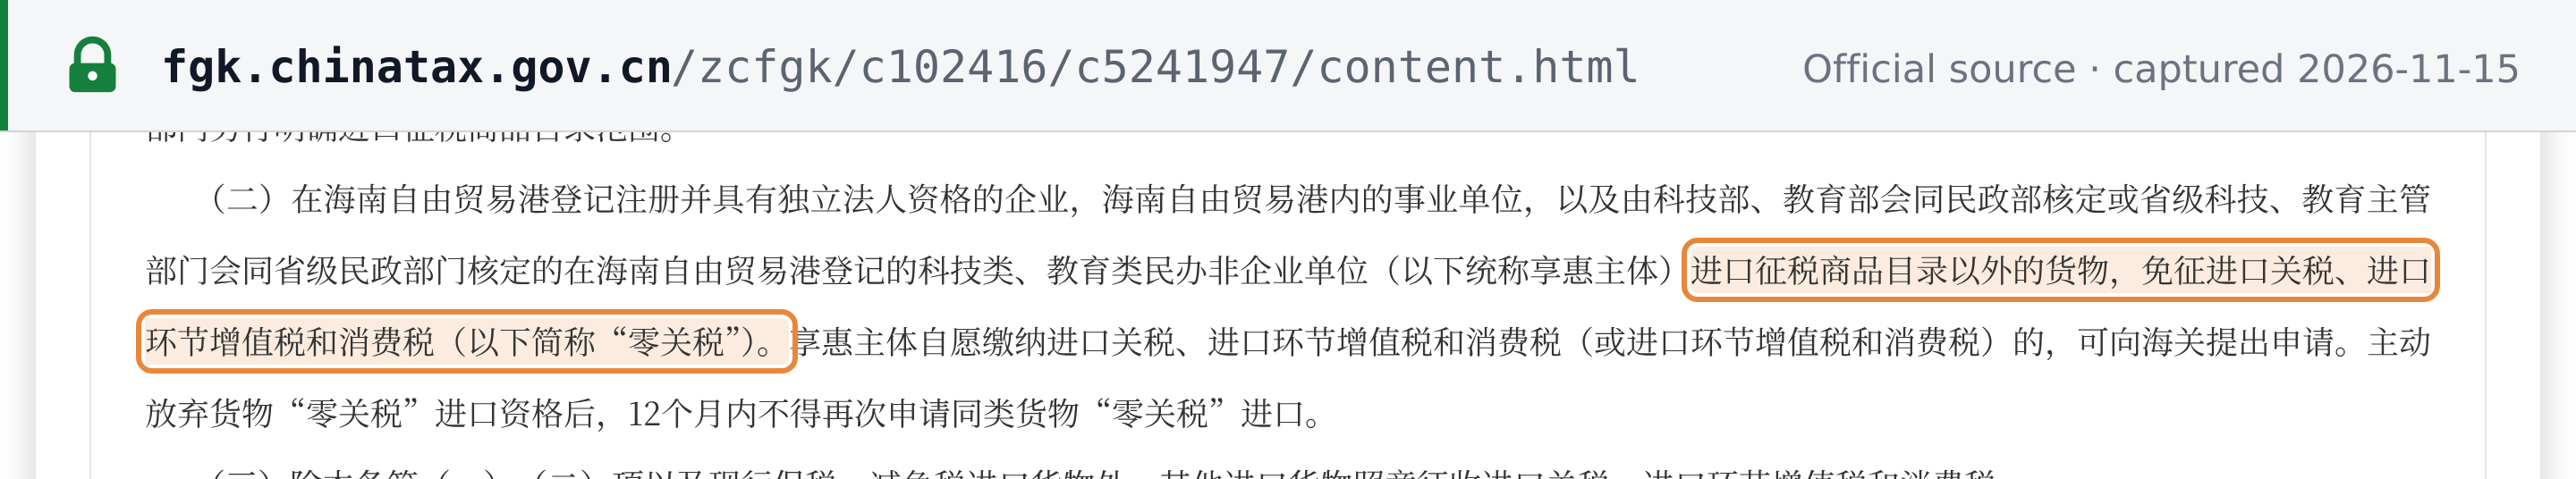 Source snapshot of the official page. Open full size ↗