Denmark abolishes the coffee duty from 1 January 2027 under Lov nr. 1000 of 17 November 2026
This page records one dated change. For the rules in Denmark as they stand today, see the Denmark guide →
- Jurisdiction
- Denmark
- Tax
- Excise
- Change type
- Rate change
- Status
- Enacted
- Impact
- Action required
- Announced
- 18 November 2026
- Effective
- 1 January 2027
- Authority
- Lovtidende / Retsinformation (Civilstyrelsen)
- Systems
- Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Danish importers, roasters and wholesalers registered for coffee duty under the Act on various consumption duties, including businesses holding duty-paid coffee stock on 1 January 2027.
Danish coffee importers, roasters and wholesalers registered for coffee duty: stop charging the duty from 1 January 2027 and claim the transitional refund on duty-paid stock within the deadline.
Tax engineReporting
Denmark's Lov nr. 1000 of 17 November 2026 (Afskaffelse af kaffeafgiften), enacted from bill L 36 A (passed 12 November 2026) and published in Lovtidende on 18 November 2026, repeals sections 11 and 11 a of the Act on various consumption duties (lov om forskellige forbrugsafgifter) with effect from 1 January 2027, abolishing the coffee duty. Businesses holding duty-paid coffee stock on 1 January 2027 can reclaim the duty on unopened bags or containers under transitional rules.
What changed in detail
Lov nr. 1000 of 17 November 2026 amending the Act on various consumption duties (lov om forskellige forbrugsafgifter), the Tax Assessment Act and several other acts was published in Lovtidende A on 18 November 2026. It was enacted from bill L 36 A, which the Folketing passed on 12 November 2026.
Section 1, no. 1 repeals sections 11 and 11 a of the consumption duties act, the provisions that impose the duty on coffee. Section 1, nos. 2 and 3 remove the references to section 11 from section 14 a. Under section 12(2), section 1 enters into force on 1 January 2027; the rest of the law, which covers income-tax deductions, inheritance duty and other matters, has its own dates.
Section 13 sets the transitional rule. A business that on 1 January 2027 holds stock of goods on which duty was paid under section 11 can, on the basis of a specified stock statement, have the duty refunded for unopened bags or containers. The refund covers only goods intended for production or sale, applies only where the duty exceeds DKK 500, and the request must reach the Danish customs and tax administration by 14 January 2027. The administration may require proof that the goods were not bought duty-free, and the business must comply with the accounting rules in section 15(2) and (4) of the consumption duties act.
What it means
Coffee sold from 1 January 2027 carries no Danish coffee duty, so price lists and duty-inclusive cost bases need to change at year end. The refund window is short: a stock count on 1 January and a claim filed by 14 January 2027. Opened bags or containers do not qualify, and claims of DKK 500 or less are not paid, so small holders may get nothing back. Duty registrations and returns for coffee should be closed off with the final December period.
Proof
§§ 11 og 11 a ophæves.Sections 11 and 11 a are repealed.
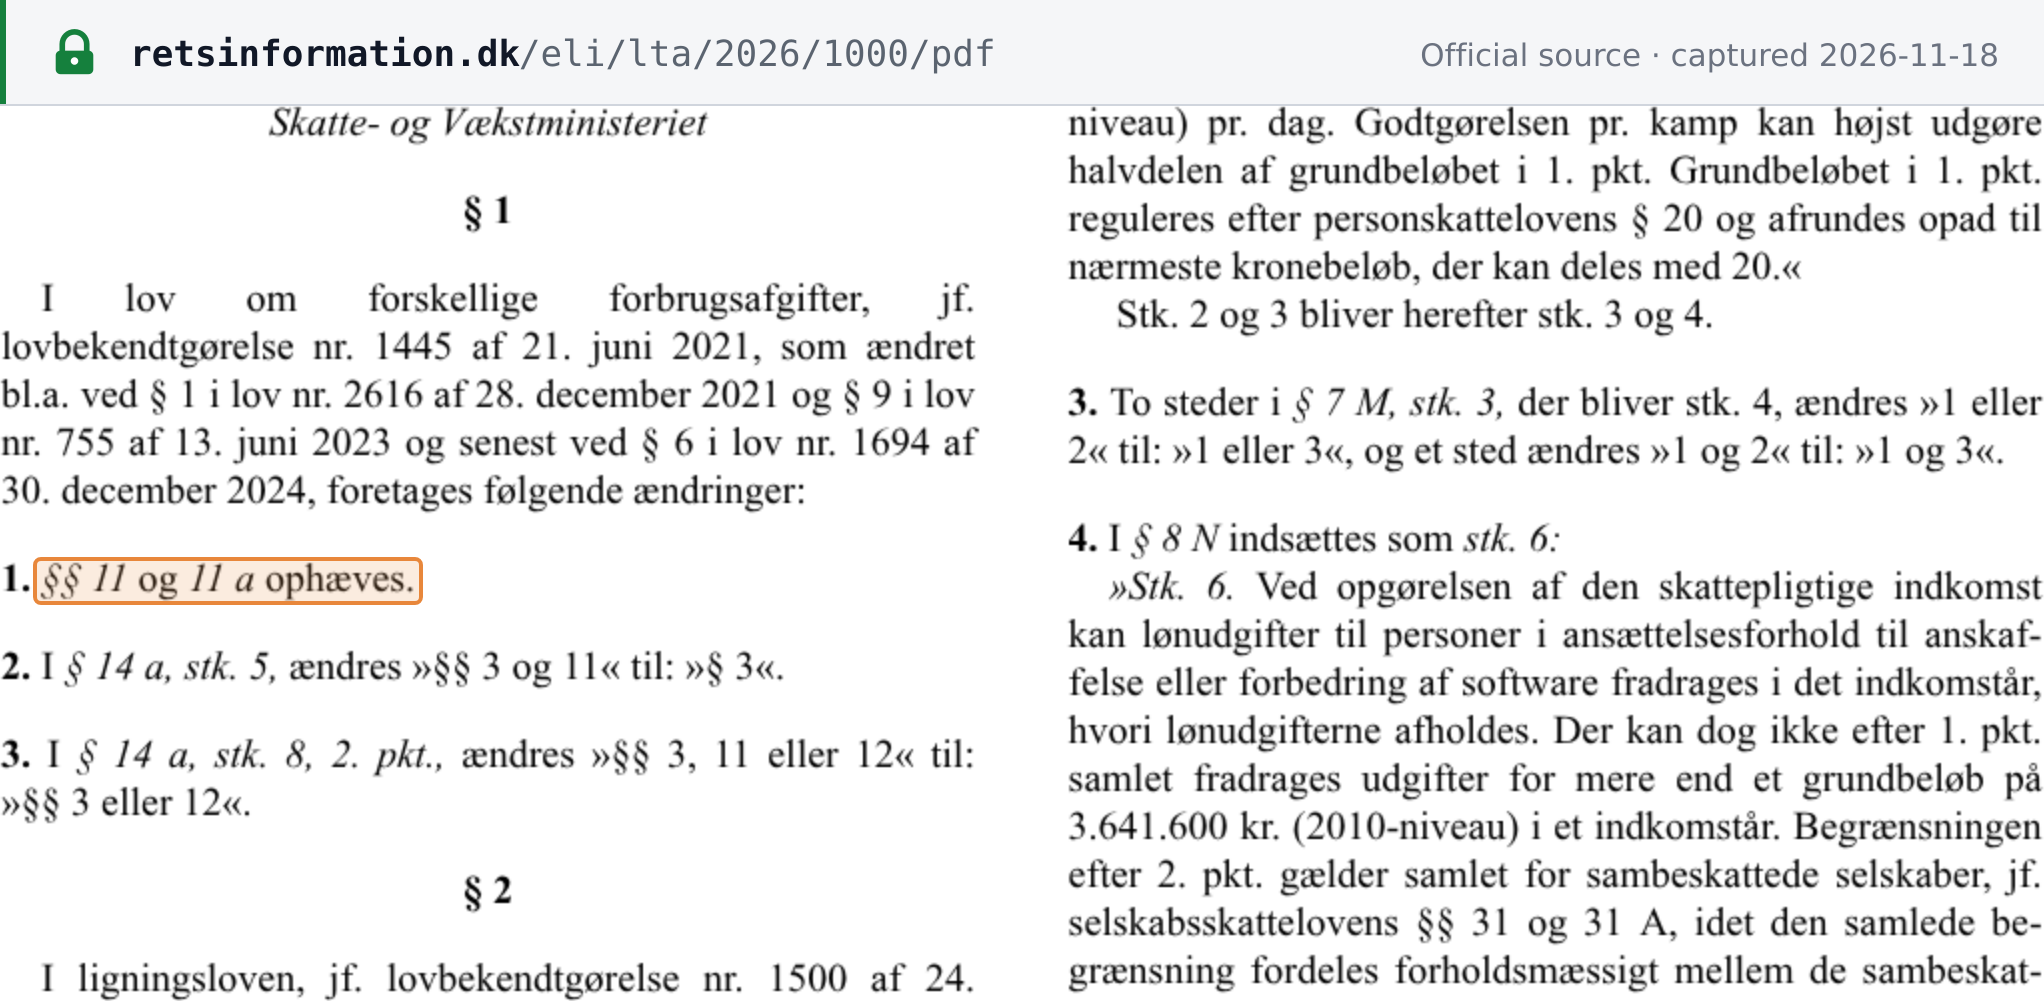 Source snapshot of the official page. Open full size ↗
Stk. 2. §§ 1, 4, 5, 11 og 13 træder i kraft den 1. januar 2027.Subsection 2. Sections 1, 4, 5, 11 and 13 enter into force on 1 January 2027.
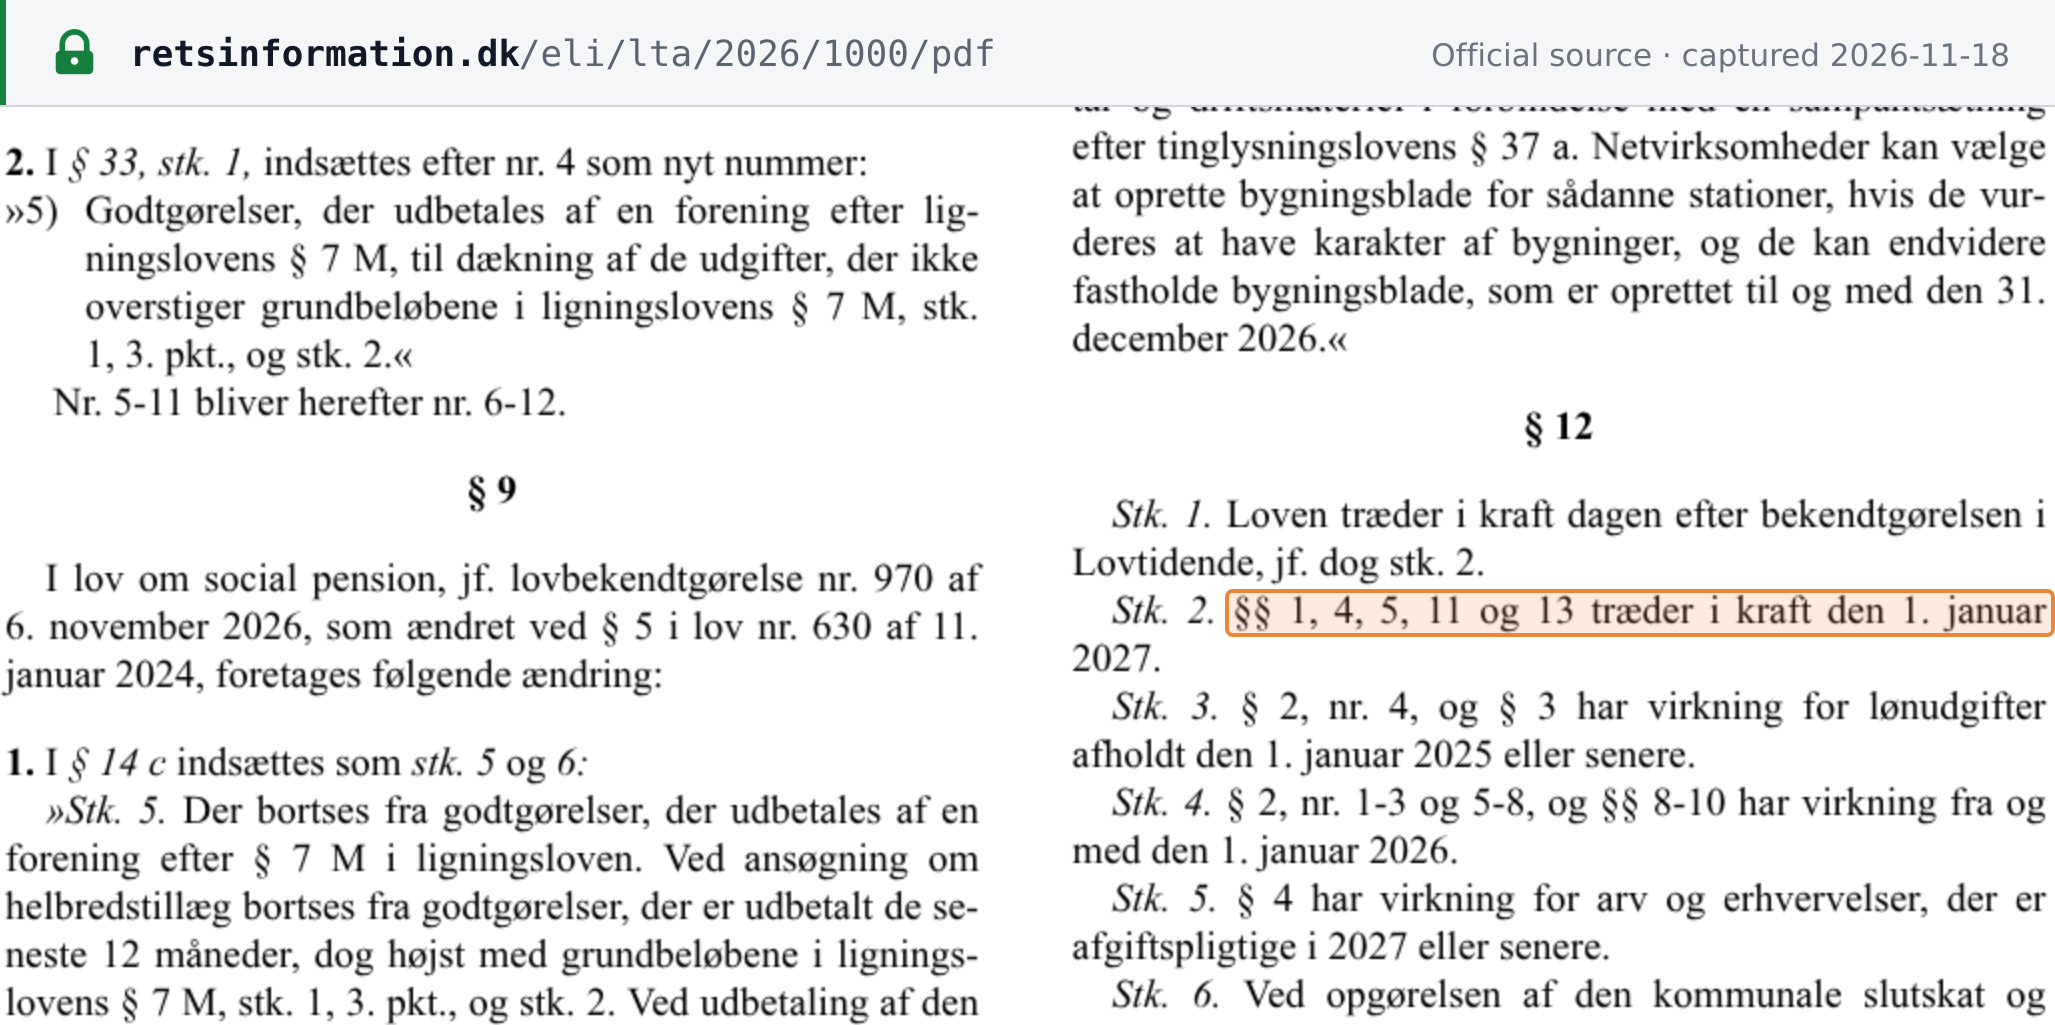 Source snapshot of the official page. Open full size ↗