Denmark zero-rates books and e-books from 1 July 2027 under Lov nr. 1001 of 17 November 2026
This page records one dated change. For the rules in Denmark as they stand today, see the Denmark guide →
- Jurisdiction
- Denmark
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Action required
- Announced
- 18 November 2026
- Effective
- 1 July 2027
- Authority
- Lovtidende / Retsinformation (Civilstyrelsen)
- Systems
- Tax engine, POS, E-commerce
- Verified
- Fetched from official source · high confidence
Publishers, booksellers and other businesses supplying printed books or electronically supplied books in Denmark.
Sellers of printed books and e-books in Denmark: apply 0% VAT (with deduction rights) from 1 July 2027 and update rates in POS and e-commerce systems.
Tax enginePOSE-commerce
Denmark's Lov nr. 1001 of 17 November 2026 amending the VAT Act (momsloven), enacted from bill L 36 B (passed 12 November 2026) and published in Lovtidende on 18 November 2026, adds the supply of books, including electronically supplied books, to the zero-rated supplies in section 34(1), no. 18 of momsloven. The law enters into force on 1 July 2027.
What changed in detail
Lov nr. 1001 of 17 November 2026 amending the VAT Act (momsloven), titled “Indførelse af nulmoms på bøger” (introduction of zero VAT on books), was published in Lovtidende A on 18 November 2026. It was enacted from bill L 36 B, which the Folketing passed on 12 November 2026.
Its single amendment inserts, in section 34(1), no. 18 of momsloven, after the word “månedligt”, the words ”, og levering af bøger, herunder elektronisk leverede bøger”. Section 34(1) lists supplies that are exempt from VAT with the right to deduct input VAT, which is how Denmark applies a 0% rate; no. 18 already covered newspapers published at least monthly. Books, including electronically supplied books, are added to that list.
Under section 2 the law enters into force on 1 July 2027. A footnote states that the law implements parts of Council Directive (EU) 2022/542, the 2022 VAT rates directive that allows Member States to apply reduced and zero rates to books.
What it means
Until 30 June 2027 books stay at the standard 25% rate. From 1 July 2027 sellers of printed books and e-books charge 0% while keeping full input VAT deduction, so systems need a new tax code with deduction rights, not an exempt code. The amendment says “books”, not printed matter in general, so bundles and borderline products are worth checking against Skattestyrelsen guidance when it appears. This law replaces the bill-stage record for L 36.
Proof
levering af bøger, herunder elektronisk leverede bøger«.supply of books, including electronically supplied books».
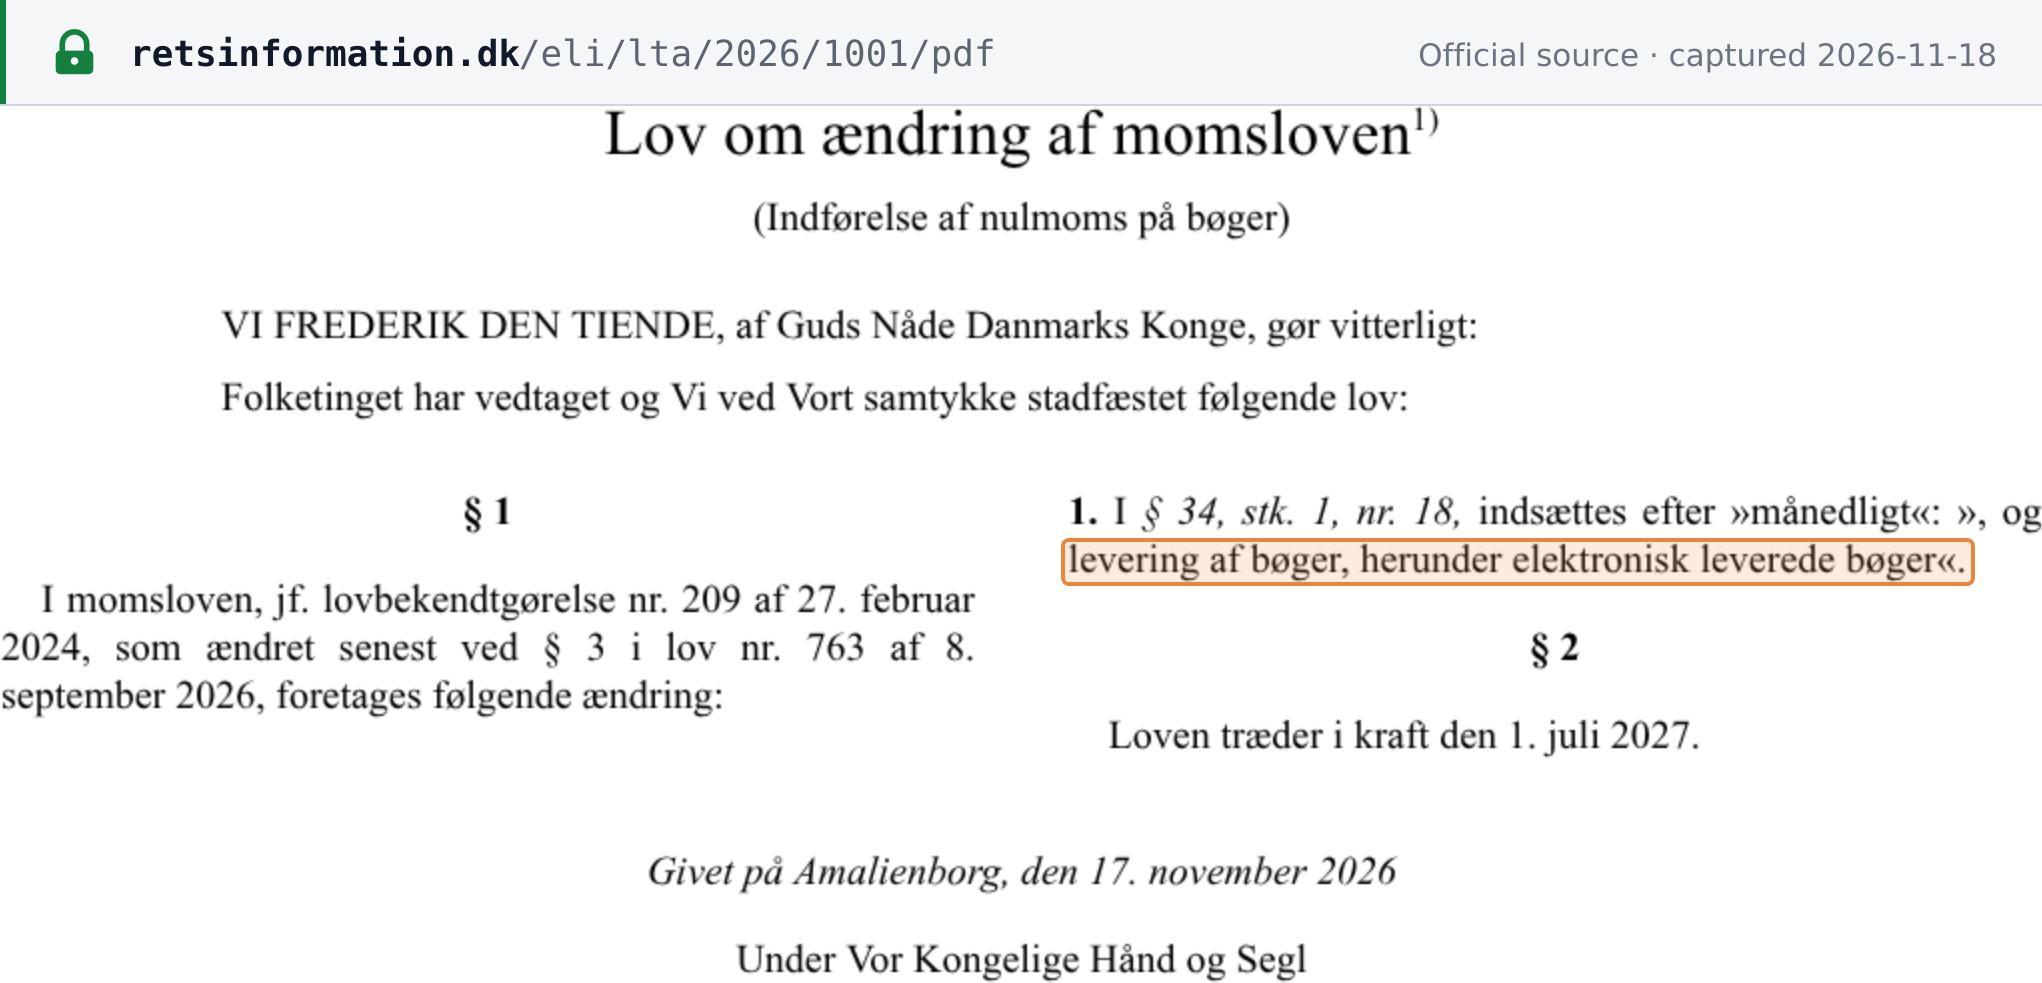 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Denmark tables bill L 36 to zero-rate books for VAT from 1 July 2027 effective 1 July 2027