Estonia raises VAT on accommodation to 13% and on press publications to 9% from 1 January 2025
This page records one dated change. For the rules in Estonia as they stand today, see the Estonia guide →
- Jurisdiction
- Estonia
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 1 January 2025
- Effective
- 1 January 2025
- Instrument
- EE-ACT-RT-I-01-07-2023-2
- Authority
- Eesti Maksu- ja Tolliamet (Estonian Tax and Customs Board)
- Verified
- Fetched from official source · high confidence
Hotels and other accommodation providers, and publishers and sellers of printed and electronic press publications, in Estonia.
No action — monitoring only.
In force from 1 January 2025: under the Käibemaksuseaduse muutmise seadus adopted on 19 June 2023 and published on 1 July 2023 (RT I, 01.07.2023, 2), Estonia's VAT rate on accommodation and accommodation with breakfast rose from 9% to 13% (new § 15(1^1)), and printed and electronic press publications moved from the 5% rate to the 9% rate. Taxpayers using cash-basis VAT accounting may apply the old 9% (accommodation) or 5% (press) rate until 31 December 2026 to supplies invoiced and provided before 1 January 2025.
What changed in detail
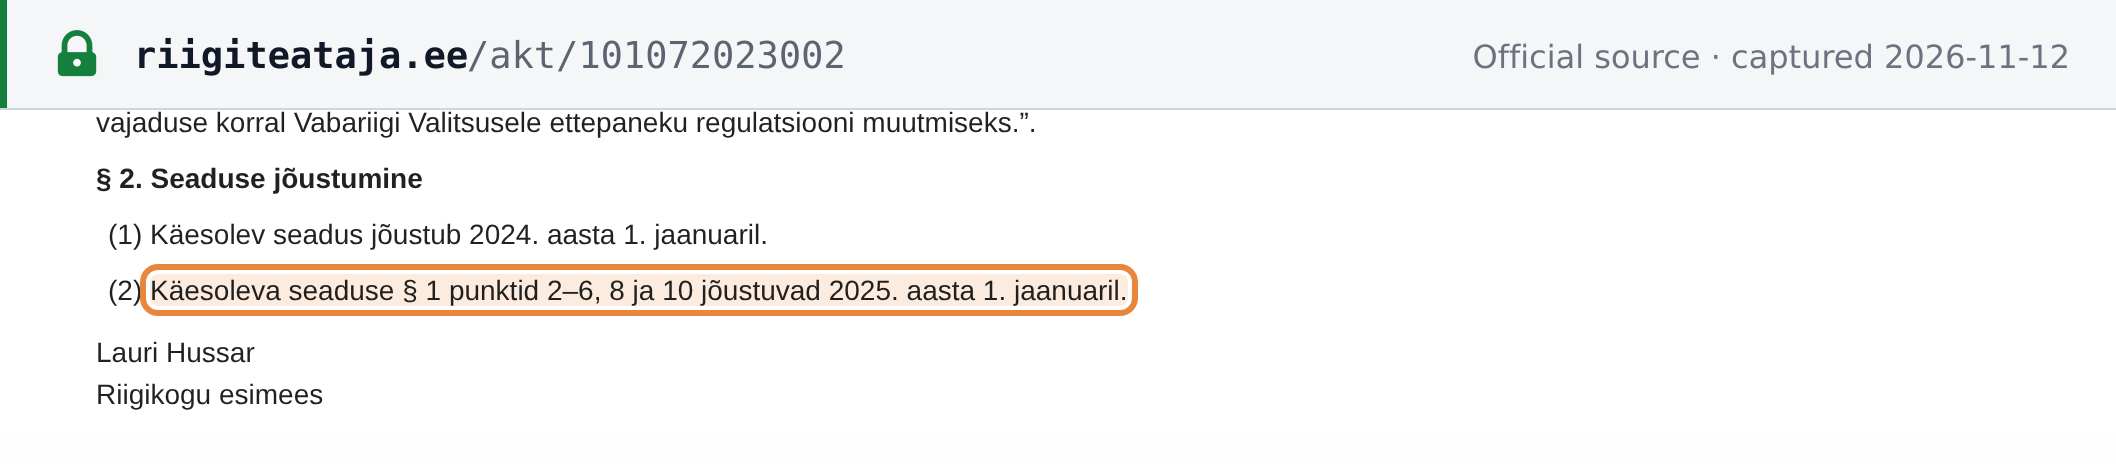
From 1 January 2025 two Estonian reduced rates changed. Both changes were made by the Käibemaksuseaduse muutmise seadus, adopted by the Riigikogu on 19 June 2023 and published in Riigi Teataja on 1 July 2023 as RT I, 01.07.2023, 2, the same Act that raised the standard rate to 22% in 2024. Its § 2(2) put the relevant points in force on 1 January 2025:
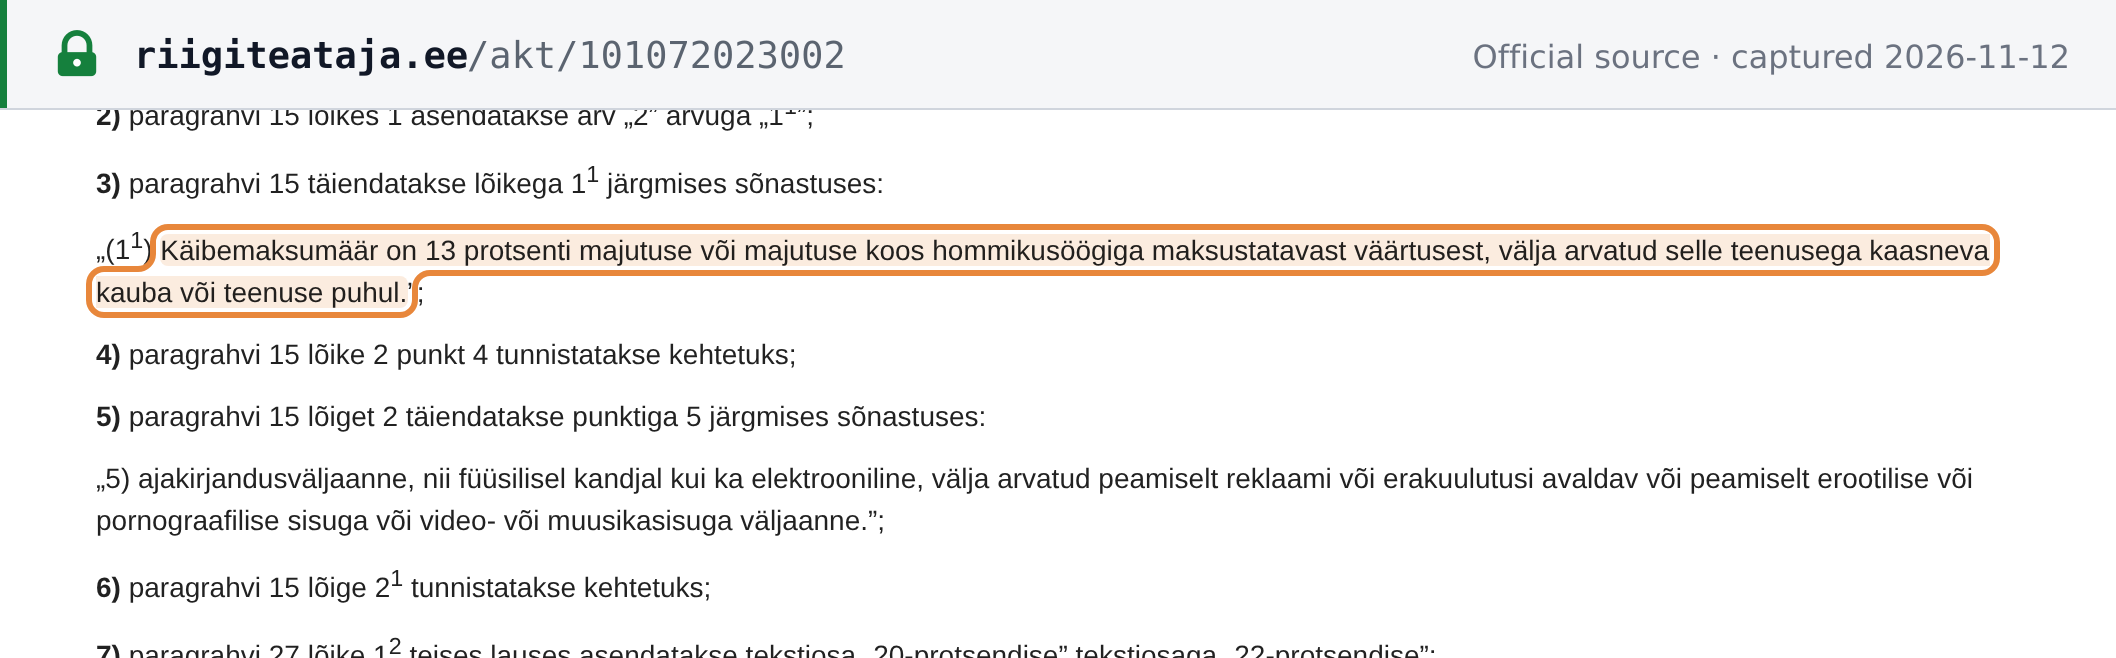
- Accommodation: a new § 15(1¹) of the VAT Act taxes accommodation and accommodation with breakfast at 13%, except for goods or services that accompany the service. Accommodation was removed from the 9% list (§ 15(2)(4) repealed).
- Press publications: printed and electronic press publications were added to the 9% list as § 15(2)(5), and the 5% rate in § 15(2¹) was repealed. Publications mainly carrying advertising or classified ads, or mainly erotic, pornographic, video or music content, are excluded.
New § 46(26)–(27) let taxpayers using cash-basis VAT accounting pay the old rate (9% for accommodation, 5% for press) until 31 December 2026 on supplies taxed after 31 December 2024 where the invoice was issued and the service or goods provided before 1 January 2025.
What it means
Both rates are still in force: the consolidated VAT Act (RT I, 30.06.2026, 129) carries the 13% accommodation rate in § 15(1¹) and press publications at 9% in § 15(2)(5). Estonia no longer has a 5% rate.
The rise in the standard rate to 24% on 1 July 2025 (Estonia raises VAT to 24%) did not touch these reduced rates. The breakfast itself is part of the 13% service, but other goods or services sold with a room take their own rate. The cash-basis transition closes on 31 December 2026, after which any late-collected pre-2025 supplies are taxed at the new rates.
Proof
From 1 January 2025, accommodation services and accommodation services with breakfast are taxed at 13% VAT rate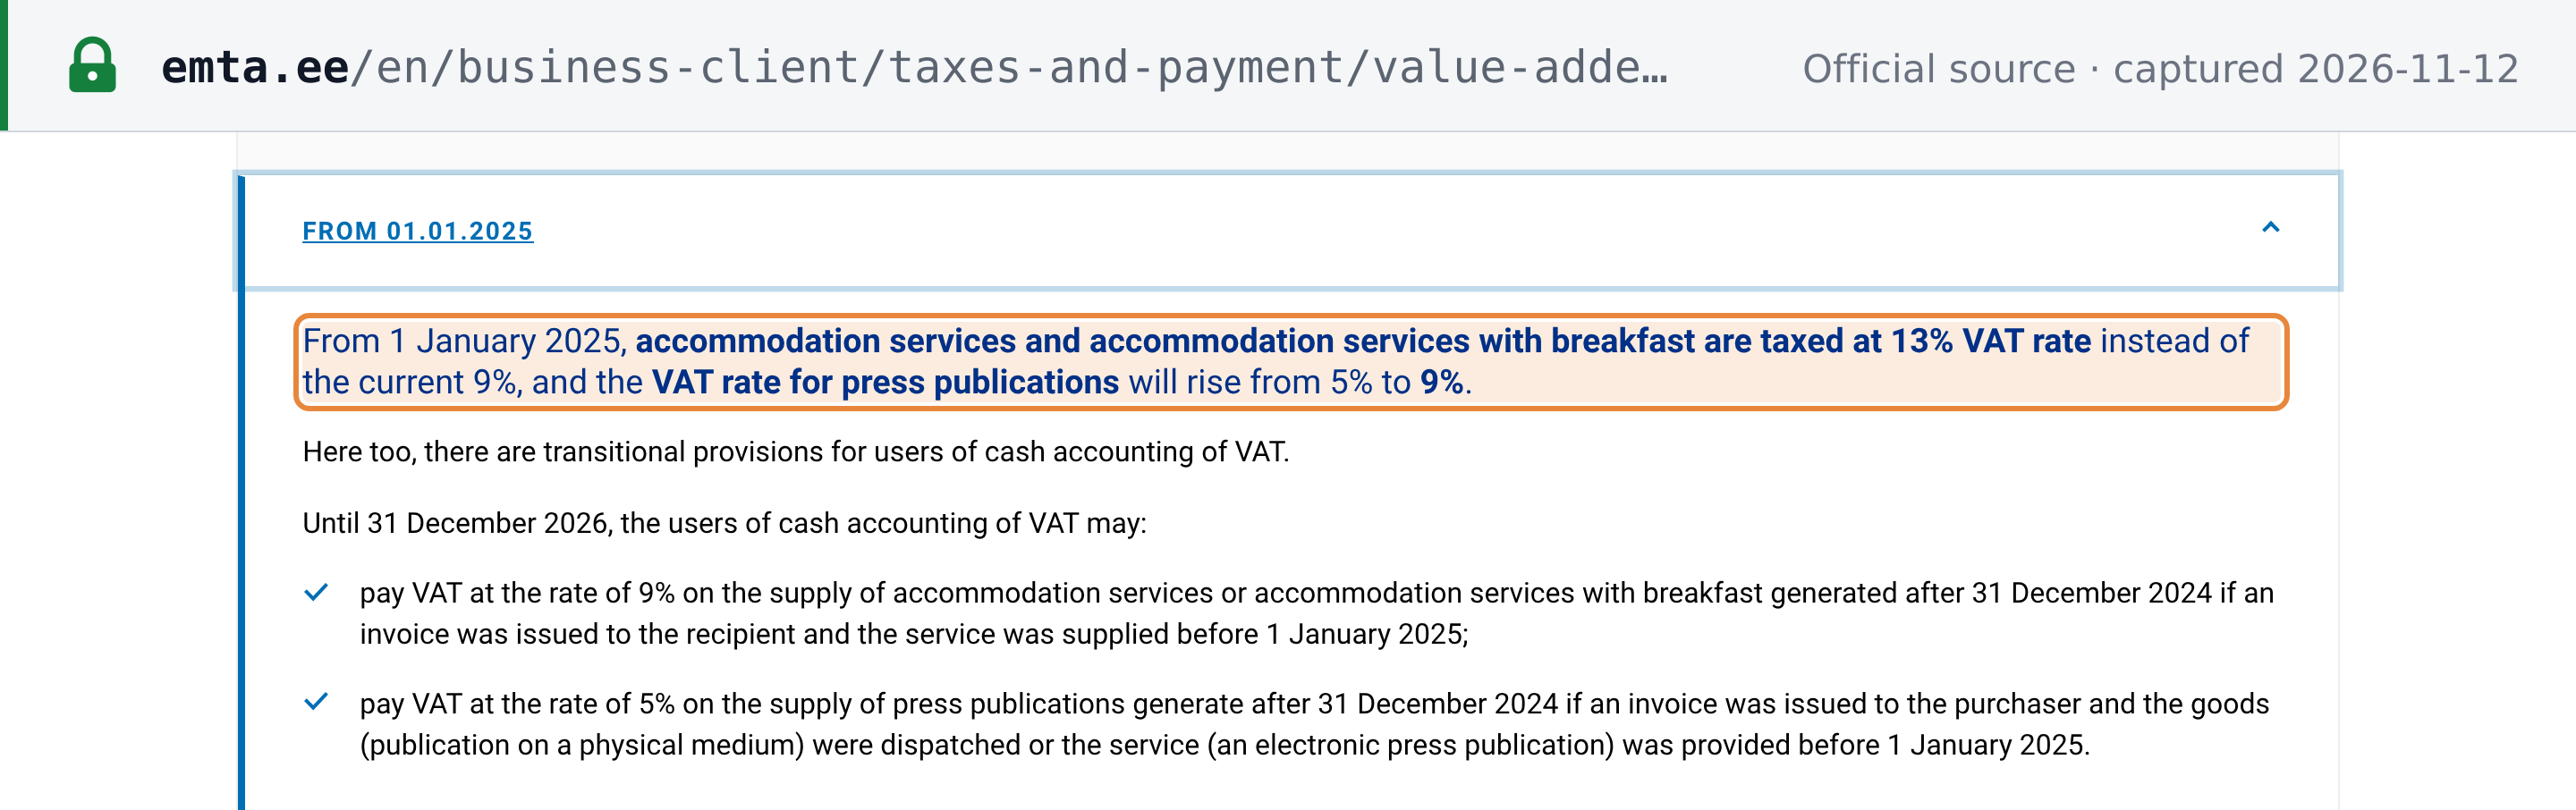 Source snapshot of the official page. Open full size ↗
Käibemaksumäär on 13 protsenti majutuse või majutuse koos hommikusöögiga maksustatavast väärtusest, välja arvatud selle teenusega kaasneva kauba või teenuse puhul.The VAT rate is 13 per cent of the taxable value of accommodation or accommodation with breakfast, except for goods or services accompanying that service.
 Source snapshot of the official page. Open full size ↗
Käesoleva seaduse § 1 punktid 2–6, 8 ja 10 jõustuvad 2025. aasta 1. jaanuaril.Points 2–6, 8 and 10 of § 1 of this Act enter into force on 1 January 2025.
 Source snapshot of the official page. Open full size ↗