Estonia adopts the EU SME scheme: small businesses can use VAT exemptions in other Member States from 1 January 2025
This page records one dated change. For the rules in Estonia as they stand today, see the Estonia guide →
- Jurisdiction
- Estonia
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- Action required
- Announced
- 3 December 2024
- Effective
- 1 January 2025
- Instrument
- EE-ACT-RT-I-03-12-2024-2
- Authority
- Riigi Teataja
- Verified
- Fetched from official source · high confidence
Estonian-established businesses with EU-wide turnover of EUR 100,000 or less that supply in other EU states, and small EU businesses supplying in Estonia.
Estonian businesses making supplies in other EU states may apply the cross-border SME exemption without registration in those states; eligible businesses should register with EMTA through the electronic portal before supplying abroad.
Käibemaksuseaduse ja maksukorralduse seaduse muutmise seadus, adopted by the Riigikogu on 13 November 2024, proclaimed 13 November 2024 (President's Resolution No. 475), published in Riigi Teataja on 3 December 2024 (RT I, 03.12.2024, 2), in force 1 January 2025 (most provisions): transposed the EU SME scheme (Directive 2020/285). New § 19^1 'Väikeettevõtete erikord' (Small enterprise special scheme) allows Estonian-established businesses to apply a cross-border VAT exemption in other EU Member States without registering there, subject to: (a) EU-wide annual turnover not exceeding EUR 100,000 (current and prior year); (b) the other Member State's domestic threshold not being exceeded; and (c) prior notification to the home-state tax authority with receipt of a registration number carrying the EX suffix. Corresponding provisions for inbound EU businesses are in § 19(1^1). § 19(1) was also restated to clarify that the EUR 40,000 Estonian VAT-registration threshold is calculated by reference to the § 19^1(3) EU-wide turnover formula.
What changed in detail
The Käibemaksuseaduse ja maksukorralduse seaduse muutmise seadus (Act amending the Value Added Tax Act and the Taxation Act) was adopted by the Riigikogu on 13 November 2024, proclaimed by the President the same day (Resolution No. 475) and published as RT I, 03.12.2024, 2. Most of it entered into force on 1 January 2025. It transposes the EU SME scheme of Council Directive (EU) 2020/285.
New § 19¹ “Väikeettevõtete erikord” (small enterprise special scheme) lets an Estonian-established business apply the small-business VAT exemption of another Member State without registering for VAT there. The scheme applies where:
- the business’s EU-wide turnover, including Estonia, does not exceed EUR 100,000 in the current or the previous calendar year;
- its turnover in the other Member State stays within that state’s own exemption threshold;
- it has given prior notification to the Estonian Tax and Customs Board through the electronic portal, and received an identification number with the EX suffix.
New § 19(1¹) sets the mirror rules for businesses established in other Member States that use the scheme for supplies in Estonia. Restated § 19(1) keeps Estonia’s EUR 40,000 registration threshold, now measured by the turnover formula in § 19¹(3). Some points of the Act, including folding the EC sales list into the VAT return, take effect only on 1 January 2027.
What it means
The scheme is in force. It is optional: a small Estonian business selling into, say, Finland or Latvia can stay unregistered there and use that country’s exemption, but only after notifying the Estonian Tax and Customs Board and getting its EX number. Without that step the old rule applies and registration abroad is needed.
The EUR 100,000 cap counts turnover in every Member State together, so a business that crosses it mid-year loses the scheme everywhere at once. Estonia’s own EUR 40,000 threshold is unchanged in amount, but the way turnover is counted now follows the EU-wide formula.
Proof
Ettevõtlusega tegeleval Eestis asukohta omaval isikul ei teki teises liikmesriigis käibe tekkimise korral kohustust ennast selles teises liikmesriigis maksukohustuslasena registreerida, kui ta rakendab käesolevas paragrahvis sätestatud väikeettevõtete erikorda (edaspidi käesolevas paragrahvis erikord).An Estonian-established business person is not obliged to register as a taxable person in another Member State in which a taxable supply arises, if that person applies the special scheme for small enterprises provided in this section (hereinafter in this section: special scheme).
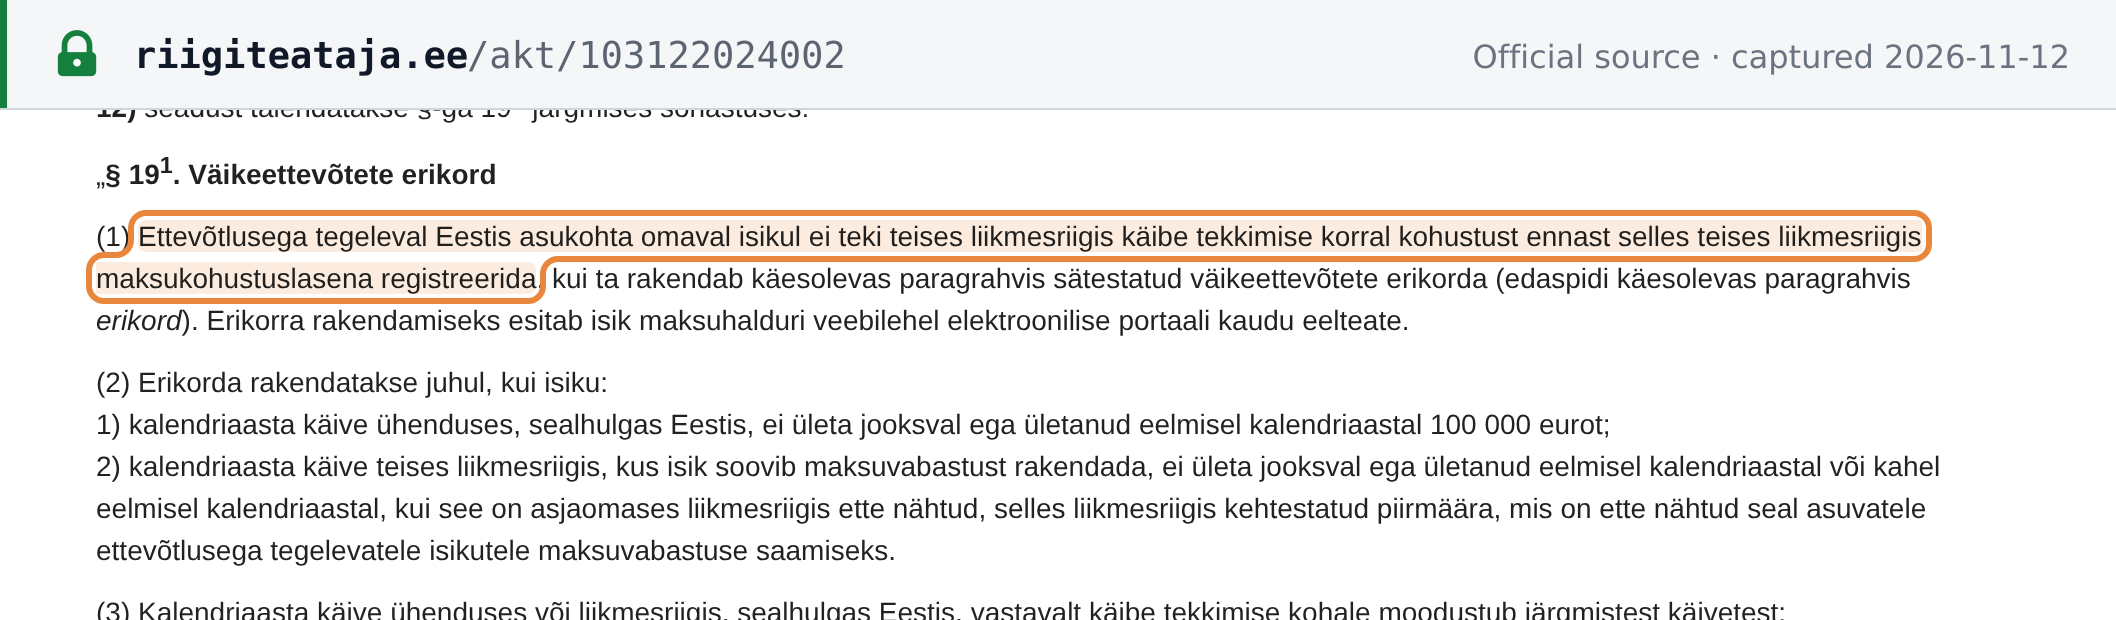 Source snapshot of the official page. Open full size ↗