EU opens the small-business VAT exemption to businesses from other Member States from 1 January 2025
This page records one dated change. For the rules in European Union as they stand today, see the European Union guide →
- Jurisdiction
- European Union
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- Plan ahead
- Announced
- 1 January 2025
- Effective
- 1 January 2025
- Instrument
- EU-DIRECTIVE-2020-285
- Authority
- Official Journal of the European Union (EUR-Lex)
- Verified
- Fetched from official source · high confidence
Small businesses established in an EU Member State with Union annual turnover up to EUR 100,000 that supply goods or services in other Member States.
Small enterprises expanding across EU borders should assess eligibility for the cross-border exemption scheme.
Council Directive (EU) 2020/285 of 18 February 2020 amending Directive 2006/112/EC introduces a cross-border SME VAT exemption scheme from 1 January 2025: small enterprises established in the EU may claim VAT exemption in other Member States provided their EU-wide annual turnover does not exceed EUR 100,000 and their sales in each Member State do not exceed that state's national threshold (capped at EUR 85,000). Enterprises must notify their home Member State and receive an individual identification number with an 'EX' suffix. Applies from 1 January 2025.
What changed in detail
Council Directive (EU) 2020/285 of 18 February 2020, published in OJ L 62 on 2 March 2020, rewrites the special scheme for small enterprises in Title XII, Chapter 1 of the VAT Directive and amends Regulation (EU) No 904/2010 for the related information exchange. Member States had to transpose it by 31 December 2024 and apply it from 1 January 2025 (Article 3); the administrative-cooperation part (Article 2) also applies from that date (Article 4).
- Domestic thresholds. A Member State may exempt small businesses established on its territory whose turnover there does not exceed a threshold it sets, which may be no higher than EUR 85,000 or the national-currency equivalent, including sector thresholds (new Article 284(1)).
- Cross-border access. A Member State applying the exemption must also grant it to businesses established in another Member State if their Union annual turnover does not exceed EUR 100,000 and their supplies in that Member State stay within its own threshold (Article 284(2)).
- Procedure. The business notifies its Member State of establishment in advance and receives an individual identification number carrying the suffix “EX” for the exemption in each Member State concerned (Article 284(3)).
Directive (EU) 2022/542 later replaced the turnover-reference rule in Article 288 before it applied.
What it means
The scheme has been live since January 2025 and remains the current rule. It does not create a single EU threshold: each Member State still sets its own figure up to EUR 85,000, and the EUR 100,000 Union-wide cap is what decides eligibility for using other states’ exemptions. The amended turnover rule came in with Directive (EU) 2022/542, which applies from the same date. A business whose EU turnover passes EUR 100,000 loses the exemption in every Member State other than its own from that moment, must tell its home state within 15 working days, and then registers normally where it supplies. The scheme also adds quarterly reporting of supplies per Member State.
Proof
That threshold shall be no higher than EUR 85 000 or the equivalent in national currency.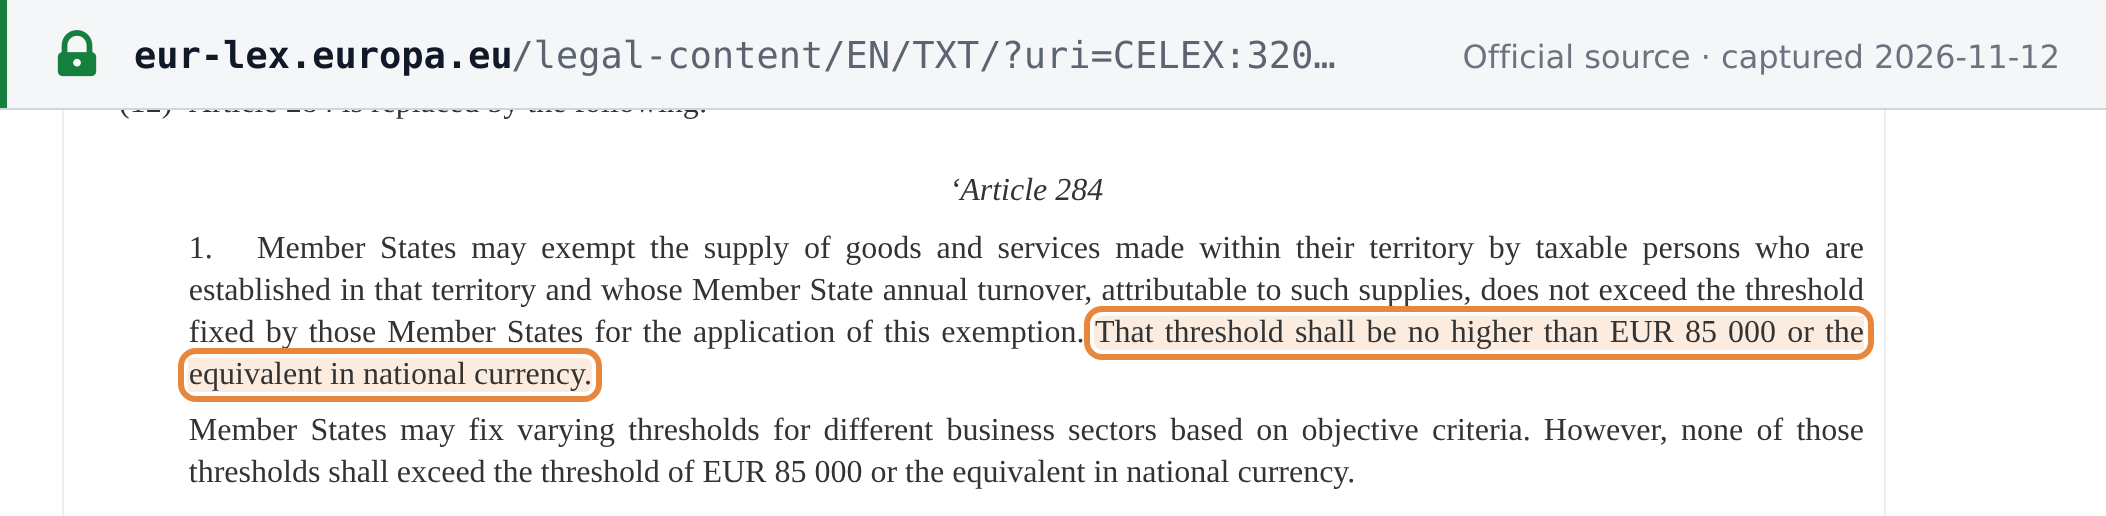 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Council Directive (EU) 2020/285 of 18 February 2020 · OJ L 62, 2.3.2020, p. 13 · publications.europa.eu
They shall apply those provisions from 1 January 2025.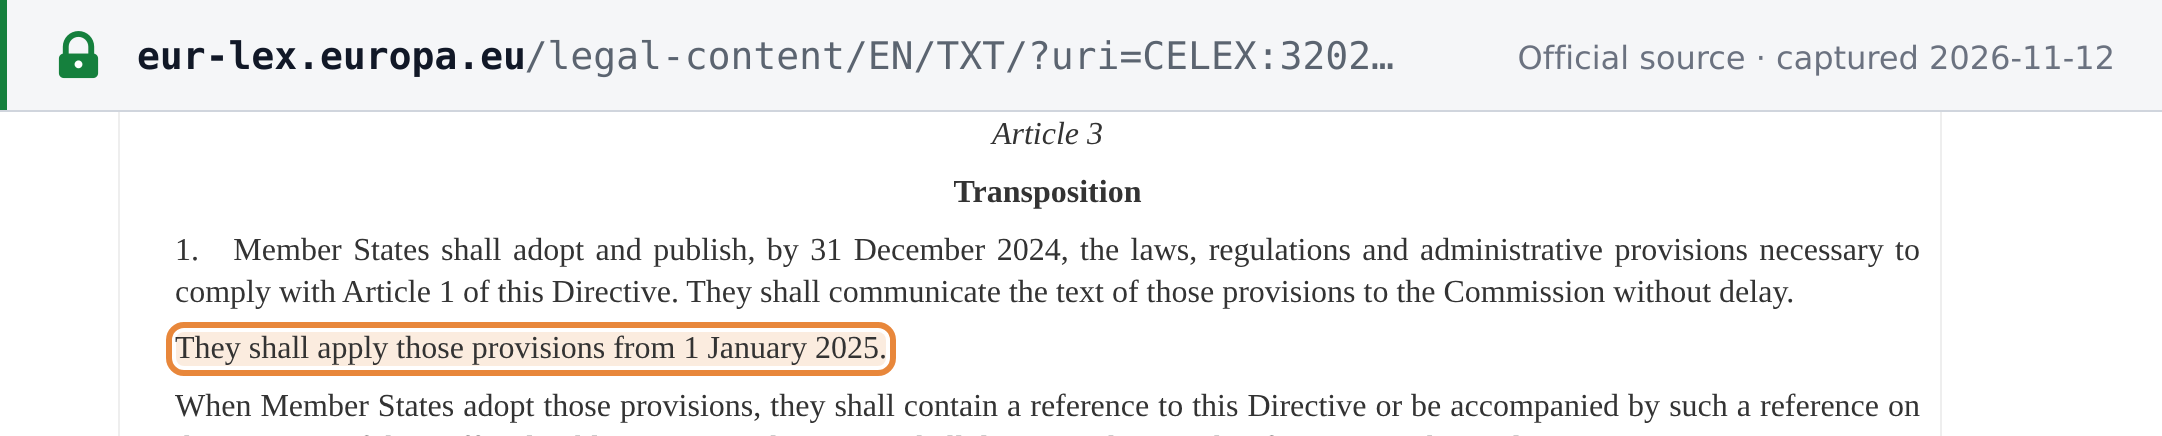 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Council Directive (EU) 2020/285 of 18 February 2020 · OJ L 62, 2.3.2020, p. 13 · publications.europa.eu